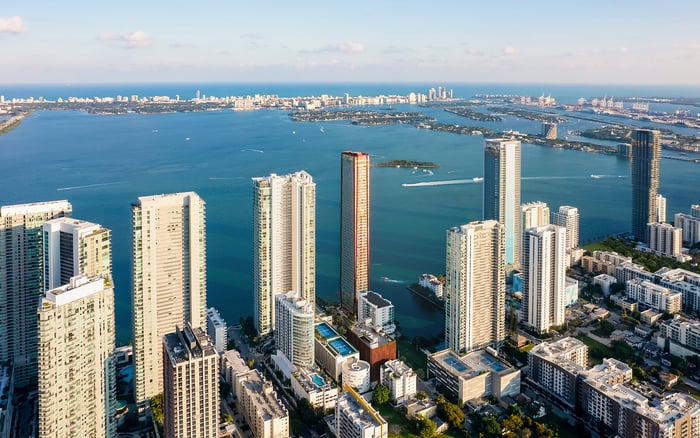
South Florida’s September 2025 luxury market accelerated across Miami, Miami Beach, Brickell, Fort Lauderdale, Palm Beach, Sunny Isles Beach, and Bay Harbor Islands. Dollar volume rose double digits, absorption tightened to 4.2 months, and ultra-luxury ($10M+) sales tracked near record pace. Cash and international demand remained dominant, while new construction condominiums and waterfront estates saw the fastest turn. Despite price gains, Miami still offers compelling relative value among global gateway cities.
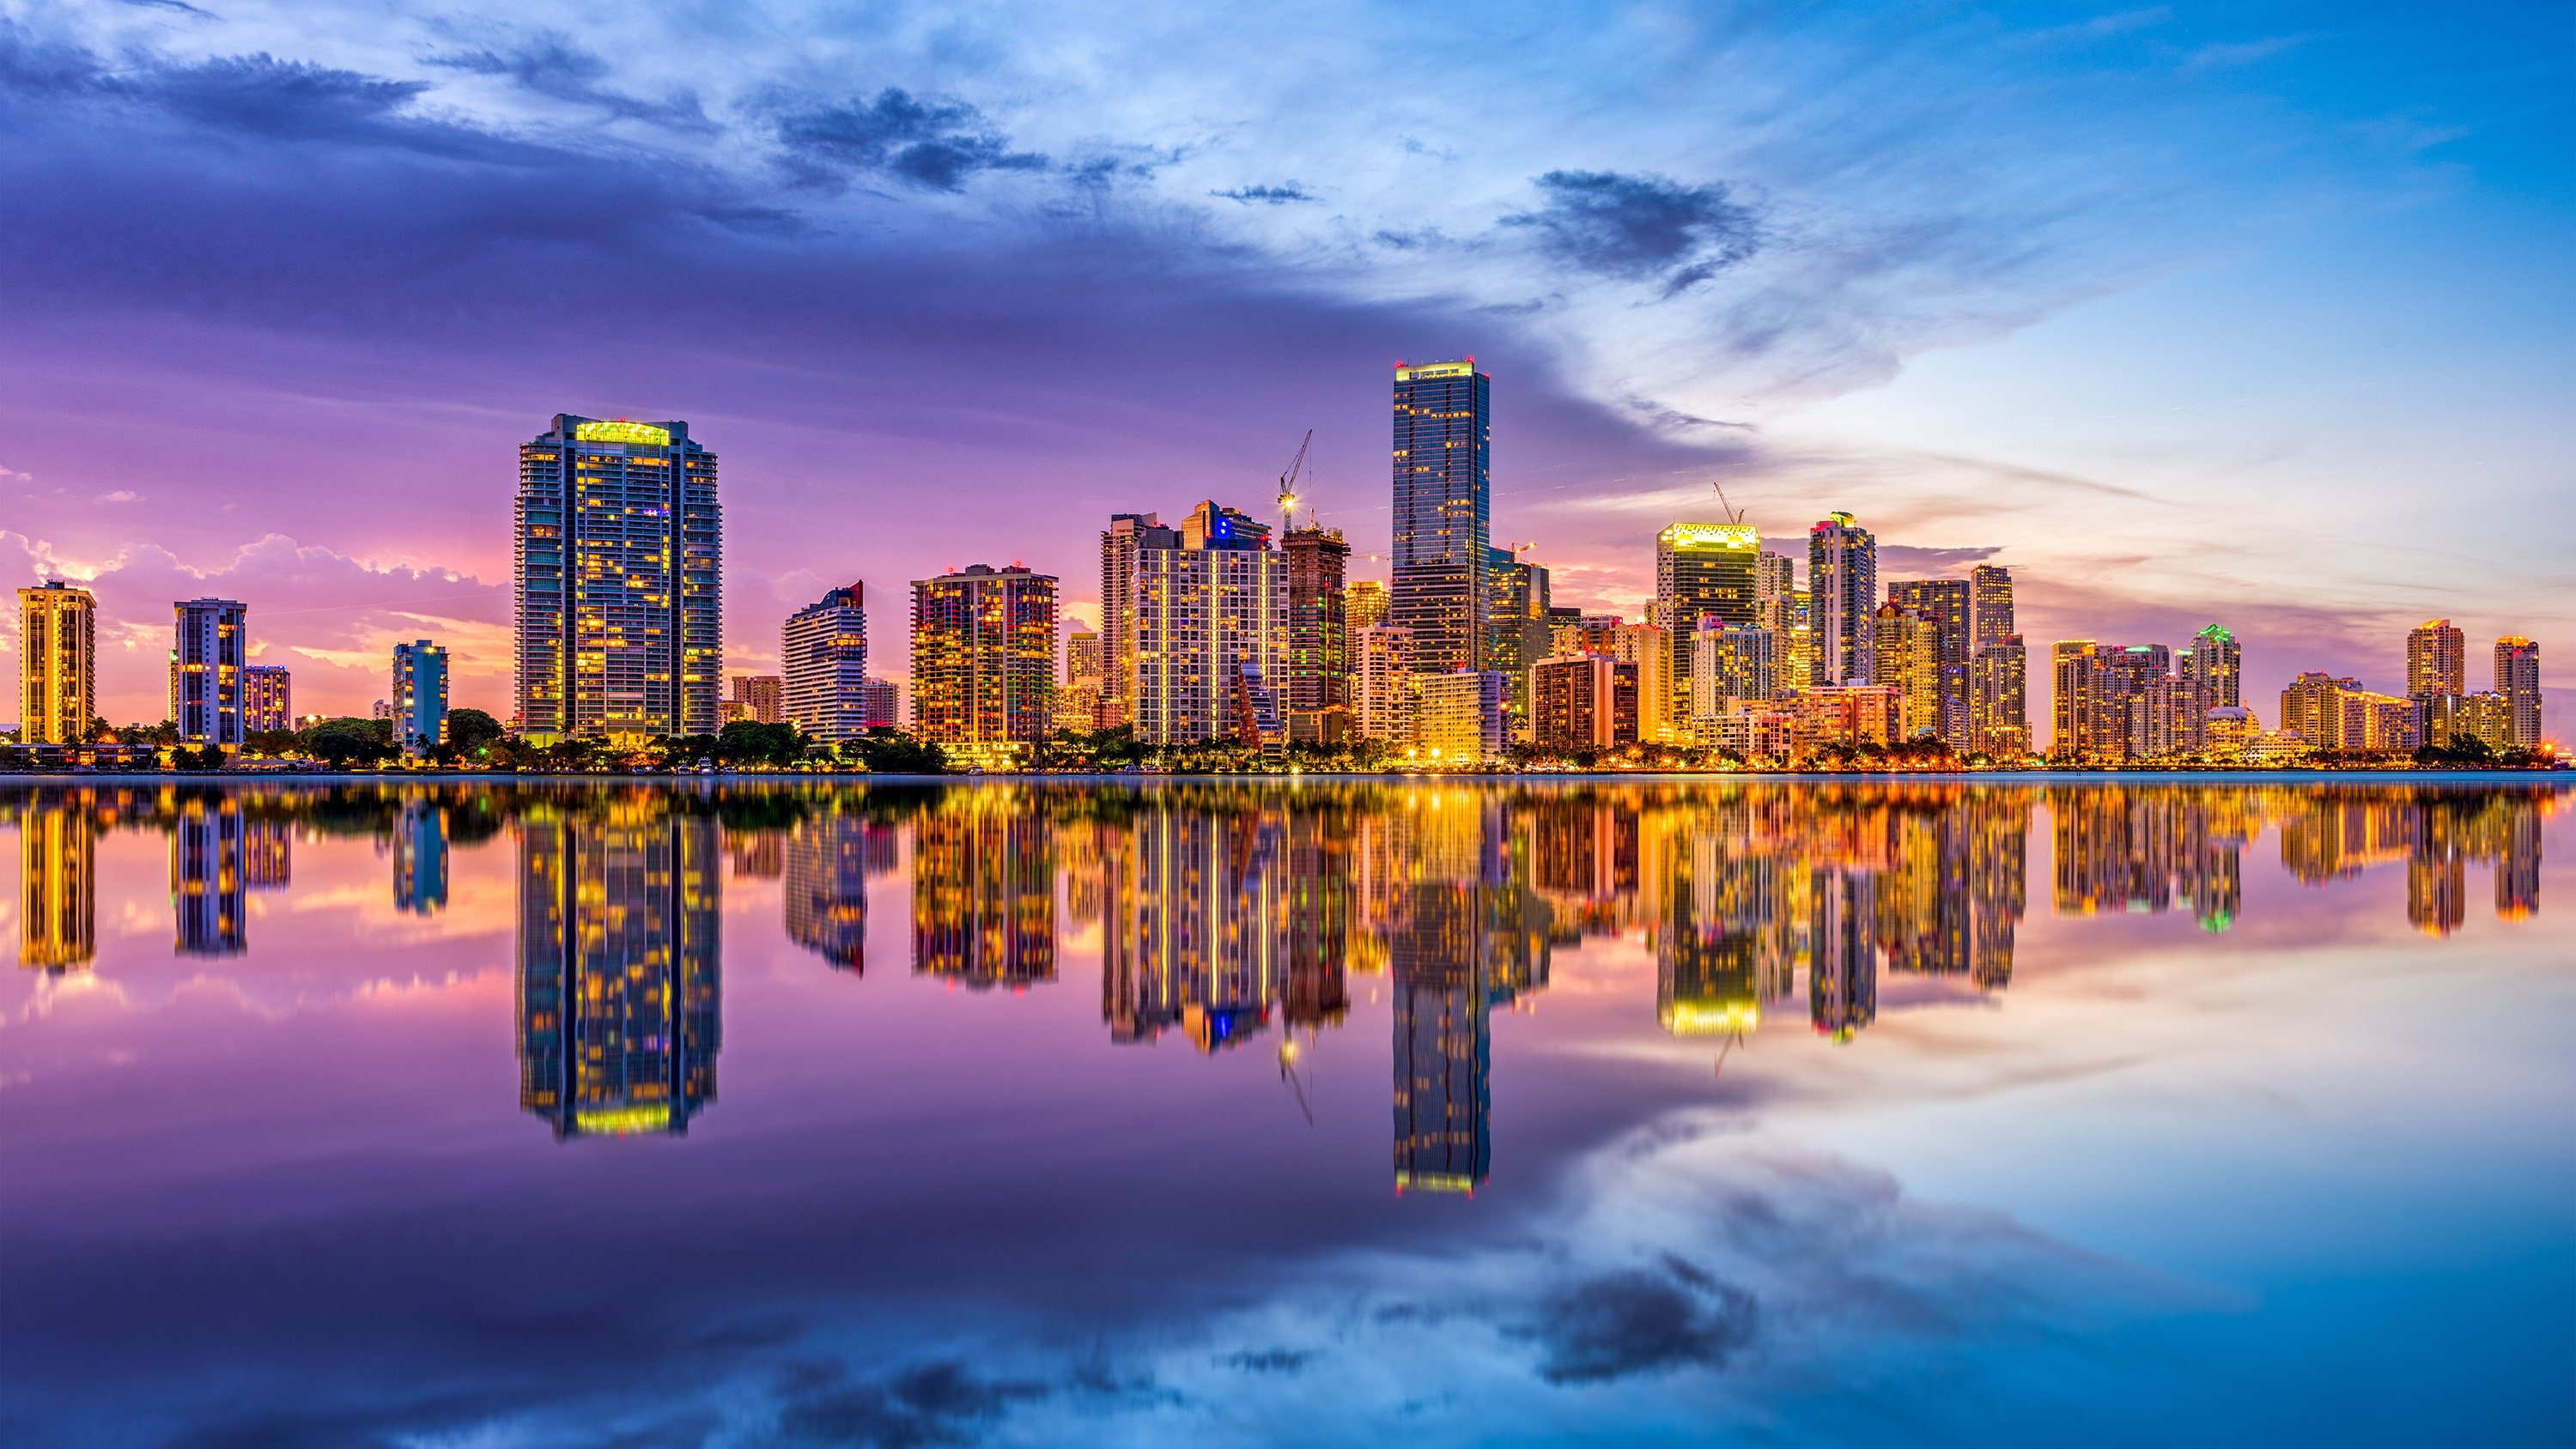
September 2025 saw significant growth in South Florida’s ultra-luxury real estate sector, particularly in new construction condominiums and high-end homes.
Each of these data points showcases a strengthening ultra-luxury real estate market in South Florida. Record-setting sales, a wave of wealthy newcomers, high levels of cash and foreign investment, and steadily rising values all contribute to a climate of confidence. Investors can take heart that the South Florida luxury new construction market is not only robust today, but positioned for continued growth moving forward.
Wealth migration and tax efficiency. Florida’s well-established advantages—no state income tax, a business-friendly environment, first-class airports, and year-round outdoor lifestyle—continue to draw high-earning households. This migration has materially changed the buyer mix across Miami, Miami Beach, and Brickell, and it has expanded northward into Fort Lauderdale, Boca Raton, Palm Beach, and Bay Harbor Islands, supporting deeper demand across both vertical and single-family product.
Liquidity from cash buyers. With roughly two out of five Miami transactions closing in cash, sellers of best-in-class properties maintain leverage. Buyers who can document funds early and close quickly often beat financed offers, particularly on rare waterfront or penthouse inventory in areas like Sunny Isles Beach and Miami Beach.
International confidence and diversification. A nearly even split of domestic and international demand in new construction helps stabilize absorption through seasonal cycles. For global buyers, South Florida remains a compelling portfolio diversification play with lifestyle utility—ocean access, yachting, fine dining, art and culture—alongside a strong rental backdrop in select buildings.
Relative global value. Despite a decade of appreciation, Miami’s prime values remain meaningfully below those of Monaco, London, and New York. That delta continues to funnel capital into South Florida’s luxury condominiums and bayfront estates.
Miami Beach. Trophy oceanfront and boutique, wellness-forward buildings see outsize demand thanks to direct sand access, privacy, and concierge service. For an overview of current opportunities and insights, explore our guide to Miami Beach.
Brickell. Brickell’s live-work-play core remains a magnet for finance and tech relocations. Pedestrian convenience, skyline views, and branded-service residences lead pricing; inventory in the most desirable lines can move within days. Review our latest market notes for Brickell.
Sunny Isles Beach. A long-established corridor for branded towers and true beachfront living, Sunny Isles Beach continues to attract international families prioritizing resort amenities, schools, and beach access.
Fort Lauderdale. Along Las Olas and the Intracoastal, marina-oriented condominiums and townhomes appeal to yacht owners seeking dockage and quicker airport access. See our neighborhood coverage for Fort Lauderdale.
Palm Beach & Boca Raton. Elegance meets convenience—country clubs, intimate downtowns, and direct Intracoastal frontage keep inventory tight. For a broader view, reference our snapshot of Palm Beach and recent activity in Boca Raton.
Bay Harbor Islands. Low-scale, waterfront living with proximity to Bal Harbour Shops and top-ranked schools remains undersupplied; boutique buildings with boat slips and rooftop amenities see swift absorption.
Product themes. New construction condominiums with wellness suites, private clubs, and deep amenity stacks are commanding premiums; at the same time, turnkey waterfront single-family with new docks, elevation, and generator packages are trading rapidly. Buyers are prioritizing views (ocean, bay, or skyline), private marina access, pet-friendly policies, and family-friendly floor plans with dens and club rooms.
For buyers
For sellers
Risk radar and offsets. Rising insurance premiums and HOA assessments are top-of-mind. Mitigate by favoring buildings with robust reserves, recent engineering reports, completed 40/50-year recertifications, updated life-safety systems, and proactive capital planning; in single-family, prioritize new roofs, impact glazing, and elevation.
Why the momentum is durable. South Florida marries lifestyle and capital efficiency. The mix of finance, tech, and creative-class relocations, plus international diversification and relative global value, points to continued depth of demand across Miami, Brickell, Fort Lauderdale, Boca Raton, Palm Beach, Miami Beach, Sunny Isles Beach, and Bay Harbor Islands.
As always, our private-client advisory team can provide line-by-line, stack-by-stack analysis and off-market access across the most coveted addresses. For bespoke guidance, connect via Million Luxury.
What price points define “luxury” and “ultra-luxury” in South Florida right now? In 2025, “luxury” commonly refers to the top 10% of closed sales within a submarket, which in Miami often begins around the $1.5–$2 million threshold for condominiums and higher for waterfront homes. “Ultra-luxury” typically starts at $10 million. Local cutoffs vary by area and product.
How should I compare pre‑construction vs. move‑in‑ready? Pre‑construction offers first‑access to best lines, modern specs, and a phased deposit schedule, with potential value creation through the cycle. Move‑in‑ready delivers immediate use and certainty on views and finishes. The right path depends on timing, liquidity, and whether you prize selection or immediacy.
What does a 4.2‑month absorption rate mean for negotiations? A balanced market is often cited around 6 months of supply; at 4.2 months, conditions favor sellers in the best buildings and locations. Buyers still find leverage in buildings or submarkets with multiple similar options or longer days on market.
Are cash offers still critical? Yes—especially for coveted oceanfront or trophy properties. Cash can shorten timelines and reduce risk for sellers. If financing, aim for strong pre‑approval, limited contingencies, and flexible closing terms.
Which neighborhoods are best for families seeking schools and amenities? Bay Harbor Islands, Boca Raton, and parts of Palm Beach offer excellent proximity to top schools, parks, and family‑friendly amenities. In Miami, select enclaves of Miami Beach and Sunny Isles Beach also align well for year‑round living.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversation