A buyer-focused guide to reading assessment schedules, negotiating seller contributions, and structuring escrow holdbacks in a Miami Beach condominium resale, without confusing contractual protections with property-wide policies.
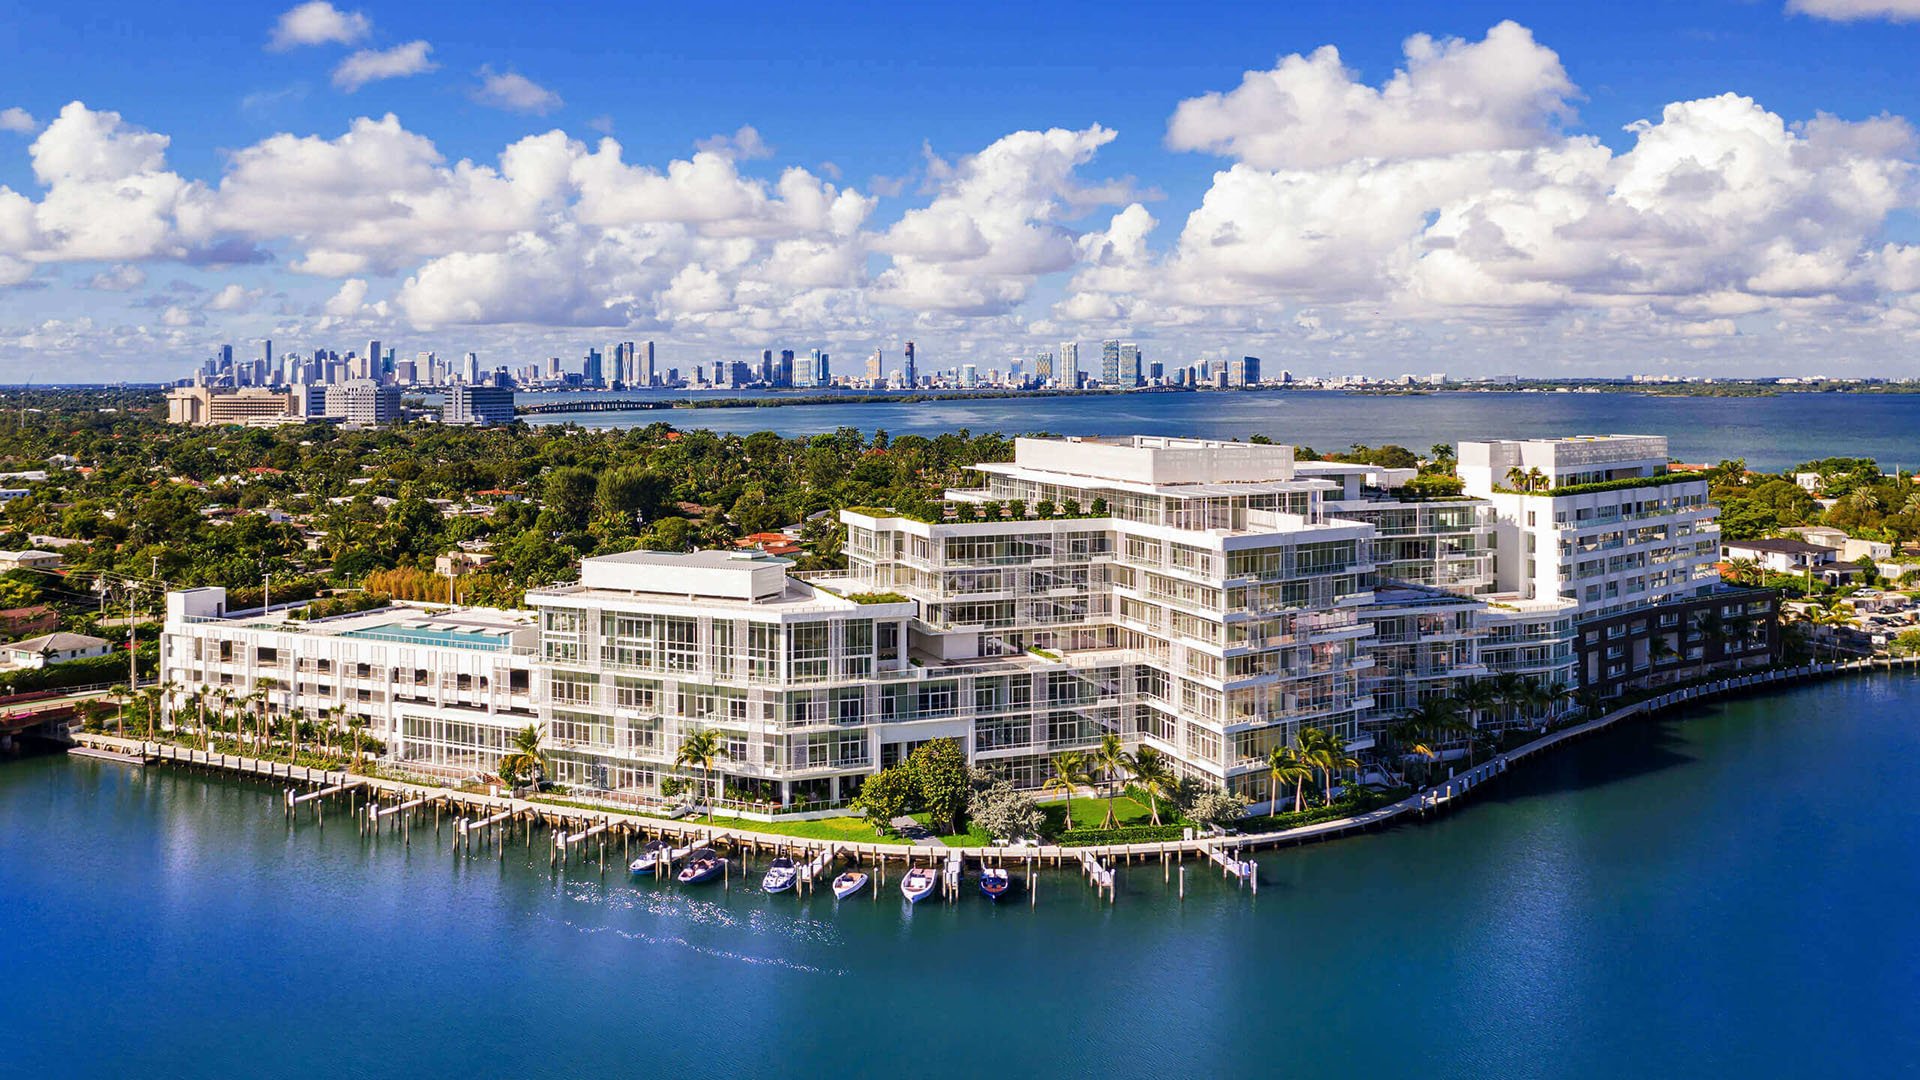
For a buyer considering The Ritz-Carlton Residences® Miami Beach, the financial terms of the purchase deserve the same scrutiny as the residence itself. A compelling presentation cannot answer every question about association obligations, installment dates, or the allocation of costs between seller and buyer. Those answers belong in condominium records and transaction documents.
This discussion does not suggest that the property currently has a special assessment, a seller-credit program, or a standardized escrow arrangement. These are due-diligence and negotiation considerations, not representations about an existing charge or property policy.
The central distinction is straightforward: an association’s payment calendar and the parties’ agreement about who bears the cost are separate matters. Establishing both before closing is more useful than securing a concession whose purpose remains ambiguous.
Begin by distinguishing a formally approved assessment from an expense merely discussed by the board. An approved obligation requires a review of the amount and payment schedule. A discussion warrants further investigation into what has been proposed and whether a decision remains outstanding. Neither should be described as the other.
Review the condominium estoppel certificate for regular and special assessment amounts shown as currently due or scheduled to become due. Reconcile that information with the assessment documentation, governing documents, and financial information supplied for the resale rather than treating any single record as the complete picture.
Board agendas and minutes deserve a separate review for assessment discussions and decisions. Ask counsel to confirm which disclosure provisions apply under the condominium rider used in the transaction, including any required review period, rather than assume every contract uses identical language.
The estoppel review should also extend beyond the balance due to any disclosed violations or unresolved issues. A buyer should ask for those matters to be identified and addressed-not merely for confirmation that regular payments are current.
When an approved assessment exists, ask the transaction team to reconcile the unit’s obligation across the estoppel, assessment documentation, and contract. Establish the amount remaining unpaid, the installment dates, and the party responsible for each payment. Resolve any inconsistency before approving the closing figures.
Do not infer responsibility solely from whether an installment falls before or after closing. The purchase contract should expressly allocate the assessment. One buyer-protection option is to require the seller to pay approved but unpaid assessments at closing, with the payment reflected in the transaction documents.
The parties may instead negotiate a different allocation. State it precisely: which obligation is covered, what the seller contributes, and what the buyer accepts. A general promise to “take care of assessments” leaves too much room for disagreement.
This discipline is equally relevant when considering another Miami Beach resale, including a residence at Setai Residences Miami Beach. Compare each unit’s documented obligations rather than assume neighboring properties share assessment practices.
A seller contribution can take different forms, and its label should never substitute for its mechanics. Direct payment of an approved unpaid assessment addresses the association obligation itself. A negotiated seller credit requires the contract and closing instructions to specify how the contribution will be applied and which party remains responsible for payment.
A purchase-price reduction works differently. It can reflect an estimated assessment cost in the acquisition price, but it does not itself pay the association’s bill. The buyer should consider both the revised price and the cash needed when any remaining obligation becomes due.
The useful negotiation question is not simply “How much is the concession?” It is “What obligation does this concession resolve?” If the answer is only that the price is lower, the payment schedule still needs to be addressed separately.
Have counsel and the closing team confirm that the agreed structure is accurately reflected throughout the transaction documents. A credit, a discount, and a payoff are not interchangeable protections.
An escrow holdback is a potential negotiation option when an assessment is pending but its final amount is not yet known. Rather than rely entirely on an estimate embedded in the purchase price, the parties can negotiate retained funds and conditions governing their use.
The structure must be transaction-specific. Counsel should address who funds the holdback, how much is retained, who holds it, and which assessment-related costs qualify for payment. The agreement should also specify the evidence required to authorize disbursement, release conditions, deadlines, and procedures for resolving disagreements.
Two questions deserve particular attention: what happens if the obligation exceeds the retained funds, and what happens if no qualifying assessment is ultimately approved? Address both explicitly rather than assume the escrow will resolve every possibility.
Consider release timing alongside the association’s decision timeline. Ask counsel how the arrangement would function if a decision remains outstanding at the proposed release date. A holdback offers useful protection only to the extent that its written terms address the uncertainty the parties intend it to cover.
Seller credits, price adjustments, and escrow holdbacks are options to discuss for an individual transaction, not evidence of a building-wide practice. A comparison with another South Florida residence should begin with that purchase’s records rather than an assumption that the same arrangement is available.
For a buyer also considering The Ritz-Carlton Residences® Sunny Isles, the same distinction matters: a shared brand name is no basis for assuming shared assessment arrangements. Each purchase requires its own records and contractual allocation.
Contractual disclosure provisions should not be confused with statutory duties. If an assessment was not disclosed, ask counsel to determine how the actual contract, condominium rider, and applicable law affect responsibility and available remedies. Do not assume the omission automatically resolves who pays.
Before closing, the buyer should be able to distinguish what is approved, what remains under discussion, what is payable, and who has agreed to pay it. Any credit or holdback should connect directly to that understanding.
The objective is not a larger concession at any cost. It is a purchase whose price, future payment obligations, and protections can be understood together, with fewer unresolved questions carried into ownership.
For a discreet conversation about your South Florida property search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. It describes due-diligence and negotiation options, not an existing assessment or a property-wide credit or escrow policy.
Review the regular and special assessment amounts shown as due or scheduled to become due, along with any disclosed violations. Reconcile the information with the assessment documentation and other resale records.
They can help distinguish assessment discussions from formal decisions. Counsel should confirm the disclosure provisions and any review period required by the transaction’s condominium rider.
No. Buyers should distinguish board discussions from formal approval because the status affects both the documents to review and the negotiation structure.
Responsibility should not be inferred solely from the installment date. The purchase contract should expressly allocate the assessment between seller and buyer.
Yes. Requiring the seller to pay approved but unpaid assessments at closing is one negotiation option, not an automatic entitlement.
No. It can reflect an estimated assessment cost in the purchase price, but the association obligation still needs to be paid by the responsible party.
It may be useful when an assessment is pending but its final amount is not yet known. The parties must negotiate transaction-specific funding and release terms.
Counsel should address funding, permitted uses, payment evidence, release conditions, deadlines, and dispute procedures. The agreement should also address any shortfall or unused balance.
Ask counsel to review the actual contract, condominium rider, and applicable law to determine responsibility and available remedies. Do not assume the omission automatically makes either party responsible.