A discreet acquisition framework for Ocean House Surfside, separating verified developer disclosures from recommended family-office approvals, funding documentation and wire controls, with the federal reporting rule’s vacatur kept in view.
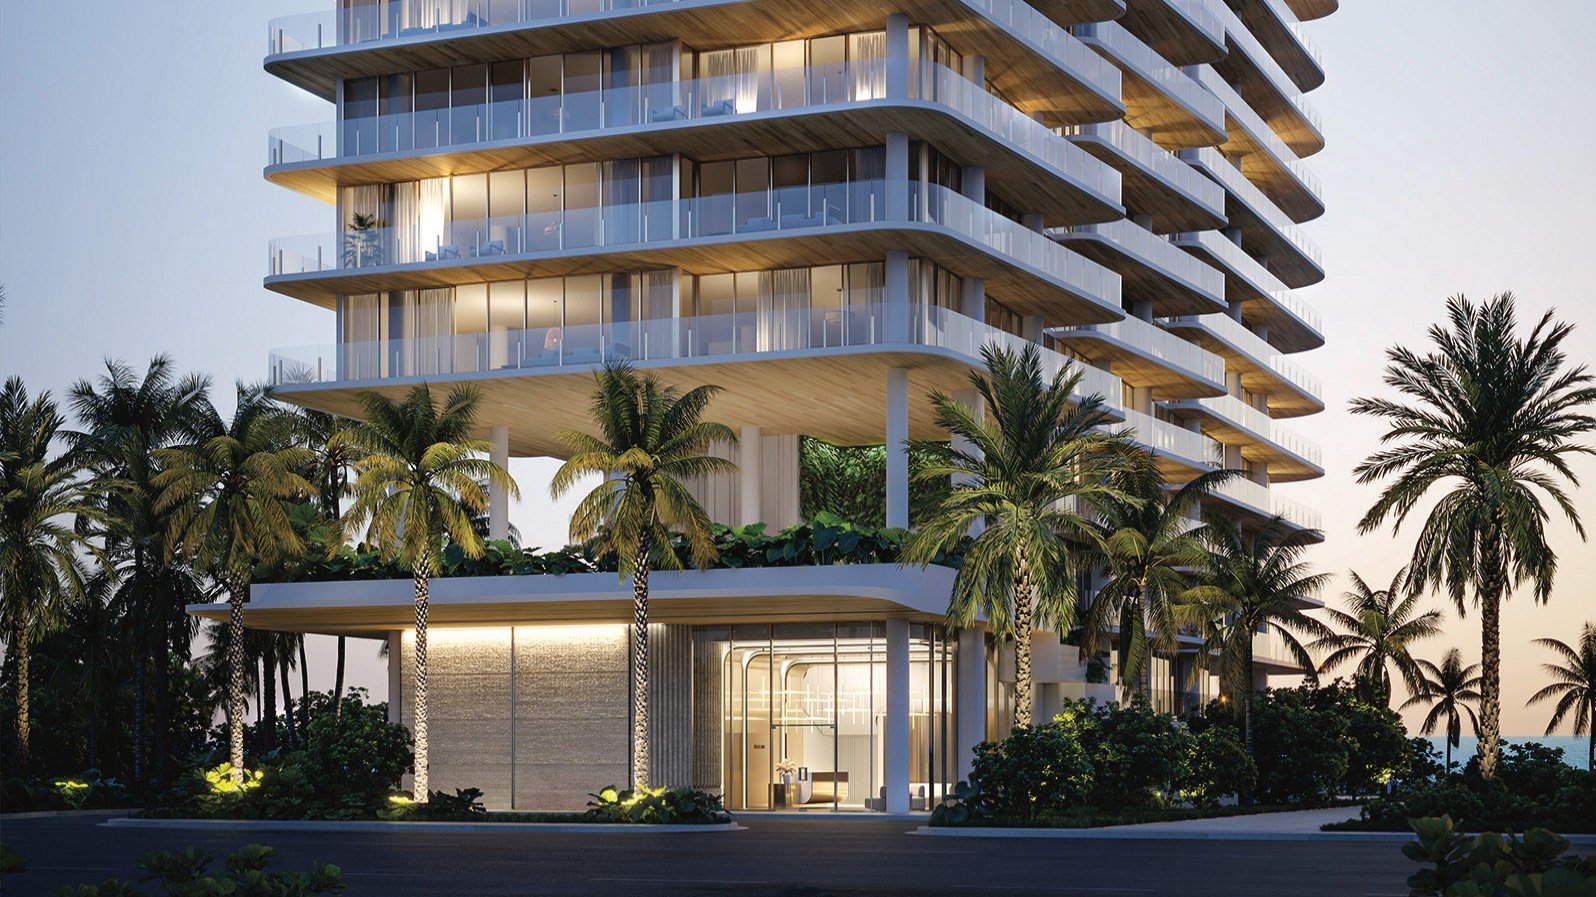
For a family office considering Ocean House Surfside, acquisition discipline begins with a distinction: the residence under consideration and the legal party responsible for its development are not interchangeable. A compelling presentation may establish interest. It should not replace identifying the developer, documenting purchase authority or controlling the movement of capital.
Ocean House Surfside’s developer is MTP Oceanside LLC, a Florida limited liability company. Multiplan serves a licensed brand and marketing role, not that of the condominium developer. Development and unit-sale representations belong to the developer. Buyers are directed to look solely to that entity, rather than Multiplan or its affiliates, for project-related matters.
That distinction should anchor the acquisition file. Family-office approvals, source-of-funds records and payment safeguards are separate layers of diligence. The recommendations below are buyer-side practices to discuss with advisers, not established Ocean House requirements.
The project’s marketing materials expressly do not constitute an offer to sell or a solicitation to buy a condominium unit. The practical implication: do not treat a presentation as the operative purchase agreement. Ask counsel to reconcile material commercial expectations with the transaction documents before authorizing execution or a deposit.
A useful review would identify the developer named in the agreement, the purchaser’s exact legal identity, the party receiving funds and any provisions governing deposits. Resolve these questions in the actual documents rather than drawing assumptions from branding.
For families considering The Delmore Surfside alongside Ocean House, maintain a separate counterparty and contract review for each candidate. A shared location does not establish shared legal obligations, deposit procedures or approval standards. The same principle applies throughout a Surfside search: evaluate each transaction on its own documents.
A recommended family-office approval file should answer three questions: who will own the residence, who may bind that purchaser and who may release its funds? Those roles may overlap. The acquisition team should not assume, however, that authority to sign a contract also establishes authority to instruct a bank.
Before execution, consider a written decision record covering the proposed purchasing entity or trust, the approved financial commitment and the individuals authorized to act. Counsel should determine which resolutions, consents or other authority documents suit the chosen structure. No specific approval format or monetary threshold is established here as an Ocean House requirement.
Investment review should also distinguish approval to pursue a property from approval to sign and approval to transmit money. A staged process can preserve discretion while giving advisers clear decision points. For a family comparing Rivage Bal Harbour with a Surfside acquisition, this structure offers a consistent buyer-side framework without implying that either project uses the same internal procedures.
Treat a source-of-funds file as an organized explanation of the proposed purchase funding, not a certificate that the transaction has passed every legal or compliance test. Its recommended purpose is to help the family office and its advisers understand where the money will come from and how it will reach the designated recipient.
Consider recording the funding account’s ownership, the relationship between that account holder and the purchaser, and the anticipated movement of funds. Where relevant, advisers may request supporting records for an asset sale, distribution or other funding event. These are illustrative buyer-side steps, not verified project document requests or universal requirements.
Ask the settlement team which documents it actually needs, through what secure channel and by what deadline. Limit access to appropriate participants rather than circulating sensitive records broadly. Do not infer an Ocean House source-of-funds threshold, escrow-bank protocol or acceptance standard. Confirm those particulars directly for the transaction.
The federal Residential Real Estate Reporting Rule was designed to cover certain non-financed residential-property transfers to legal entities or trusts. A family-office acquisition vehicle could therefore fall within its intended scope, depending on the transaction. Transfers to natural persons generally fall outside that entity-and-trust scope.
The rule assigned reporting responsibility to certain professionals involved in closings or settlements, rather than automatically making the purchaser the reporting person. It also did not itself impose an anti-money-laundering program obligation on those professionals. Neither reporting nor the absence of a reporting requirement should be treated as proof of the provenance of purchase funds.
The original reporting start date was March 1, 2026. The U.S. District Court for the Eastern District of Texas subsequently vacated the rule on March 19, 2026, and the decision was appealed. While the vacatur order remains in force, reporting persons need not file Real Estate Reports and are not liable for failing to file them.
The practical instruction remains conditional: have counsel or the settlement agent confirm the applicable legal position before closing. The original start date alone does not resolve the obligation, and the appeal should not be treated as proof that reporting has resumed.
For a waterfront acquisition, control over the final payment instruction deserves the same attention as the purchase decision. Recommended safeguards include independent verification of recipient details and a second authorization before release. Neither is presented here as a confirmed Ocean House procedure.
Consider establishing a trusted contact route before receiving wire instructions. Verify the beneficiary and account details through that independently established route, rather than relying exclusively on contact information supplied in the message carrying the instructions. A revised instruction should trigger fresh verification, not automatic acceptance because earlier correspondence appeared familiar.
A family office may also require one person to prepare the payment and another authorized person to approve it after reviewing the verification record. Confirm with the bank how that arrangement can be implemented. These steps support a controlled release process; they do not guarantee that fraud cannot occur.
Before any authorized payment, consider assembling a concise closing-readiness record: reviewed transaction documents, confirmed signing authority, an understood funding path, the settlement team’s current regulatory position and independently verified payment instructions. Unresolved discrepancies should return to counsel or the relevant adviser before release.
The central lesson for buyers is that brand familiarity, purchasing authority, funding documentation and payment verification answer different questions. At Ocean House, begin with the identified developer and ground each subsequent decision in the transaction’s own documents. Precision protects the family’s intentions without claiming assurances the materials do not provide.
Explore South Florida residences with a considered perspective at MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe developer is MTP Oceanside LLC, a Florida limited liability company.
No. Multiplan has a licensed brand and marketing role, while development and unit-sale representations belong to the developer.
No. The materials expressly do not constitute an offer to sell or a solicitation to buy a condominium unit.
No. They are buyer-side practices to discuss with counsel, not established Ocean House approval procedures or thresholds.
It should identify the purchaser, the individuals authorized to bind it and the individuals authorized to release funds. Counsel should determine the appropriate authority documents.
It helps advisers understand the proposed origin and movement of purchase funds. It does not certify that every legal or compliance requirement has been satisfied.
It was designed to cover certain non-financed residential-property transfers to legal entities or trusts. Transfers to natural persons generally fall outside that scope.
A federal district court vacated the rule on March 19, 2026, and the decision was appealed. While the vacatur remains in force, reporting persons need not file Real Estate Reports and are not liable for failing to file them.
No. The rule does not itself impose that program obligation on professionals involved in real-estate closings and settlements.
Consider independently verifying recipient details through a previously established contact route and requiring a second payment authorization. These are recommended buyer controls, not confirmed Ocean House requirements or guarantees against fraud.