For buyers leaving Jackson Hole, a Surfside residence must do more than establish a Florida address. Permanent-home evidence, January 1 eligibility, separate portability filings, and a reassessed property-tax budget each require deliberate planning.
Leaving Jackson Hole for Surfside is not simply a change of scenery. For a buyer establishing Florida domicile, the residence must become the predominant and principal home-not merely another property in a multi-state portfolio. Ownership begins that transition; it does not prove the transition is complete.
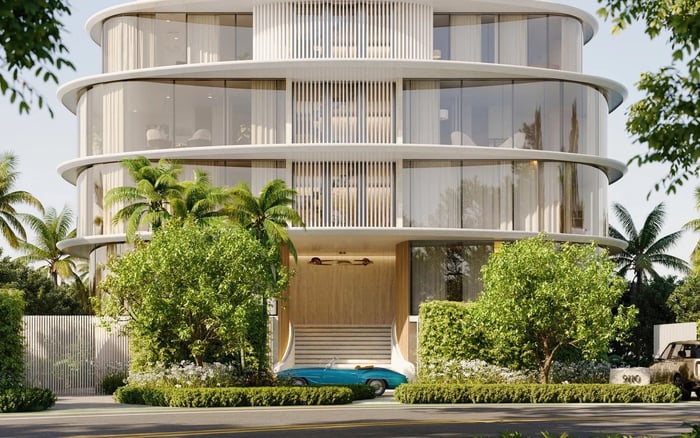
The purchase therefore calls for two parallel evaluations: whether the home suits daily life and whether the acquisition calendar supports the intended homestead year. A residence under consideration at Arte Surfside warrants the same scrutiny. The question is not just whether the buyer wants to own it, but whether it can genuinely serve as the permanent home on the required timetable.
Four matters should remain distinct throughout the process: domicile evidence, homestead eligibility, Save Our Homes portability, and reassessment after purchase. A strong position on one does not automatically resolve the others.
Keeping a Jackson Hole home does not automatically prevent Florida domicile. For someone maintaining residences in multiple states, however, the Florida property must be established as the predominant and principal home. Retaining the mountain residence is different from continuing to treat it as the household's permanent base.
Florida permits a sworn declaration of domicile to be filed with the circuit court clerk in the county of residence. The declaration documents intent; it should accompany the move, not substitute for it.
For homestead purposes, relevant evidence may include a Florida driver's license, vehicle and voter registrations, employment information, bank statements, and other permanent-residency records. Proof of previous residency outside Florida-and the date it ended-also matters.
Assemble a coherent transition file: record when Wyoming residency ended, retain supporting documentation, and ensure the Florida records reflect the actual change. The objective is consistency among the household's stated intent, documentary record, and use of the Surfside residence.
To receive homestead for a particular tax year, the buyer must own the property and establish it as a permanent residence as of January 1. The standard application deadline is March 1 of that year. The distinction is essential: January 1 determines eligibility; March 1 is the filing deadline.
Closing before January 1 without establishing permanent residence by that date does not satisfy that year's requirements. A purchase calendar that allows ample time for paperwork but leaves the actual move until after the eligibility date misses that distinction.
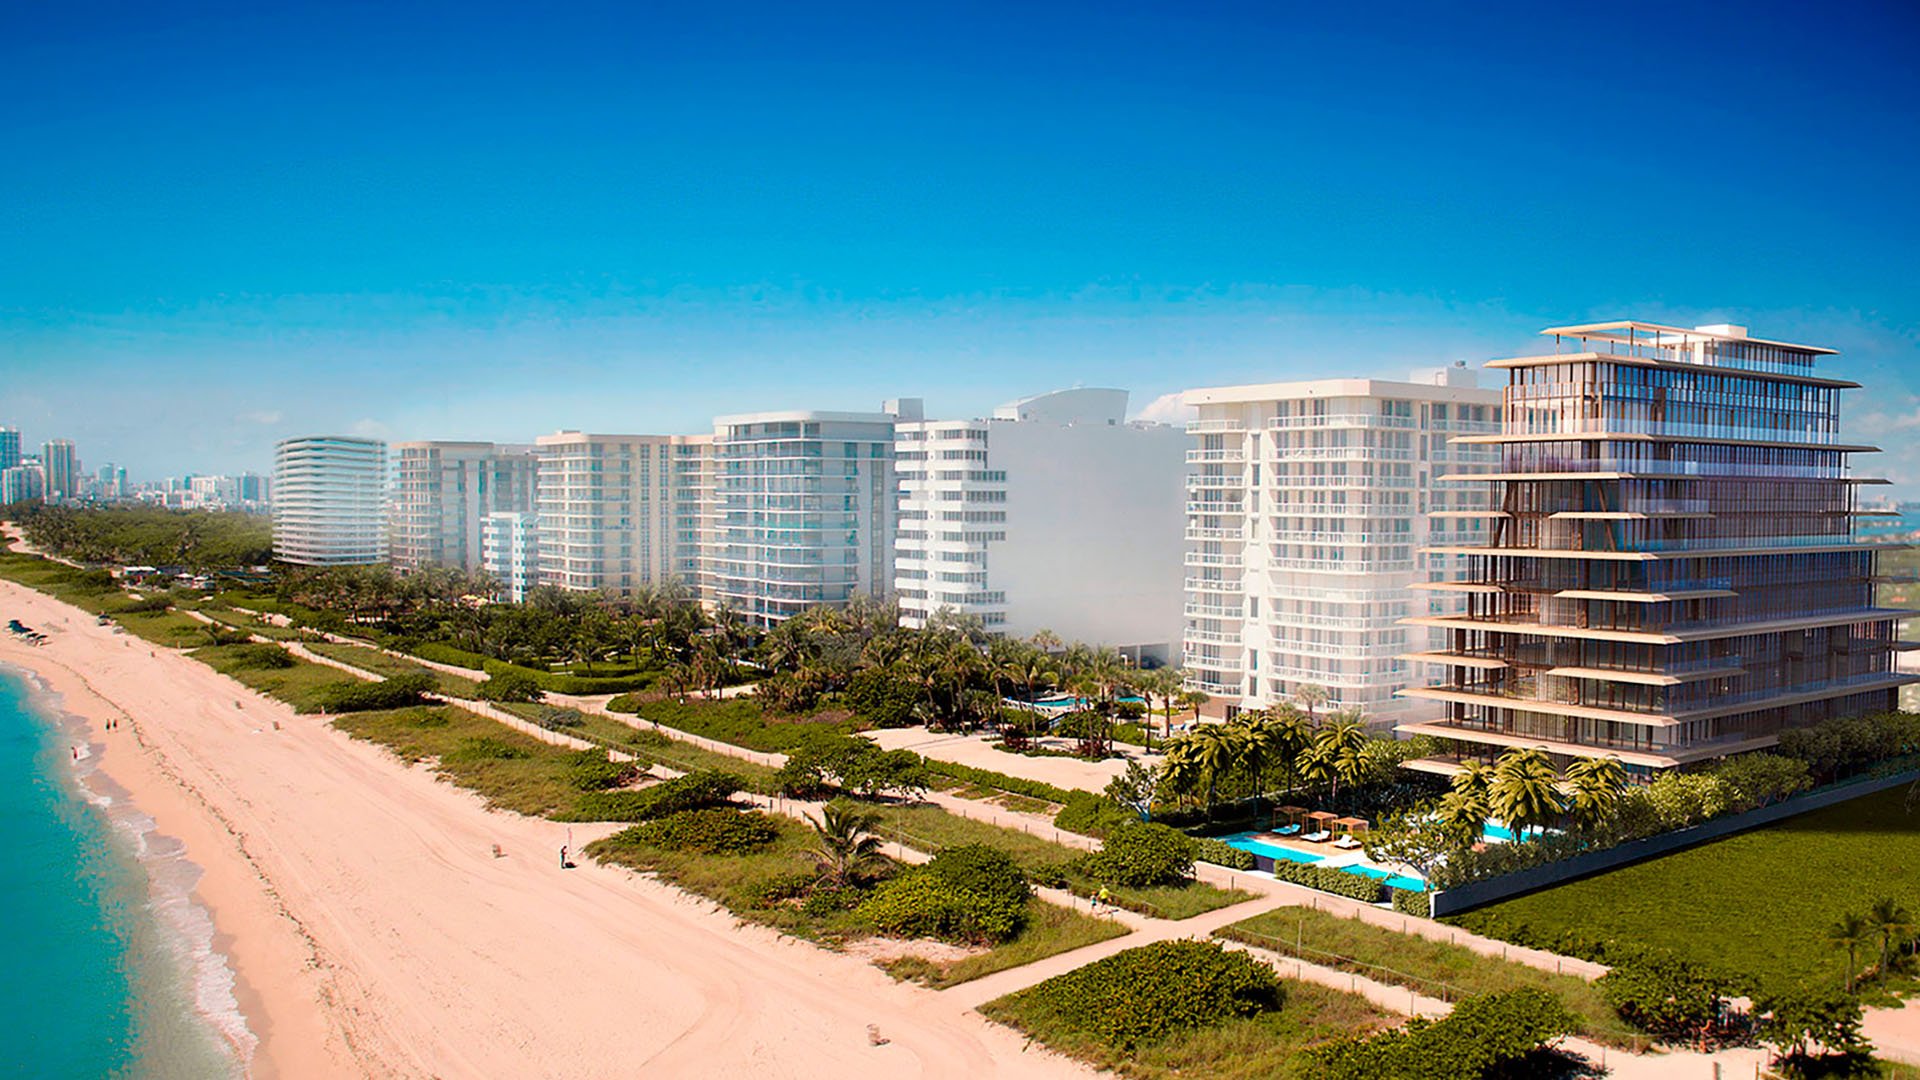
For a buyer considering Ocean House Surfside, the planning question is whether the particular residence can support ownership and permanent occupancy by the intended January 1. Neither a preferred address nor a purchase commitment replaces those conditions.
Before choosing a target homestead year, align the anticipated closing, the actual establishment of permanent residence, and the evidence supporting that transition. If those elements do not align, the tax plan should not assume they will.
Surfside homestead applications are administered by the Miami-Dade County Property Appraiser. A new owner must apply; the seller's exemption does not transfer with the residence. This distinction matters even when an existing tax record shows homestead treatment.
Treat the application as a separate closing follow-through item, not an assumed consequence of recording ownership. Prepare the residency evidence, confirm the relevant eligibility year, and work toward the standard March 1 deadline.
Households with more than one residence should pay particular attention to permanent-home evidence. The question is not merely whether Florida documents exist, but whether they support the genuine residency position being claimed. A declaration of domicile and a homestead application serve related purposes, but neither is an automatic substitute for the other.
A change of ownership generally triggers reassessment at just value on the following January 1. The seller's property-tax bill is therefore not a reliable estimate of the buyer's future bill. It may reflect an assessment history that will not carry forward to the purchaser.
Save Our Homes generally limits subsequent annual increases in a qualifying homestead's assessed value to 3% or the applicable Consumer Price Index change, whichever is lower. That protection follows the initial homestead assessment. It does not preserve the seller's capped assessment for a new buyer, nor does it guarantee that the total tax bill cannot rise more than 3%.
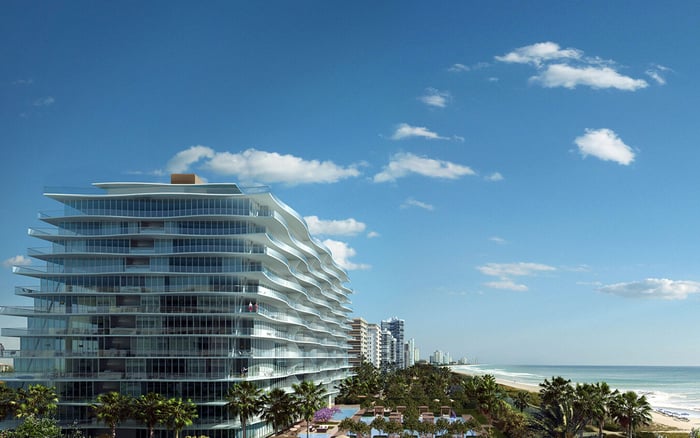
When evaluating a purchase at Fendi Château Residences Surfside, account for this distinction in the ownership budget. Request a buyer-specific tax estimate that addresses reassessment and any benefits for which the buyer may qualify, rather than carrying the historical bill into the forecast unchanged.
Establish a credible post-purchase baseline first, then consider the protection available in subsequent assessment years.
Portability transfers an eligible Save Our Homes assessment difference: the gap between just value and capped assessed value on a previous Florida homestead. It is an assessment benefit, not a transfer of the seller's tax treatment or a general relocation allowance.
Moving from Jackson Hole alone creates no Florida portability entitlement. A Wyoming benefit cannot be imported into Florida. A buyer with a qualifying previous Florida homestead, however, should examine that history separately rather than assuming the Wyoming move settles the question.
The portability window uses three tax or assessment years-not simply 36 months from a sale or moving date. The new residence must qualify by January 1 of the third year after the last homestead year on the previous Florida property. Identify that last homestead year before calculating the deadline.
Portability also requires a separate application. Submit Form DR-501T, Transfer of Homestead Assessment Difference, when applying for the new homestead exemption. For Surfside, the filing goes to Miami-Dade, with March 1 as the standard deadline. Confirm eligibility and the transferable benefit before incorporating portability into the purchase budget.
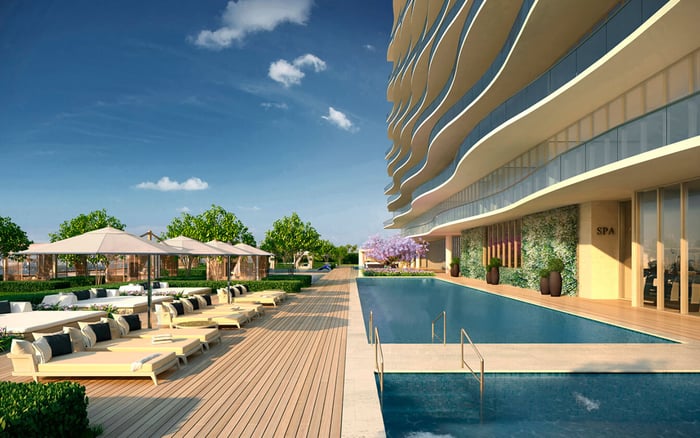
A residence at The Surf Club Four Seasons Surfside belongs within the same disciplined framework: genuine permanent-home use, a workable January 1 timeline, a new homestead application, and a realistic reassessment budget. Prior Florida homestead history adds a portability inquiry, not an automatic benefit.
Coordinate these questions with legal and tax advisers before committing to a timetable. This is a planning framework, not individualized tax advice. The strongest purchase decision pairs a home suited to everyday life with a residency record and tax calendar that support the intended transition.
For a considered approach to selecting your Surfside residence, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationOwnership alone does not establish domicile. The residence must genuinely become the owner's permanent home.
Keeping a home in Jackson Hole does not automatically prevent Florida domicile. The Florida residence must be established as the predominant and principal home.
A sworn declaration filed with the circuit court clerk in the county of residence documents intent. It does not replace actually establishing a permanent home.
Relevant evidence may include Florida license and registration records, employment information, and bank statements. Proof of prior out-of-state residency and the date it ended also matters.
The buyer must own the property and have established it as a permanent residence by January 1 for that tax year's homestead eligibility. Closing alone is insufficient.
Apply through the Miami-Dade County Property Appraiser by the standard March 1 deadline. A new owner cannot assume the seller's exemption transfers.
No. It generally limits subsequent annual growth in a qualifying homestead's assessed value to 3% or the applicable Consumer Price Index change, whichever is lower.
A change of ownership generally triggers reassessment at just value on the following January 1. The seller's capped assessment does not automatically carry over to the buyer.
No. Portability requires an eligible assessment difference from a qualifying previous Florida homestead; moving from Jackson Hole alone creates no entitlement.
The new home must qualify by January 1 of the third year after the previous Florida property's last homestead year. File Form DR-501T with the new homestead application by the standard March 1 deadline.