A financed Shorecrest purchase calls for more than an attractive mortgage quote. Align valuation assumptions, available liquidity, contract protections and written rate-lock terms with the developer’s documented closing window.
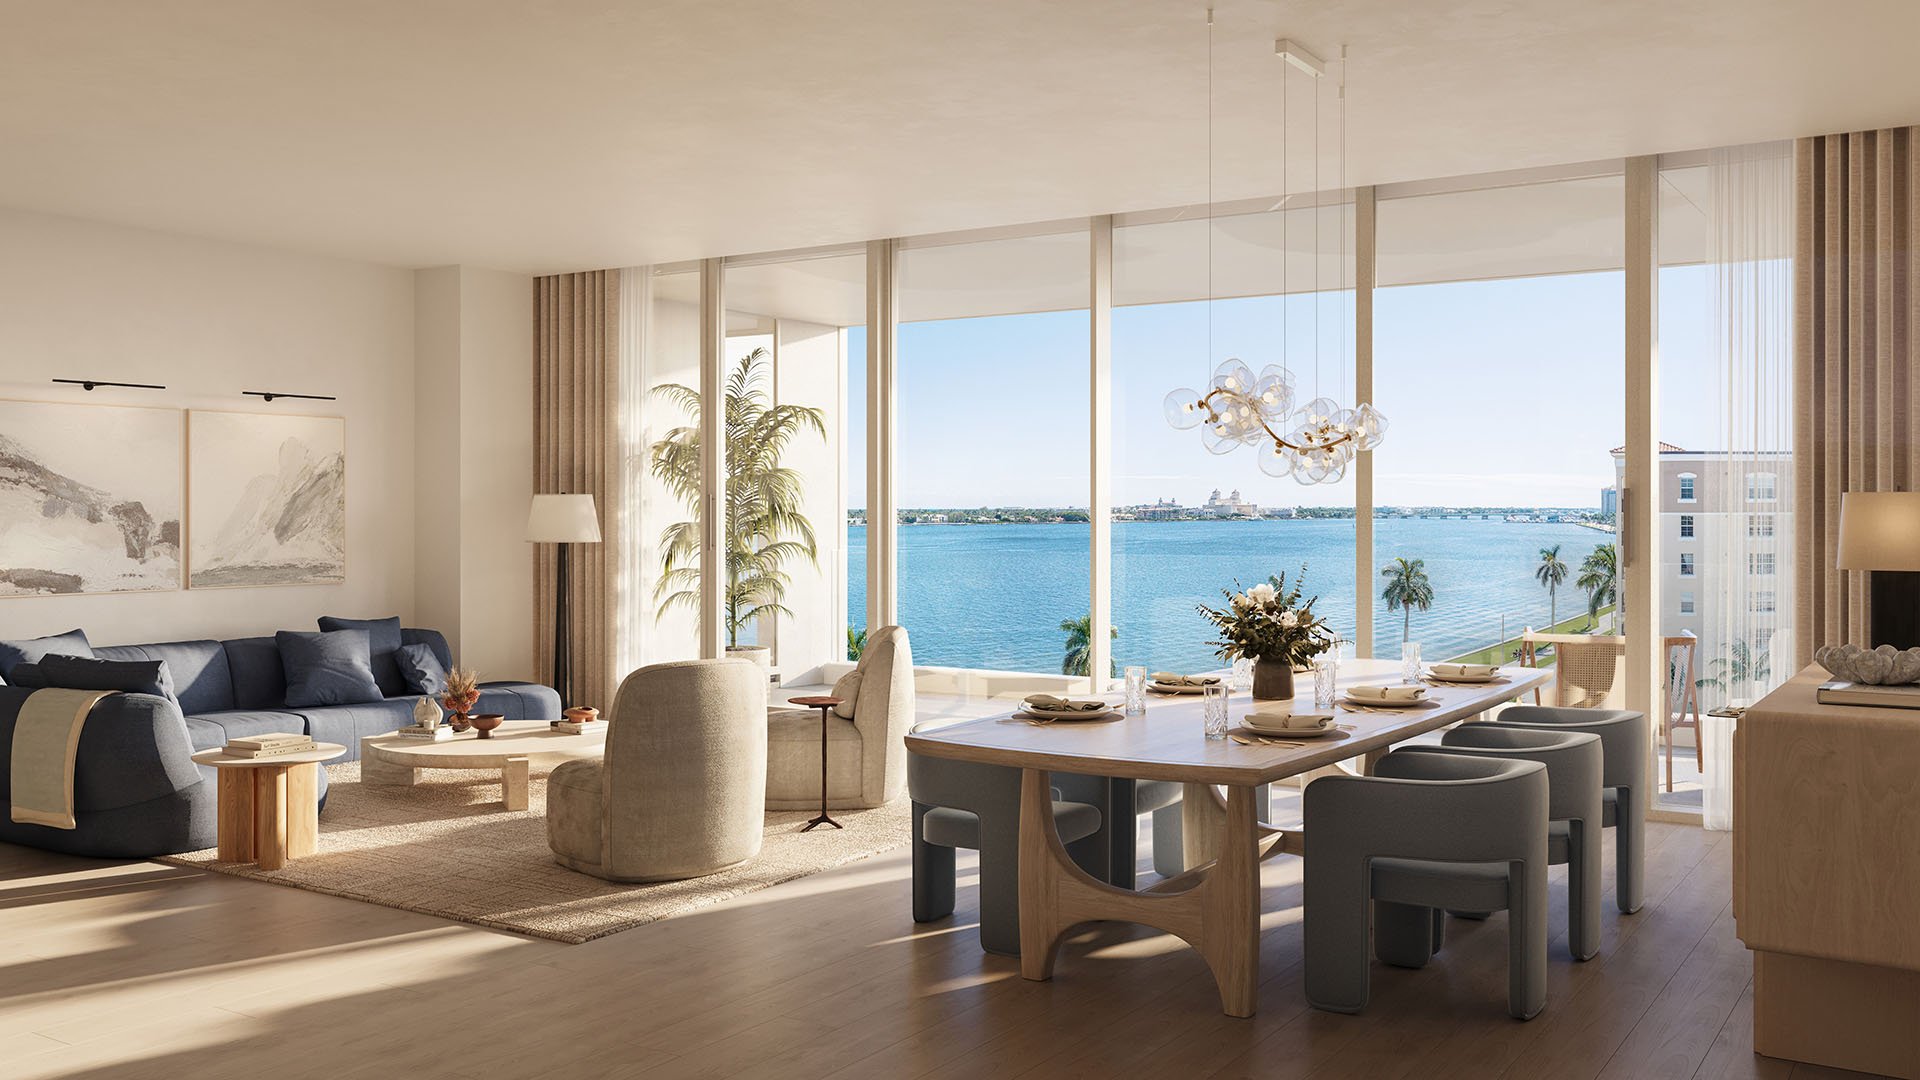
The appeal of Shorecrest Flagler Drive West Palm Beach begins with its Intracoastal setting and views toward Palm Beach. For a financed trophy purchase, however, the decisive preparation happens away from the waterfront: understanding how much the lender will advance, how much cash must remain available, and how long the quoted financing terms will hold.
Two variables deserve particular attention. An appraisal below the contract price may alter available loan proceeds. A rate lock that expires before closing may require a decision on extensions or replacement terms. Neither outcome should be assumed at Shorecrest, but both warrant attention before a purchase commitment.
The objective is not to predict an appraisal or a future interest rate. It is to preserve the ability to close on acceptable terms without an unplanned liquidity decision under deadline.
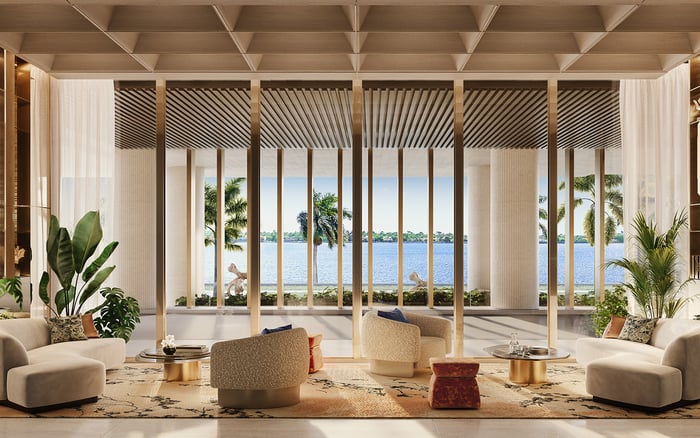
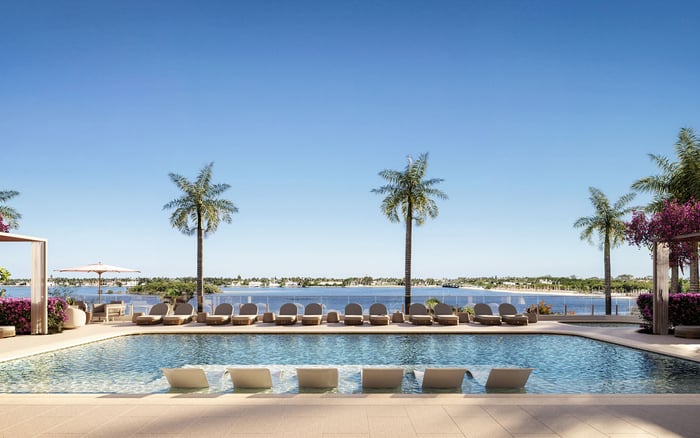
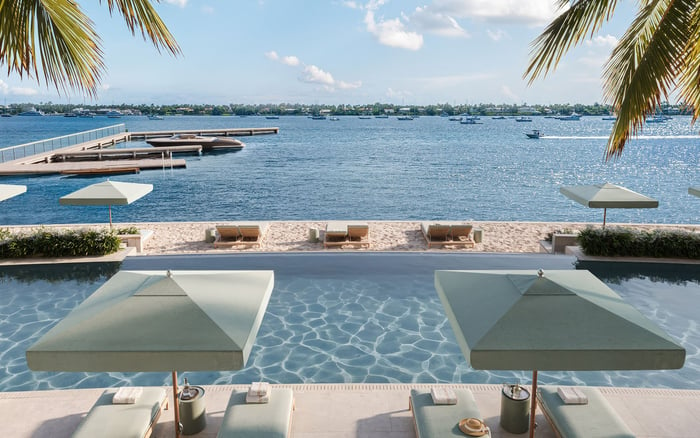
Shorecrest is a Related Ross condominium project on North Flagler Drive in West Palm Beach. Its program comprises 100 residences and approximately 323,000 square feet, with two- to four-bedroom layouts and a penthouse collection. As of February 2026, the project plan called for a 28-story tower at 1865 North Flagler Drive.
Version control matters. The project was redesigned from 199 planned residences to 100. Earlier materials used a different address and lower pricing. The revised project’s pricing range of approximately $2.7 million to $7 million should be treated as historical context, not a current availability quote.
Before submitting a financing package, reconcile the residence description, floor plan, purchase price and contract exhibits with the latest developer documents. A lender should evaluate the property being purchased, not an earlier iteration of the development. Obtain current residence-specific pricing directly rather than building a financing plan around the historical range.
An appraisal gap is the difference between the agreed purchase price and a lower appraised value. Its practical consequence depends on the lender’s underwriting rules and proposed loan structure. The question is not simply whether a valuation could fall below contract, but how that result would change the buyer’s funding obligation.
Ask the lender for a written comparison of two scenarios: an appraisal supporting the purchase price, and a below-contract valuation using an assumption agreed with the lender. Each should show anticipated loan proceeds, the treatment of deposits already paid, remaining buyer funds and estimated closing costs.
Do not assume the additional cash required would equal the entire valuation shortfall-or that an existing loan quote would remain unchanged. Have the lender calculate the effect under the actual program being considered, including any implications for eligibility or pricing.
For an owner whose wealth is held across investments and other properties, distinguish accessible closing funds from assets that would require a sale, transfer or separate borrowing decision. Ask the financial adviser to review the timing and consequences of making that cash available. A useful reserve is one the buyer can deploy when required, not merely an amount on a balance sheet.
A residence can be compelling to its buyer without every element of its appeal receiving the same treatment in an appraisal. Ask the lender which comparable transactions would be considered and how the valuation would address residence size, floor, outlook and the project’s revised configuration. These are questions for the valuation process, not assurances of a particular outcome.
A buyer also considering Alba West Palm Beach should distinguish a personal shortlist from lender-accepted comparables. Inclusion in the same property search does not establish that another building will support Shorecrest’s valuation.
The same discipline applies when reviewing Forté on Flagler West Palm Beach. Ask which closed transactions the appraiser would consider relevant rather than treating asking prices or project marketing as substitutes for valuation evidence.
If the appraisal raises concerns, request the lender’s reconsideration-of-value procedure, required documentation and expected review sequence. Establish whether the process can fit within contractual deadlines. A possible review is neither a guaranteed revision nor an automatic extension of the closing obligation.
Related Ross secured a $157 million construction loan from GoldenTree Asset Management, and Shorecrest’s groundbreaking took place on April 2, 2026. These are development milestones, not a guaranteed completion date or buyer-closing date. GoldenTree’s construction-financing role does not establish an end-buyer mortgage offering.
For the purchaser, the relevant comparison is between the developer’s documented closing window and the lender’s written lock terms. Request the lock’s start date, expiration date, extension rules, extension charges and any float-down provision. Ask which conditions must be satisfied for the quoted terms to remain available.
Then test a potential timing mismatch: if closing occurs later than anticipated, can the lock be extended, who bears the cost, and what happens if an extension is unavailable? If a float-down is offered, ask precisely when it can be exercised and what restrictions apply. Do not treat that feature as standard or assume it is free.
A parallel inquiry at Mr. C Residences West Palm Beach requires its own timing analysis. Financing terms discussed for one purchase should not be carried into another without lender confirmation.
Whether the selection is a penthouse or another residence, have counsel identify deposit obligations, closing-notice provisions and any financing or appraisal protections in the actual agreement. Do not assume the purchase is contingent on loan approval-or that it is not. The contract must answer that question.
Ask counsel to explain what happens if financing is reduced, delayed or unavailable, and whether any deadlines govern the buyer’s response. Separately, ask the lender which borrower, valuation and project-related conditions remain outstanding. A financing conversation is not the same as a contractual right to exit.
Consider valuation and timing together. A lower appraisal and a later closing could affect liquidity at the same time. Have the lender model that combined scenario, then have counsel assess the contractual choices available. The purpose is a coordinated decision, not separate reassurances from advisers working on different assumptions.
Before committing, assemble one current purchase file: residence documents, lender scenarios, counsel’s contract review and written lock terms. Assign responsibility for obtaining closing updates and revisiting the financing plan when those updates change.
Shorecrest’s waterfront proposition may guide the selection. A clear understanding of valuation exposure, accessible cash and contractual timing should guide the commitment.
For a discreet conversation about your West Palm Beach purchase priorities, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationShorecrest is a Related Ross waterfront condominium project on North Flagler Drive in West Palm Beach. February 2026 project details identify the address as 1865 North Flagler Drive.
The program comprises 100 residences and approximately 323,000 square feet. Layouts include two to four bedrooms and a penthouse collection.
The revised project’s pricing range is approximately $2.7 million to $7 million. This is historical pricing context, not a current availability quote.
An appraisal gap occurs when the appraised value is below the agreed purchase price. Its effect on loan proceeds and required cash depends on the lender’s actual underwriting terms.
Ask the lender to compare an appraisal at the purchase price with a below-contract valuation. Each scenario should identify loan proceeds, deposits credited, remaining buyer funds and estimated closing costs.
Ask the lender which reconsideration-of-value procedure applies and what documentation it requires. A review does not guarantee a higher valuation or extend contractual deadlines automatically.
Evaluate the lender’s written lock terms against the developer’s documented closing window. No Shorecrest-specific lock program or universally appropriate lock date is established here.
The available options depend on the lender’s written terms. Confirm extension availability, charges and the consequences if an extension is unavailable before relying on a lock.
GoldenTree Asset Management provided the $157 million construction loan. That role does not establish an end-buyer mortgage offering.
No. The April 2, 2026 groundbreaking is a development milestone, not a guaranteed completion or buyer-closing date.