A Greenwich-to-Surfside move calls for more than a tax comparison. Evaluate the full annual ownership budget, separate hospitality spending from mandatory charges, and examine how structural reserves and repair funding could shape future contributions.
Moving from Greenwich to Surfside is a decision about how a home should support daily life. The financial question is equally personal: which responsibilities will remain yours, which will rest with an association, and which services will be charged as you use them?
The useful comparison is not Connecticut property tax against Florida condominium dues. It is a complete annual ownership budget for each candidate property, followed by an assessment of how that budget could evolve. Select a residence for both its immediate appeal and the obligations that accompany it.
For a buyer considering Arte Surfside, the discipline is straightforward: assess the residence and its financial documents together. A quoted monthly charge is a starting point, not a complete account of ownership costs.
Greenwich’s fiscal-year 2025-26 mill rate was 12.041, effective July 1, 2025. Treat it as a dated benchmark, not a rate to carry into later years. The town’s 2025 revaluation applies to July 1, 2026 tax bills; the associated mill rate was scheduled to be set in May 2026.
For a purchase decision, obtain the applicable tax figures and property-specific estimates on both sides. Those Greenwich dates establish neither that Connecticut ownership is inherently predictable nor that Surfside will produce a lower annual bill.
Keep municipal taxes separate from association assessments. They address different obligations, and a scheduled revaluation says nothing about whether a condominium association might require additional capital. Use the same ownership period for both comparisons, and distinguish confirmed bills from estimates.
Create a consolidated annual schedule covering property taxes, insurance paid directly, association charges, approved assessments, association-debt costs charged separately, private maintenance, and hospitality spending. If the purchase is financed, show personal debt service separately so financing choices do not obscure the property’s operating costs.
Break association charges into operating expenses and reserve contributions where the budget allows. Then identify what is already included. Counting an association’s insurance premium or reserve contribution again as a separate household expense would overstate the total. Assuming the association covers every personal insurance or maintenance obligation could understate it.
Rising Florida property-insurance costs have added pressure to condominium budgets alongside reserve funding and major repairs. Ask how the adopted budget addresses insurance rather than applying a statewide assumption to a particular residence.
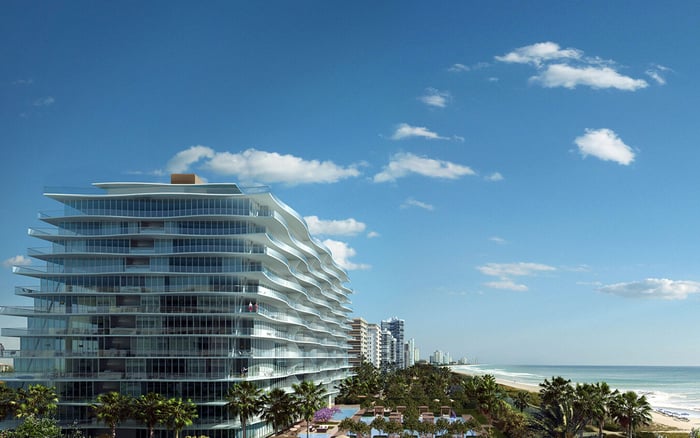
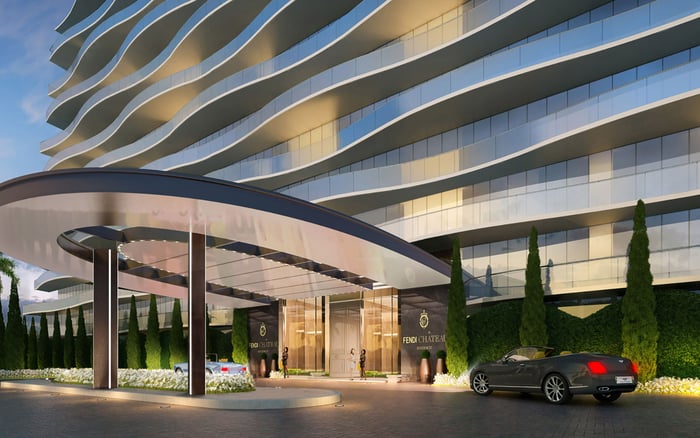
When comparing Fendi Château Residences Surfside with another candidate, put those categories on a consistent basis before judging which quoted fee represents better value. This is a comparison method, not a conclusion about either building’s finances.
Hospitality spending deserves its own schedule. Request written details for any mandatory service charges, club dues, parking, cabanas, dining, and other pay-per-use services that apply to the property. Distinguish recurring contractual obligations from elective spending and discretionary gratuities.
There is no sound basis for applying a universal Surfside service-charge percentage or tipping allowance to every residence. Nor should a buyer assume that familiar Greenwich practices translate directly to a different ownership arrangement.
For The Surf Club Four Seasons Surfside, as for any candidate where service is central to the purchase decision, ask what is included, what is billed separately, and whether a service charge includes gratuity. Confirm any property-specific tipping policy in writing rather than inferring it from the name.
Budget around your intended use. Frequent entertaining and occasional occupancy call for different discretionary allowances, even when mandatory charges are identical. That distinction makes the cost of convenience visible without treating every optional pleasure as a fixed obligation.
Florida enacted SB 4-D in 2022 after the Champlain Towers South collapse, introducing building-safety inspections and stronger reserve requirements. The framework primarily concerns condominium and cooperative buildings with three or more stories.
Milestone inspections and Structural Integrity Reserve Studies, or SIRS, serve different purposes. Inspections assess older buildings’ structural condition; SIRS determine the savings needed for future major repairs. Covered associations must undertake SIRS at least every decade. Structural reserve planning encompasses roofing, load-bearing elements, plumbing, electrical systems, and fire-protection elements.
The 2022 reforms restricted the ability to waive required structural reserves. Subsequent changes introduced flexibility but did not erase the underlying financial responsibilities.
Legislation signed in June 2025, effective July 1 that year, extended the SIRS deadline by one year. It also allowed qualifying associations, subject to statutory conditions, to pause or reduce reserve contributions for up to two years following a milestone inspection while funding necessary repairs. Loans or lines of credit for reserve funding became possible with majority owner approval.
Mandatory inspections and structural-reserve obligations remained substantially in place. Have counsel establish the requirements and timing that apply to the building under consideration rather than relying on an original deadline or a generalized description of the law.
A brand is not evidence of stronger reserves, more predictable fees, or lower assessment risk. Apply the same financial review regardless of architectural distinction or service positioning.
For a candidate such as Ocean House Surfside, request the applicable reserve studies, milestone inspection findings, adopted budget, reserve balances, planned contributions, outstanding loans, and approved assessments. Establish which documents govern the actual ownership period and which figures remain projections.
Model association charges over three to five years. Separate operating costs, reserve contributions, repair assessments, and loan payments, then reconcile them to avoid duplication. Ask what happens after any temporary contribution reduction ends.
Read reserve growth alongside planned withdrawals and repair timing. A balance alone cannot show whether future obligations are adequately addressed. Likewise, borrowing changes the funding mechanism; it does not eliminate the cost of the underlying work. Use documented commitments for the base case and clearly labeled assumptions for alternatives-not a blanket forecast that fees will double or triple.
A Surfside single-family home falls outside this condominium and cooperative reserve framework. It does not remove responsibility for maintenance, insurance, or major repairs. The buyer should instead build a private maintenance and capital-replacement plan alongside the annual operating budget.
The final choice is not simply lower dues versus higher dues. It is the preferred balance of private control, shared obligations, service, and financial visibility. Favor the property whose ongoing commitments you understand and whose future funding demands fit comfortably within your plans.
For a considered approach to your Greenwich-to-Surfside property search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationInclude property taxes, directly paid insurance, association charges, separately charged assessments or association debt, private maintenance, and hospitality spending. Avoid counting expenses twice when they are already included in dues.
No. It is the fiscal-year 2025–26 benchmark, and the 2025 revaluation applies to July 1, 2026 tax bills; obtain the applicable figures for your comparison.
No general savings conclusion is established. Compare property-specific taxes and the full ownership budget rather than relying on location alone.
A universal percentage is not established. Obtain each property's written schedule and distinguish mandatory charges from discretionary gratuities.
A milestone inspection assesses an older building’s structural condition. A Structural Integrity Reserve Study determines savings needed for future major repairs.
It primarily concerns condominium and cooperative buildings with three or more stories. Have counsel confirm the requirements applicable to the specific building.
No. It introduced deadline and funding flexibility, including conditional contribution reductions and owner-approved borrowing, while mandatory inspections and structural-reserve obligations remained substantially in place.
Request the applicable SIRS, milestone inspection findings, adopted budget, reserve balances, planned contributions, outstanding loans, and approved assessments. Use them to model three to five years of costs.
No such assumption is justified. Evaluate the association’s reserves, planned repairs, debt, and budget independently of the brand.
It falls outside this condominium and cooperative reserve framework, but maintenance and major repairs remain the owner’s responsibility. Build a private capital-replacement plan into the purchase analysis.