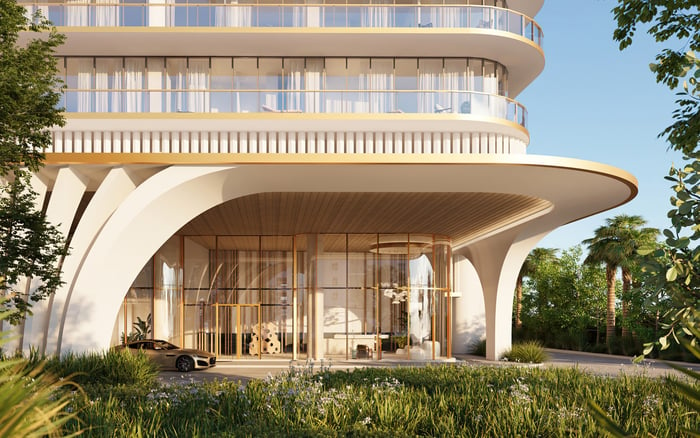
A discreet move-in begins with precise paperwork. For 57 Ocean buyers, this audit separates vendor insurance, common-area damage deposits, and personal coverage, with a practical framework for securing written approvals and refund terms.
The floor plan describes the residence. Move-in arrangements determine how smoothly ownership begins. At 57 Ocean Miami Beach, at 5775 Collins Avenue, Miami Beach, FL 33140, a buyer's diligence should extend beyond the apartment to the people, insurance documents, and delivery arrangements needed to bring it to life.
For an owner coordinating furnishings, installers, and a household move, the objective is straightforward: secure written approval before committing to a schedule. A vendor's insurance certificate, an elevator reservation, and a refundable damage deposit address different concerns. None substitutes for another.
57 Ocean's current deposit amount, certificate requirements, elevator charges, and refund procedure require written confirmation from management. General high-rise practices provide a useful checklist, not the building's rules.
Formal condominium documents deserve priority over promotional descriptions. The developer-disclosure framework referenced for 57 Ocean includes Section 718.503, Florida Statutes, concerning documents furnished by a developer to a buyer or lessee. That reference is neither a move-in schedule nor a statement of current vendor requirements.
Whether considering a developer purchase or a resale, request the current move-in application, vendor policy, insurance template, and any applicable fee schedule. Ask management which documents govern your planned activities and whether deliveries or contractor work require separate instructions.
Keep these documents together with the name of the person authorized to approve the move. An attractive residence and a well-organized arrival require separate diligence. A buyer also considering Faena House Miami Beach should request that property's requirements rather than assume a neighboring condominium uses the same forms or approvals.
A certificate of insurance, commonly called a COI, provides evidence that a moving company carries liability insurance. Managed high-rises commonly request it before move day, with liability and workers' compensation coverage often included in submissions. Those regional practices do not establish the coverage limits required at 57 Ocean.
Start with management's current template. Forward it to the vendor and its insurance representative rather than requesting a generic certificate. Obtain written clarification of:
The exact legal names required for the certificate holder and any additional insureds.
Required coverage types, limits, and endorsements.
Policy expiration requirements for the scheduled work.
The submission deadline and designated approval contact.
Check certificate-holder wording and additional-insured requirements separately. Ask the insurance representative to address each requirement, including any supporting endorsements management requests. Then obtain management's acceptance of the submission. Sending a document is not the same as receiving approval.
Regional practice often involves submission several business days before a move. Do not mistake that general guidance for a 57 Ocean deadline. Confirm the actual lead time and allow room for corrections before confirming the vendor's arrival.
The phrase move-in insurance can obscure three distinct questions: whether the vendor meets the building's requirements, how common-area damage is handled, and whether the owner's possessions are adequately protected.
A vendor's COI and an association damage deposit are not proof of coverage for furniture, artwork, or other belongings. Nor do they replace the buyer's own insurance. Review protection for the household shipment and the residence separately with the appropriate insurance adviser and mover.
The same distinction matters when comparing ownership logistics at Five Park Miami Beach. The useful comparison is not which building appears to require less paperwork, but whether the buyer can clearly identify the applicable requirements and unresolved coverage questions. No specific vendor policy for that property is implied here.
Avoid borrowing requirements from municipal forms, too. Miami Beach's insurance requirements for parties using city facilities do not automatically establish the rules for a private condominium.
Refundable moving deposits commonly protect elevators, corridors, lobbies, and loading areas against damage. General high-rise practice may tie a refund to an inspection and confirmation that no chargeable damage occurred. That is a reason to ask precise questions, not a verified description of 57 Ocean's refund policy.
Before paying any requested deposit, obtain the amount, payment method, payee, and refund terms in writing. Ask who performs the inspection, when it occurs, what deductions are permitted, and when the balance must be returned. Clarify whether potential liability can exceed the deposit; do not assume the payment caps exposure.
Keep three categories separate: an administrative charge, a refundable damage deposit, and any nonrefundable elevator or cleaning fee. Ask whether each applies; do not presume that 57 Ocean charges any of them. An itemized explanation of what is recoverable, and under what conditions, is more useful than a single move-in total.
Finally, ask how deductions are documented and how an owner can question a charge. The refund process deserves as much attention as the initial payment.
A household mover, a furniture delivery crew, an installer, a designer, and a renovation contractor may face different approval requirements. Ask management to distinguish those categories before treating one accepted certificate as sufficient for the entire furnishing program.
For each planned visit, confirm the vendor's scope, required paperwork, approved moving window, elevator arrangements, and loading instructions. Managed high-rise moves may involve a formal application and separate scheduling steps. Do not assume insurance acceptance reserves access.
If the plan changes, ask whether the approval must change too. A revised date, an additional crew, or work extending beyond delivery should prompt a fresh check with management. Resolve uncertainty while adjustments remain easy, not when a vehicle is waiting outside.
Request a pre-move condition record for the agreed common-area route and ask whether a joint walkthrough is available. Retain dated photographs where permitted, along with payment receipts, accepted insurance submissions, and scheduling approvals.
After the move, request the inspection outcome and written confirmation of the refund status. If deductions are proposed, ask for the supporting record and an itemized calculation. These are prudent buyer practices, not a promise of a particular inspection or reimbursement procedure at 57 Ocean.
A well-managed arrival preserves attention for the residence itself. The essential discipline is simple: distinguish insurance from deposits, acceptance from submission, and general practice from a building-specific rule.
For a considered approach to South Florida condominium ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversation57 Ocean is at 5775 Collins Avenue, Miami Beach, FL 33140.
A current amount is not established by the marketing materials. Obtain the applicable amount and payment terms directly from management in writing.
A COI provides evidence that the moving company carries liability insurance. It should be checked against the building's specific requirements before the move.
Request exact entity names, certificate-holder and additional-insured wording, coverage limits, required endorsements, expiration requirements, the submission deadline, and the approval contact.
General high-rise practice often calls for submission several business days ahead. Confirm 57 Ocean's actual deadline rather than relying on that general timing.
It should not be treated as proof of coverage for the buyer's possessions or a substitute for personal insurance. Review shipment and residence coverage separately.
No. Ask separately about refundable damage deposits and any nonrefundable elevator, cleaning, or administrative charges, without assuming that 57 Ocean imposes them.
Confirm the inspection process, permitted deductions, refund deadline, and documentation for charges. Also ask whether liability can exceed the deposit.
Do not assume it can. Ask management whether each vendor category and scope of work requires separate paperwork or approval.
No. Municipal requirements for parties using city facilities do not automatically establish insurance requirements for a private condominium.