A considered Denver-Miami lifestyle requires more than two well-chosen homes. Coordinate estate liquidity, title protection, beneficiaries, and property-specific operating budgets so each residence remains manageable through a change in ownership.
A life divided between Denver and Miami offers two distinct settings for the same household. The more consequential design decision, however, is often invisible: how the residences will be owned, insured, funded, and transferred when circumstances change. A property can pass to the intended beneficiary while the cash needed to maintain it remains elsewhere.
For a buyer considering The Residences at 1428 Brickell, the Brickell search should run alongside a review of the Denver estate plan. The question is not simply whether both homes are affordable today. It is whether those responsible for them tomorrow will have the authority, information, and accessible funds to act without a rushed sale.
A Colorado beneficiary deed transfers a real-property interest at the owner's death without transferring ownership during life. It must be recorded before death to be valid and can generally be revoked during the owner's lifetime. These features can make it a useful estate-planning instrument, but they do not turn the property into readily available cash.
A statutory four-month waiting period can delay a beneficiary's sale of inherited Colorado property in many cases. This is a potential transaction delay, not a universal prohibition on every sale or refinancing. Counsel and the title professional should assess the specific property and proposed transaction before anyone relies on a closing date.
The practical distinction is straightforward: transfer and liquidity are separate events. Do not make the Miami residence's operating plan depend on immediate proceeds from the Denver home. Identify another funding source, confirm who can access it, and test whether it remains available during an estate transition.
Title insurance and homeowners insurance answer different questions. In Colorado, title insurance addresses past defects in the chain of title rather than future physical damage. An owner's policy protects the purchaser's ownership interest; a lender's policy protects the lender's loan interest. One should not be mistaken for the other.
Standard title-policy forms generally extend protection to a Colorado beneficiary-deed recipient, subject to the policy's terms and exceptions. Ask the title professional to confirm how the actual policy treats the intended transfer rather than assuming every ownership change receives identical protection.
Homeowners coverage requires a separate review. Casualty insurance is generally a personal contract and may not automatically follow a beneficiary-deed transfer. The transition checklist should identify who contacts the insurer, what documentation is needed, and how coverage will be confirmed. Retaining title protection does not establish that the home itself remains properly insured.
Florida title insurance protects against prior ownership claims, outstanding liens, and other title defects. It remains distinct from homeowners insurance. Florida law does not generally require homeowners coverage, although mortgage lenders commonly require it as a condition of the loan. A cash purchase removes neither the physical risks nor the need to evaluate protection.
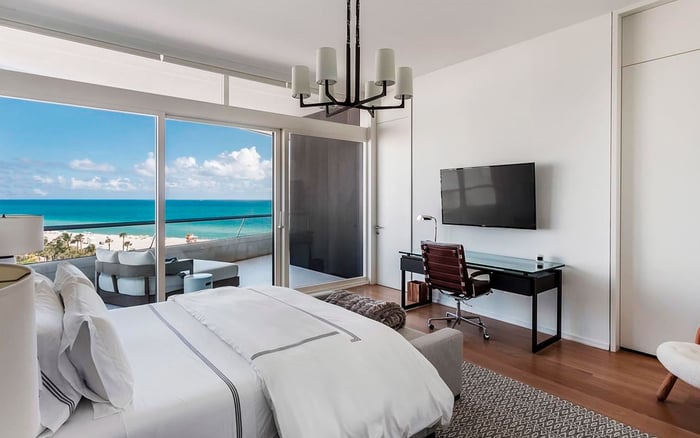
For a Miami Beach purchase, including a residence under consideration at The Perigon Miami Beach, make the insurance review property-specific. Request the applicable coverage documents and individual quotes before finalizing the operating budget. A project name is no substitute for policy terms.
Homeowners policies do not cover flood damage. Separate flood coverage therefore warrants explicit consideration. Ask the insurance adviser to distinguish title, homeowners, and flood protection and explain the relevant exclusions and deductibles. Describe the intended occupancy pattern rather than assuming a two-city schedule has no bearing on the review.
A Miami second home should not automatically be treated as Florida homestead. Homestead inheritance protections and property-tax exemption eligibility are distinct questions; the ownership plan should not collapse them into a single assumption.
Florida homestead carries special constitutional protections and inheritance restrictions, particularly when an owner leaves a surviving spouse or minor children. Depending on family circumstances and the applicable rules, a surviving spouse may receive a life estate while descendants hold remainder interests. That outcome is not automatic in every estate.
Before finalizing the deed or revising a trust, ask Florida counsel to determine whether homestead rules apply and how they affect the intended transfer. Coordinate that answer with Colorado counsel. A structure selected for one residence should not simply be replicated for the other without examining its consequences.
Review deeds, bank and brokerage accounts, LLC interests, trusts, beneficiary forms, and marital agreements together. Examining each document in isolation can leave the family's intended outcome unclear.
Create a shared ownership-and-funding schedule for the advisers to reconcile. For each home, identify the current owner, intended recipient, person expected to manage expenses, and proposed source of cash. Then establish who will have legal authority to use those funds and when that authority begins. These are questions to resolve, not permissions to presume.
The family should also discuss whether the intended recipient wants to retain the residence. A plan for continued ownership calls for a different cash-flow discussion from one anticipating a sale. Record the preference while leaving room for circumstances to change.
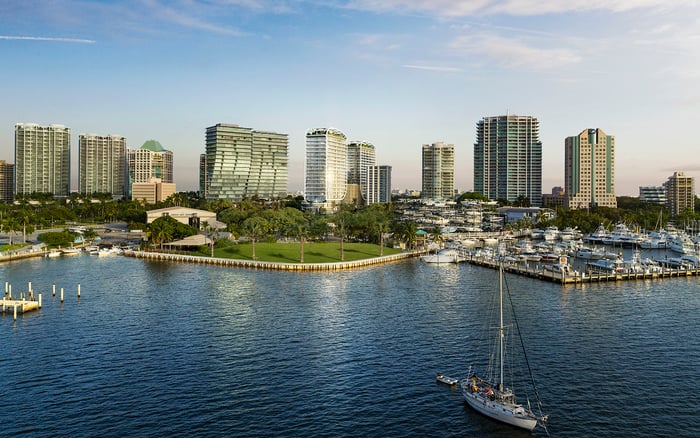
For a Coconut Grove search that includes Park Grove Coconut Grove, compare the residence-level obligations with those of the Denver home. Neither the purchase price nor the appeal of an address is a reliable shortcut for annual carrying costs.
Request actual tax bills, insurance quotes, association budgets, utility records, maintenance contracts, financing terms, and capital-reserve needs. Separate recurring expenses from anticipated capital work, and avoid counting a service twice if an association payment already includes it. Label estimates clearly and update them when documents arrive.
Consider a two-year liquidity schedule covering both homes. This is a planning recommendation, not a legal requirement or an established industry standard. Map payment dates and expected funding sources, then test a scenario in which the Denver sale is delayed. Ask the advisers what accessible reserve would suit that scenario rather than imposing an unsupported percentage or market-average budget.
Bring the estate attorneys, title professionals, insurance adviser, and financial adviser into one coordinated review. Keep deeds, policies, beneficiary confirmations, property contacts, and the operating schedule accessible to those authorized to use them. Revisit the arrangement when ownership, financing, family circumstances, or intended use changes.
The objective is continuity: two residences that support the family's life without forcing an avoidable financial decision during an already difficult transition. This framework is a starting point for individualized legal, tax, and insurance advice, not a substitute for it.
Explore South Florida residences with MILLION as you shape a considered two-city life.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationIt transfers a real-property interest at the owner's death without transferring ownership during life. It must be recorded before death to be valid and can generally be revoked during the owner's lifetime.
They should not assume immediate sale proceeds. A statutory four-month waiting period can delay sales in many cases, although it is not a universal prohibition on every sale or refinancing.
An owner's policy protects the purchaser's ownership interest, while a lender's policy protects the lender's loan interest. Neither should be confused with insurance against physical damage.
Standard title-policy forms generally extend coverage to the beneficiary-deed recipient, subject to policy terms and exceptions. Have the title professional confirm the actual policy's treatment.
Not necessarily, because casualty insurance is generally a personal contract. Coverage should be reviewed with the insurer when title transfers.
Florida law does not generally require homeowners insurance, but mortgage lenders commonly require it as a loan condition. Cash buyers should still evaluate protection against physical-property risks.
Florida's statutory disclosure language warns that homeowners policies do not cover flood damage. Separate flood coverage warrants consideration for a Miami residence.
No such assumption should be made. Counsel should evaluate homestead inheritance protections separately from property-tax exemption eligibility and consider the family's circumstances.
Compare deeds, bank and brokerage accounts, LLC interests, trusts, beneficiary forms, and marital agreements together. Also identify who is intended to manage each residence and how expenses will be funded.
No, it is a planning recommendation, not a legal requirement or established industry standard. Build it from property-specific costs and test whether accessible funding can support both homes if a sale is delayed.