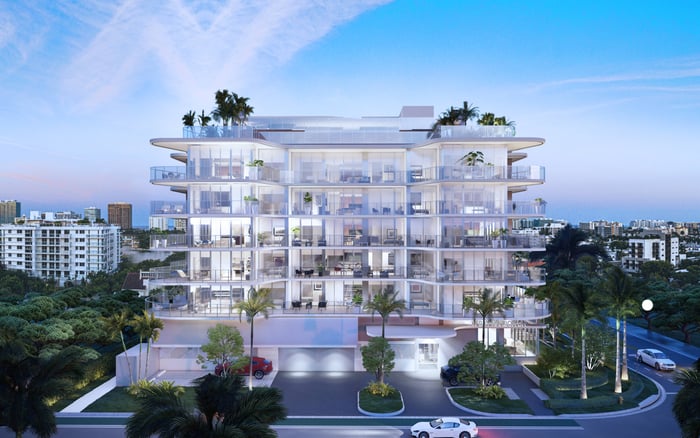
A buyer-focused guide to separating replacement-cost appraisals from policy appraisal clauses, translating storm deductibles into potential owner exposure, and reviewing loss-assessment protection at Origin Bay Harbor Islands.
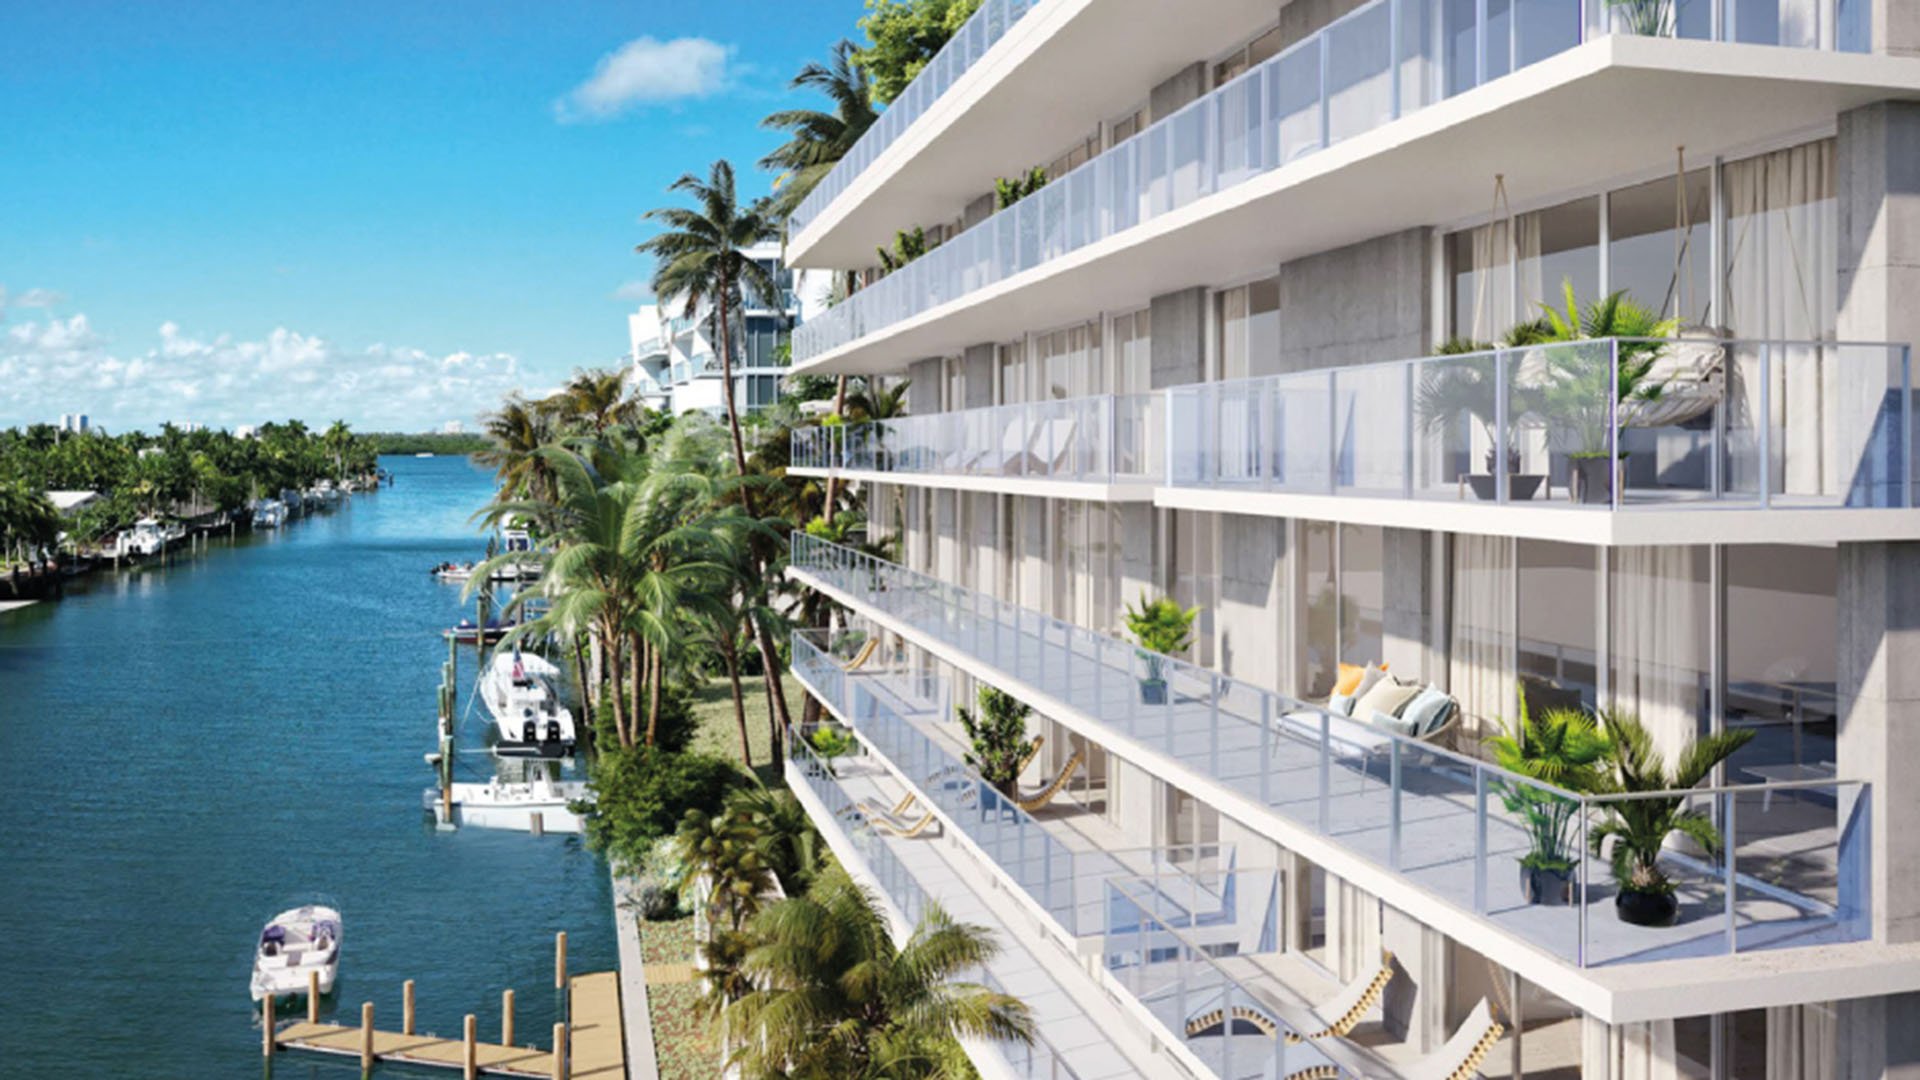
For a buyer considering Origin Bay Harbor Islands, insurance diligence belongs alongside the purchase agreement and ownership budget. A residence can satisfy every aesthetic preference yet leave a separate financial question unresolved: what might the owner have to contribute after a covered building loss?
The answer requires more than confirmation that an association carries insurance. Replacement-cost values, policy deductibles, assessment allocations and the buyer’s own condominium policy must be read together. Marketing language is not evidence of Origin’s carrier, insured value, deductible, appraisal provisions or assessment obligations.
The essential distinction is between an insured building and an owner protected against every resulting expense. Those are not equivalent promises.
Florida’s condominium insurance framework requires associations to maintain adequate property insurance and determine replacement cost through an independent insurance appraisal or appraisal update at least every three years. That valuation concerns the cost of replacing insured property, not the resale price of an individual residence.
For buyers, the document request is clear: obtain the current replacement-cost appraisal or update and review its date alongside the master-policy declarations. A purchase valuation and an insurance valuation answer different questions; neither should substitute for the other.
An insurance-policy appraisal clause is a separate contractual matter. Do not assume the statutory replacement-cost appraisal explains how a policy’s appraisal provision operates. Request the complete policy, including forms and endorsements, and have a coverage attorney explain any appraisal language, its scope and its procedural requirements before relying on it.
For a buyer also considering Alana Bay Harbor Islands, this distinction provides a consistent basis for comparison. Compare each association’s actual documents rather than assuming similarly positioned residences share insurance arrangements.
“Hurricane,” “named storm” and “windstorm” should not be used interchangeably. The applicable policy wording matters, including the event that activates a particular deductible. A tropical storm, tornado or hail event should not automatically be treated as triggering the same deductible as a hurricane.
A deductible is the portion of a covered loss for which the policyholder is responsible under the policy. Hurricane deductibles can be percentage-based and are generally higher than ordinary deductibles. Depending on the policy, they may operate on a calendar-year basis.
Three questions are therefore essential: what event activates the deductible, what value supplies the calculation base, and how does the deductible apply over time? The percentage alone cannot answer them.
For Origin, ask the reviewing professional to identify the exact storm wording in the operative policy. If the documents use “hurricane,” preserve that term. If they use “named storm,” examine that wording rather than importing the treatment of a different policy.
A seemingly small percentage can represent a substantial association obligation. As a purely hypothetical illustration, a 2% deductible calculated on a $100 million insured building limit equals $2 million. These are not verified insurance terms for Origin Bay Harbor Islands.
The illustration shows why a covered storm loss can still lead to an owner assessment. Insurance may respond to the underlying damage while leaving the association responsible for its deductible. The practical question is how that responsibility could reach the individual residence.
Do not simply divide a building-level shortfall by the number of units. An owner’s share depends on the applicable allocation rules, which are not necessarily equal for every residence. Review the condominium declaration and relevant assessment documentation before estimating a personal obligation.
When comparing Origin with Bay Harbor Towers, follow the same sequence: identify the deductible, convert it into dollars using the applicable policy base, then examine the allocation rules. This is a diligence framework, not a statement that either property has a particular deductible or assessment.
Residential condominium unit-owner policies in Florida must include at least $2,000 in property loss-assessment coverage for qualifying direct losses to collectively owned property. That minimum does not establish that an owner has enough protection for a potential share of a building-wide storm deductible.
Loss-assessment coverage applies to certain assessments involving direct damage to collectively owned property caused by a peril insured under the unit-owner policy. It remains subject to limits and exclusions. It is not blanket reimbursement for every condominium special assessment.
The statutory deductible for this coverage cannot exceed $250 per direct property loss. If the owner has already paid a deductible for another property loss arising from the same event, no additional deductible applies to the loss-assessment coverage.
Timing also matters. The applicable loss-assessment limit is the limit in effect one day before the event that caused the loss. Multiple assessments arising from the same direct property loss do not require the insurer to pay beyond that limit.
Before selecting a proposed HO-6 policy, ask a Florida condominium-insurance broker or coverage attorney whether assessments attributable to the master-policy storm deductible are covered and whether a separate sublimit applies. A larger headline limit does not, by itself, answer that question.
Request the current master-policy declarations, complete policy forms and endorsements, replacement-cost appraisal, condominium declaration, assessment notices and proposed HO-6 policy. Have the documents reviewed together rather than treating the association’s coverage and the owner’s policy as unrelated purchases.
Ask the reviewer to distinguish confirmed obligations from hypothetical exposure. The review should connect the master-policy deductible, the declaration’s allocation rules and the HO-6 policy’s applicable coverage, exclusions and limits. It should also explain any contractual appraisal provision separately from the replacement-cost valuation requirement.
A buyer comparing Onda Bay Harbor or extending a search to Bal Harbour can apply the same discipline without assuming identical policy terms. The objective is not to rank residences by a premium or deductible percentage in isolation. It is to understand the financial responsibilities attached to the particular purchase.
For Origin, the most useful outcome is a documented explanation of what the association insures, what an owner could be asked to fund, and what the proposed personal policy would actually cover. That clarity supports an ownership decision made with the same care as the choice of residence itself.
Explore South Florida residences with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Buyers should confirm the carrier, insured value, deductibles and contractual provisions in the actual master policy and related documents.
It addresses the replacement cost of insured property, not an individual residence’s resale price or market value.
Florida’s condominium insurance framework requires an independent insurance appraisal or appraisal update at least every three years.
No. The replacement-cost valuation and any contractual appraisal provision are separate matters requiring separate review.
No. Preserve the policy’s exact terminology and confirm which events activate each deductible.
The applicable insured value determines the dollar amount. Hypothetically, 2% of a $100 million insured building limit is $2 million, but these are not verified Origin terms.
Not necessarily. Each owner’s share depends on the applicable allocation rules and assessment documentation.
The statutory minimum is $2,000 for qualifying direct losses to collectively owned property. That amount does not establish adequate protection for an owner’s potential exposure.
No. Multiple assessments arising from the same direct property loss do not require payment beyond the applicable loss-assessment limit.
Ask whether it covers assessments attributable to the master-policy storm deductible and whether a separate sublimit applies. Review the answer alongside the association’s policy and allocation rules.