A buyer-focused framework for examining reserve accessibility, investment restrictions, structural funding obligations, and assessment timing before purchasing at Alana Bay Harbor Islands.
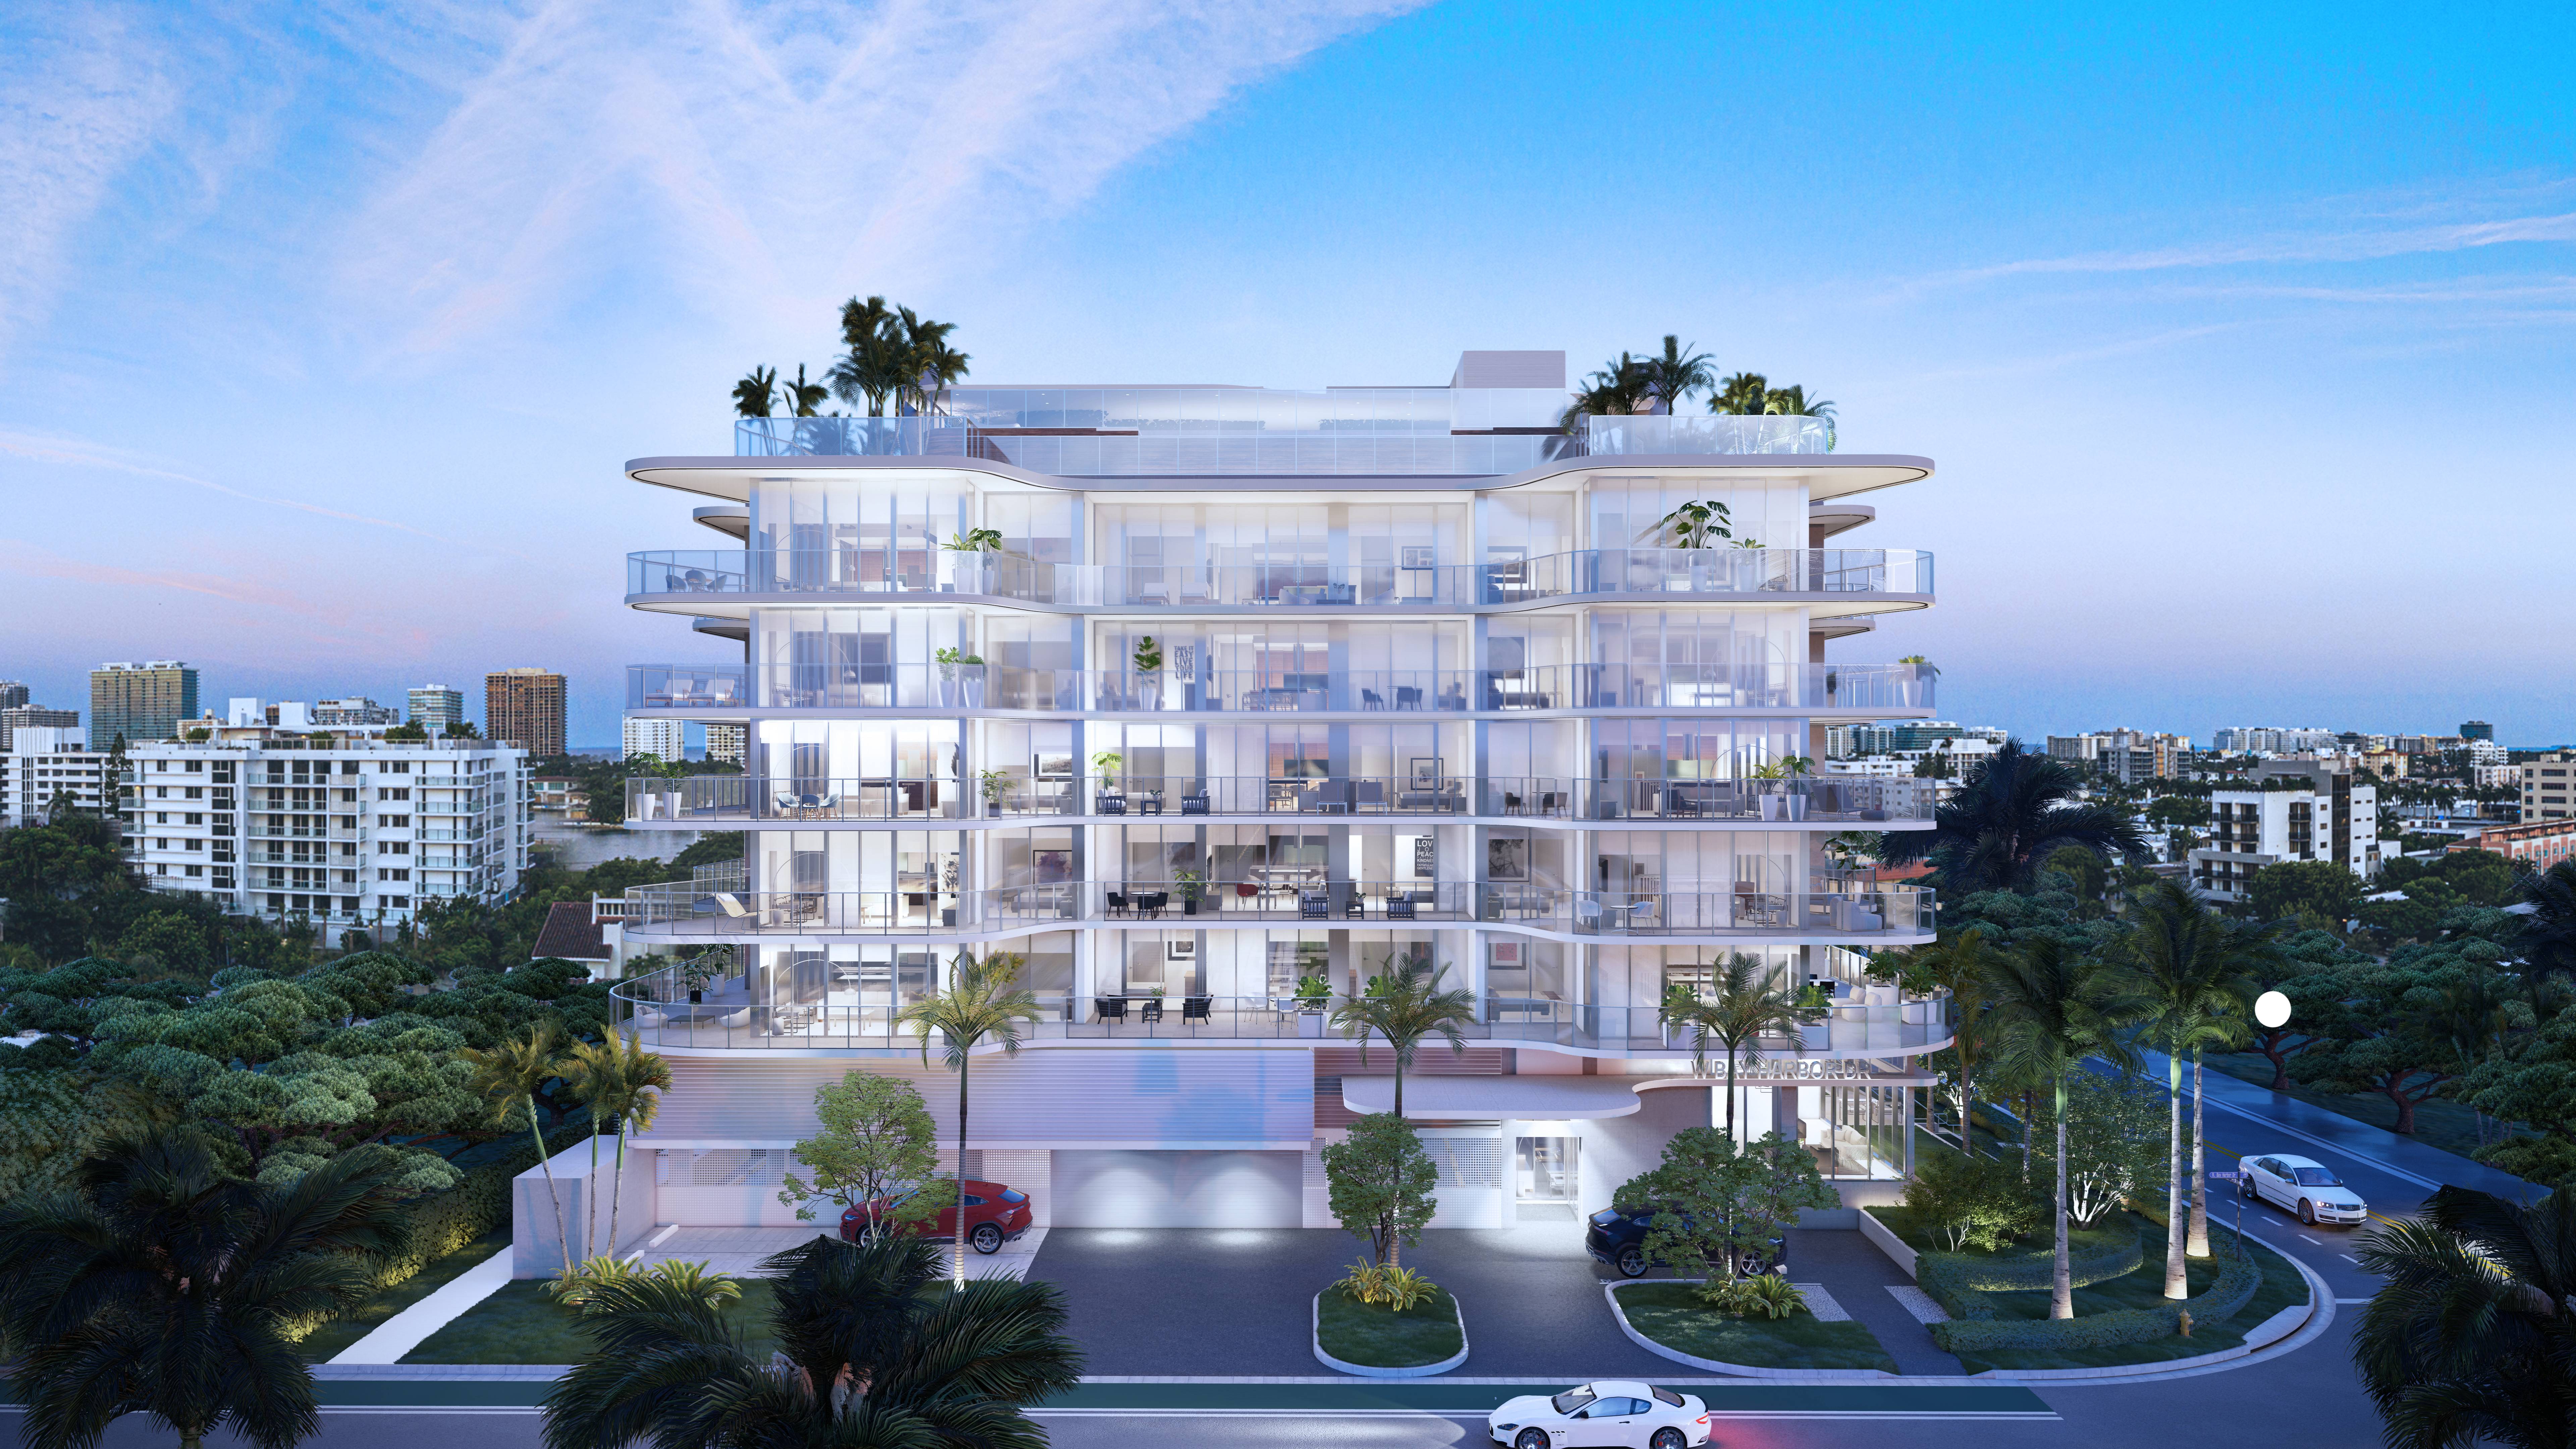
For a buyer considering Alana Bay Harbor Islands, financial diligence deserves the same attention as the residence itself. The central question is not simply how much the association holds in reserves. It is whether those funds are accessible when work must be paid for, whether contributions match anticipated needs, and when additional owner payments could fall due.
A reserve balance is a snapshot; a purchase decision needs a calendar. Ask management to connect available cash, investment maturities, planned repairs, and assessment collections. That exercise turns an abstract balance into a practical view of ownership costs.
Treat these as questions to resolve through association documents, not conclusions about Alana’s finances. Establish the actual balances, holdings, inspection status, and assessment obligations before taking financial comfort in the purchase.
A Structural Integrity Reserve Study, or SIRS, identifies components requiring reserve funding, estimated remaining useful lives, replacement costs, and a funding schedule. Florida requires SIRS for qualifying condominium buildings with three habitable stories or more. Verify applicability to the specific building; do not assume a study is required, completed, or current.
Required studies generally must be completed at least every 10 years after the condominium’s creation. Request the complete applicable study, then compare its funding schedule with the adopted budget and actual contributions. A completed study does not, by itself, establish adequate funding.
The useful questions are component-specific: What work is anticipated? When is it expected? What cost is assigned to it? How much is being contributed toward that obligation? An aggregate reserve total cannot answer all four.
For buyers also considering Bay Harbor Towers, the same comparison framework applies: examine each association’s documents independently rather than treating neighborhood proximity as evidence of similar funding arrangements.
A milestone inspection evaluates structural conditions. A SIRS is a forward-looking financial-planning tool for repairs and replacements. They serve different purposes; neither should substitute for the other.
Florida’s milestone framework applies to qualifying buildings with three or more habitable stories, generally requiring inspection by December 31 of the year a building reaches age 30 and periodically thereafter. For an Alana purchase, request the certificate-of-occupancy date and applicable inspection notices so counsel can establish the relevant timetable.
Review the complete SIRS alongside applicable milestone-inspection and engineering documents. Ask how identified repair needs translate into project budgets and payment dates. Also request any required written disclosure from engineers or architects bidding on milestone inspections about their intent to bid on related maintenance or repair services. Together, these documents help clarify both the technical findings and the proposed work.
Ask for operating-account and reserve-account statements, along with a schedule showing amounts accessible within 30, 90, and 180 days. These are diligence windows, not assertions about Alana’s holdings or statutory liquidity requirements.
Separate unrestricted cash from funds assigned to particular purposes. Identify balances with withdrawal restrictions, maturity dates, or costs for early access. A useful presentation shows each holding, its availability date, and the expenditure it is intended to support.
The critical comparison is between payment dates and accessible funds. If a project requires an early payment, ask whether the funding plan accommodates it without relying on an unapproved assessment or an uncertain collection date. Request written explanations wherever the timing is unclear.
Request the association’s written investment policy and ask who may authorize purchases, renewals, transfers, and withdrawals. Review how the policy addresses preservation of principal, permitted holdings, concentration, and the timing of cash needs. These are review questions, not descriptions of Alana’s existing policy.
Ask whether maturity dates align with the capital schedule and whether any planned expenditure would require early liquidation of an investment. If funds are described as immediately available, seek supporting account terms rather than relying on that description alone.
A buyer comparing Onda Bay Harbor should apply the same discipline. Evaluate the relationship between holdings and obligations, not just the stated return or total reserve figure.
Capital-call diligence should distinguish three categories: assessments already approved and billed, assessments approved but not yet billed, and projects merely under discussion. Each represents a different stage of decision-making; they should not be combined into a single estimate of immediate liability.
Request approved and proposed assessments, board resolutions, payment schedules, project bids, and recent meeting minutes. For each item, identify the scope, approval status, anticipated payment dates, and amount allocated to the residence, where established.
Required structural-integrity reserves generally cannot be waived, reduced, or redirected through an ordinary owner vote, subject to applicable statutory provisions. Florida’s 2025 reserve-law changes also provide funding alternatives beyond regular assessments, with specified alternatives requiring approval by a majority of the association’s entire voting interests. Have counsel confirm the applicable rules and approvals rather than assuming owners can simply defer funding.
Request a 12-24-month forecast incorporating reserve contributions, capital projects, insurance payments, debt service, and expected assessment collections. Ask management to distinguish funds already held from contributions or collections expected later.
The forecast should explain whether reserve funding depends on regular assessments or another approved method. That distinction matters because the funding mechanism shapes owners’ payment obligations. Ask what happens if collections arrive later than expected or project payments become due earlier.
For buyers considering The Well Bay Harbor Islands alongside Alana, consistent forecast requests make comparisons more useful. The same approach applies when extending a search to Bal Harbour: compare documented obligations, not assumptions about financial strength based on location.
Review the declaration’s allocation of responsibility for building components. Portions outside association ownership or responsibility may require separate owner action, so the association’s reserve plan may not capture every obligation relevant to the residence.
Ask counsel to specify responsibility for assessments approved before closing, installments due afterward, and project overruns. Resolve these issues in the transaction documents rather than relying on a general understanding between buyer and seller.
Finally, obtain updated association confirmation shortly before closing. The objective is a clear picture of ownership obligations: accessible reserves, a documented funding method, identifiable project timing, and an agreed allocation of payments. That clarity provides a more useful foundation for a considered purchase than any reserve total viewed in isolation.
For a considered approach to your next South Florida residence, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationRequest the applicable reserve study, adopted budget, operating and reserve statements, and approved or proposed assessment documents. Use them to connect available funds with scheduled obligations.
A SIRS identifies components requiring reserve funding, estimated remaining useful lives, replacement costs, and a funding schedule.
Florida requires SIRS for qualifying condominium buildings with three habitable stories or more. Verify applicability to the specific building rather than assuming it.
Required SIRS generally must be completed at least every 10 years after the condominium’s creation. Confirm the applicable timetable with counsel.
A milestone inspection evaluates structural conditions, while a SIRS plans financially for future repairs and replacements. Review them together to connect repair needs with funding.
Reserve adequacy depends on component costs, remaining useful lives, and scheduled contributions. Buyers should also establish when funds can actually be accessed.
Request amounts accessible within 30, 90, and 180 days, including maturity dates and withdrawal restrictions. These are practical diligence windows, not stated statutory requirements.
Required structural-integrity reserves generally cannot be waived, reduced, or redirected through an ordinary owner vote, subject to applicable statutory provisions. Counsel should confirm the rules governing any proposed funding alternative.
Separate approved and billed assessments, approved but unbilled assessments, and projects still under discussion. Review resolutions, payment schedules, bids, and meeting minutes to establish each item’s status.
Ask counsel to specify responsibility for assessments approved before closing, installments due afterward, and overruns in the transaction documents. Obtain updated association confirmation shortly before closing.