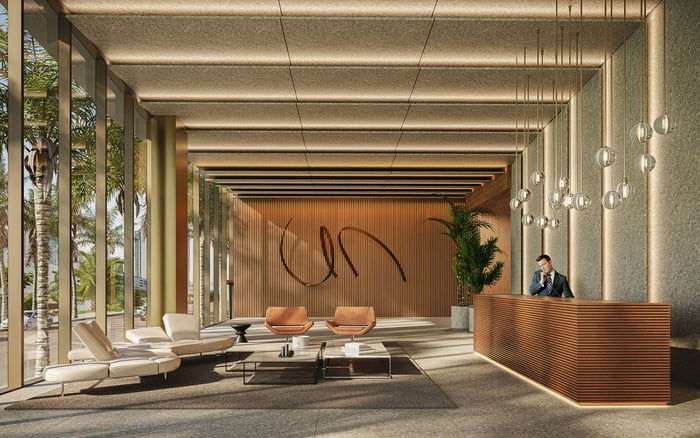
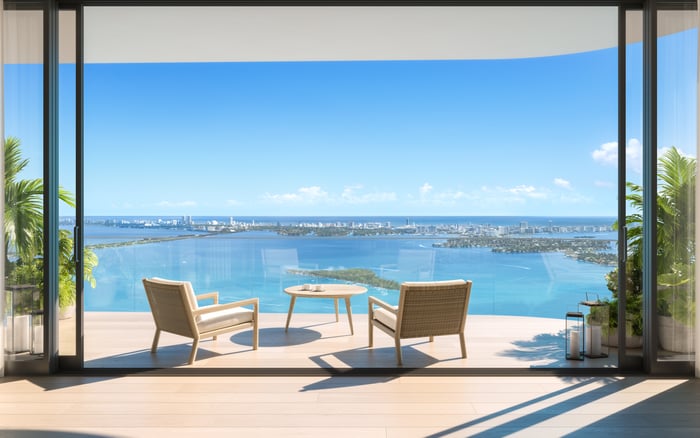
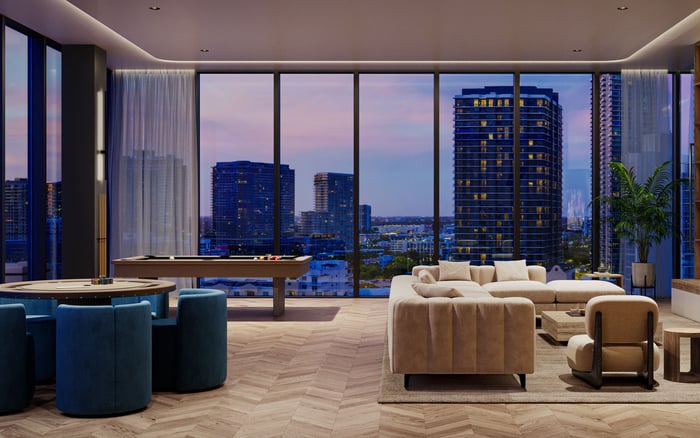
A considered ownership plan for Lilli Miami Edgewater should distinguish building insurance, personal liability and household-employment protection. This buyer’s checklist explains what to review before closing and before staff begin work.
A waterfront residence is both a private retreat and a place where people work, visit and go about daily routines. For a serious buyer considering Lilli Miami Edgewater, the ownership plan deserves the same attention as the floor plan. Domestic-staff insurance and personal umbrella liability address distinct exposures. Neither belongs on a list of finishing details.
LILLI is a proposed waterfront condominium at 717 NE 27th Street in Miami’s Edgewater neighborhood, overlooking Biscayne Bay. Plans call for 53 stories, 117 residences and a height of approximately 636 feet. OKO Group is the developer, with architecture by Adrian Smith + Gordon Gill Architecture.
Those details describe the proposed building, not its insurance arrangements. The essential distinction is straightforward: association protection, owner protection and coverage relating to household employees each require separate review.
Indicative starting pricing in May 2026 was approximately $1.65 million, with offerings including one- to four-bedroom residences, garden estates and penthouses. That figure is not a current unit quotation. Confirm the residence, availability and purchase terms independently of the insurance discussion.
Before committing, request the available condominium insurance documents, proposed owner insurance requirements and household-staff access procedures. Do not assume LILLI’s actual master-policy terms, owner requirements or staff-access rules. Ask which documents are preliminary and which terms will govern ownership once finalized.
For a buyer also considering Aria Reserve Miami, the same document discipline offers a useful comparison framework. Ask identical questions of each property; a shared neighborhood does not establish equivalent insurance obligations. Keep architectural preferences and policy findings in separate columns of the purchase review.
Start with a written description of the intended household. Will you directly employ a housekeeper, cook, nanny or companion? Will anyone work regularly rather than occasionally? Will duties include driving? These are questions for the insurance adviser, not details to defer until move-in.
Describe the actual arrangement without inferring coverage from a job title. A household role may involve several duties, and the adviser needs the complete picture to evaluate policy wording. If an agency is involved, ask who employs the individual and what protection applies. Do not infer the answer from the invoice.
Prepare a concise staffing brief covering duties, schedules, work locations and the proposed employment relationship. Have the appropriate payroll or legal adviser resolve employment-status questions. Then ask the insurance professional to evaluate the arrangement, including any changes anticipated after occupancy.
Florida generally does not require household employers to obtain workers’ compensation insurance for domestic employees in a private home. The absence of a general requirement, however, is not protection against a work-related injury.
Do not assume standard homeowners or condominium insurance fully covers household-employee injuries. Coverage depends on policy wording and applicable workers’ compensation requirements. Before directly employing staff, review residence-employee provisions, exclusions and whether separate workers’ compensation protection is appropriate.
Ask the adviser to distinguish coverage for an employee’s work-related injury from the owner’s other personal liability exposures. Request an explanation of what a proposed workers’ compensation policy or voluntary-compensation endorsement would cover, whether it is available for the arrangement and what it would leave uncovered. An endorsement’s name alone does not establish coverage.
This review is equally relevant if EDITION Edgewater is on the shortlist. The question follows the household’s employment arrangement, not the project’s name. Resolve it before staff begin work rather than relying on a general assurance that the residence is insured.
A personal umbrella policy provides additional liability limits above covered underlying policies after their applicable limits are exhausted. For a condominium owner, it can sit above condo-unit and personal-auto liability coverage. It does not replace those policies.
Umbrella insurers commonly require minimum underlying liability limits. Ask the adviser to compare the actual condo and auto limits with the umbrella’s requirements and identify any necessary adjustments before coverage begins. Review the policies together rather than treating the umbrella as an isolated purchase.
Additional limits do not mean every exposure is covered. Do not assume an umbrella automatically responds to household-employment claims or fills a gap created by another policy’s exclusion. Ask specifically how the proposed wording treats employee injuries and other household-employment exposures.
A residence’s purchase price does not establish a universal umbrella limit. Request a recommendation based on your circumstances and the policies being coordinated. The goal is a clear explanation of covered exposures, required underlying limits and remaining exclusions-not simply the largest headline number.
A condominium association’s umbrella addresses association liability. It is not a substitute for an owner’s personal umbrella. That distinction matters even when the building’s insurance program appears substantial.
Ask your adviser to review the association documents alongside the proposed unit-owner policy and personal umbrella. Have the adviser identify the relevant coverage boundaries rather than assuming an incident’s location determines which policy responds. For LILLI, obtain the actual applicable terms before drawing conclusions about protection.
A buyer weighing Villa Miami can use the same approach without presuming the two properties share coverage or operating rules. Compare each building’s documents in the context of the owner’s intended household arrangements. A polished service environment is not a substitute for contractual insurance protection.
Bring the purchase and household reviews together in one working file. Before occupancy, and before employees start, ask the relevant advisers to confirm:
The applicable association insurance documents and owner insurance requirements.
The intended staffing arrangement and the residence-employee provisions reviewed.
Whether separate workers’ compensation or other employee-related protection is appropriate.
The condo and auto liability limits required by the selected umbrella.
The effective dates, exclusions and unresolved coverage questions for each policy.
Revisit the file when staffing duties, vehicles or household arrangements change. The purpose is not to collect policies indiscriminately. It is to understand which protection addresses each exposure, where additional limits apply and where a separate solution may be needed.
For LILLI buyers, this is the quieter side of a well-considered acquisition: planning the home’s operation with the same care as its selection. Use this checklist as a discussion framework with licensed insurance professionals and, where employment questions arise, qualified legal or payroll advisers.
For a considered approach to your South Florida residence search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationLILLI is proposed at 717 NE 27th Street, Miami, FL 33137, overlooking Biscayne Bay in Edgewater.
Plans call for 53 stories and 117 residences in a tower approximately 636 feet tall. OKO Group is the developer, and Adrian Smith + Gordon Gill Architecture is the architect.
Indicative starting pricing in May 2026 was approximately $1.65 million. This is not a current unit quotation, so confirm availability and pricing directly.
Florida generally does not require household employers to obtain workers’ compensation insurance for domestic employees in a private home. Coverage may still be appropriate for work-related employee injuries.
Do not assume it does. Coverage depends on the policy’s residence-employee provisions, exclusions and applicable workers’ compensation requirements.
It adds liability limits above covered underlying policies after their applicable limits are exhausted. For a condo owner, those underlying policies can include condo-unit and personal-auto liability coverage.
No automatic coverage should be assumed. Ask the insurer or adviser to confirm how the proposed policy treats household-employment exposures and employee injuries.
Umbrella insurers commonly require minimum underlying liability limits. The condo and auto policies should be checked against the selected umbrella’s requirements.
No. An association’s umbrella addresses association liability and should not be treated as a substitute for an owner’s personal coverage.
Confirm the employment arrangement, residence-employee coverage, exclusions and whether separate workers’ compensation protection is appropriate. Also obtain applicable building staff-access rules rather than assuming them.