
A move from Abu Dhabi to Fisher Island calls for separate decisions about the residence, the source of closing funds, and contractual valuation protection. Cash strategy should sit alongside verified credit arrangements, precise appraisal deadlines, and a realistic ownership budget.
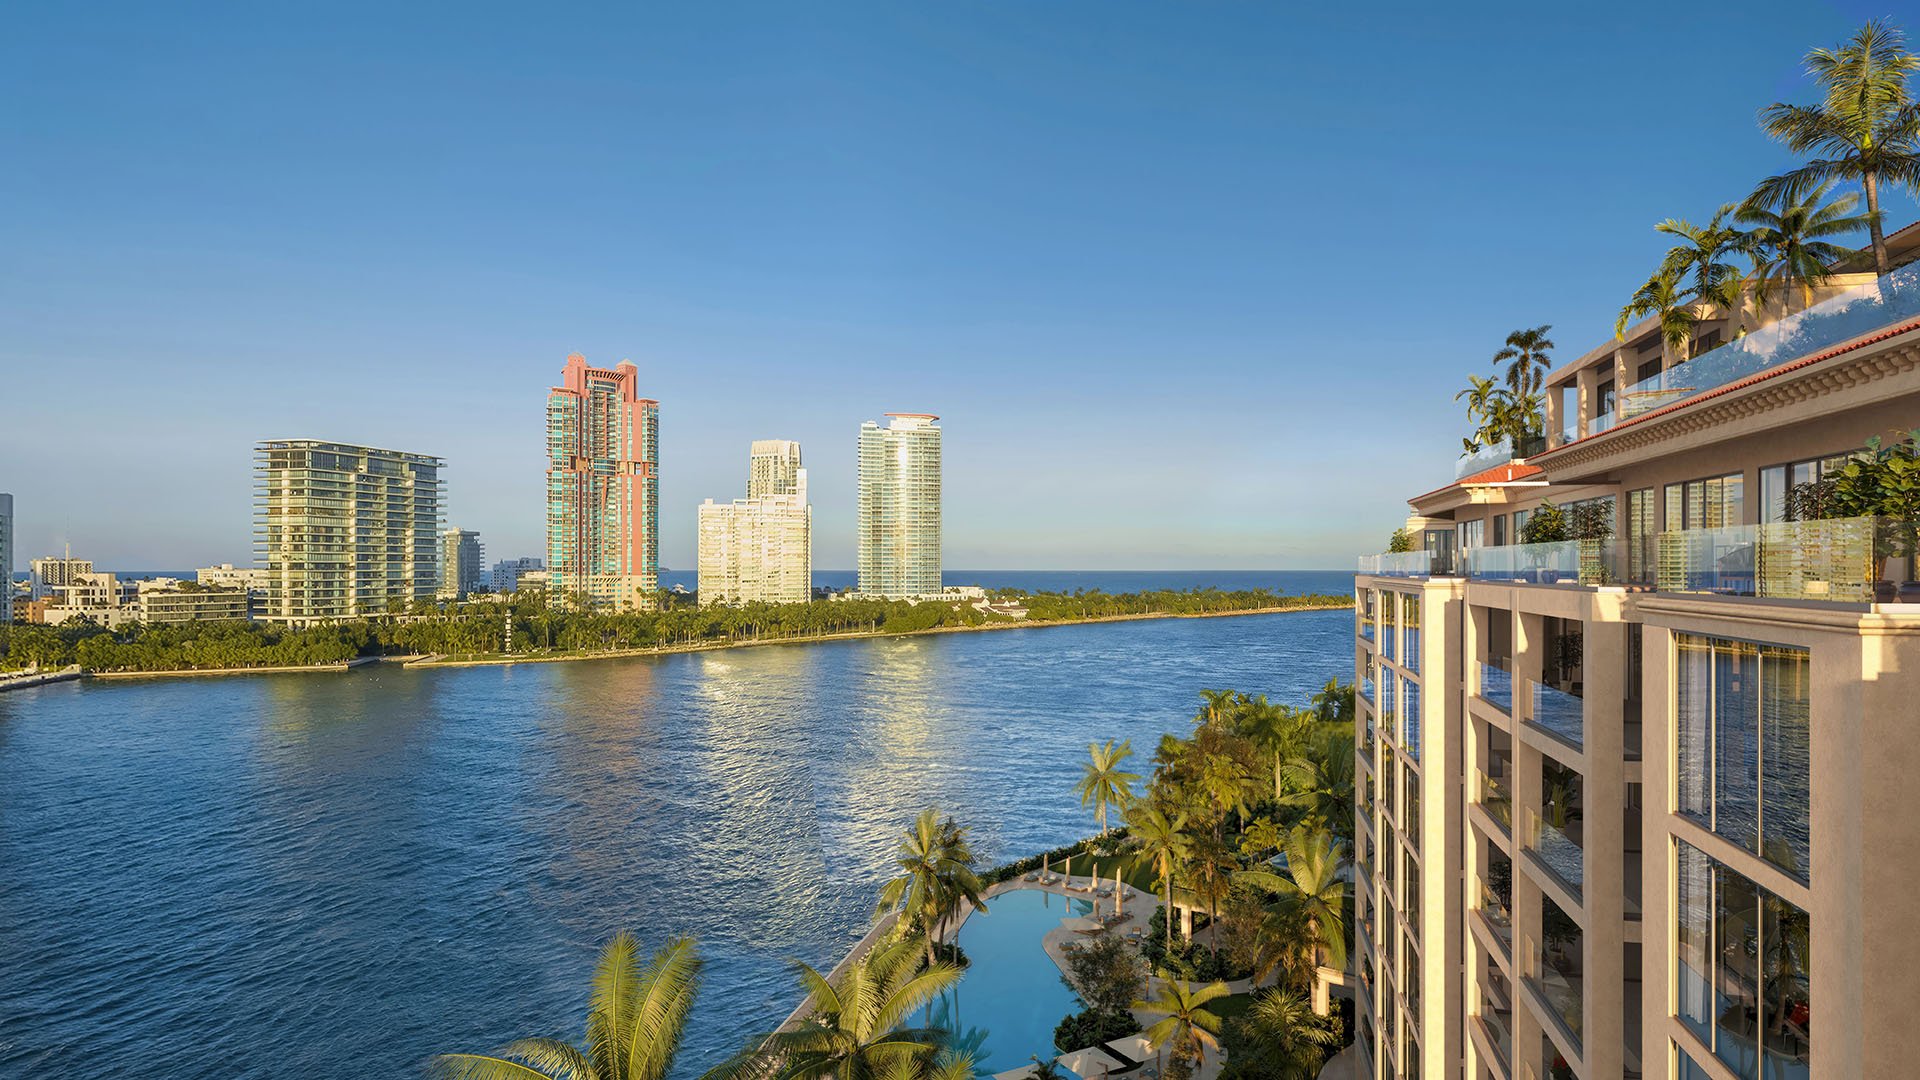
For a household planning a move from Abu Dhabi to Fisher Island, the property search should begin with three questions: Which residence suits the intended way of life? What funds will be available at closing? What contractual protection should apply if the valuation falls short? Keeping these decisions separate makes it easier to pursue a preferred home without confusing purchasing power with an obligation to proceed at any price.
A cash purchase removes mortgage underwriting and the mortgage lender’s appraisal requirement from the closing process. It does not require the buyer to forgo an independent valuation or a negotiated right to cancel. Likewise, an intention to use securities-backed credit is no substitute for a confirmed funding arrangement.
Whether the search begins with Palazzo del Sol or another island residence, establish the acquisition framework before allowing a particular property to set the financial agenda.
Fisher Island has no road connection to the mainland. Ferry access belongs in the relocation plan, not merely the viewing itinerary. Under the island’s 2022 association rules, ferry service is reserved for owners, members, and members’ permittees, with controlled access criteria for employees, guests, and visitors. Confirm current arrangements rather than treating those dated rules as a guarantee of present procedures.
Before scheduling a concentrated property tour, establish how access will work for the household and its advisers. Before committing to a move, clarify arrangements for guests, household employees, and service providers. Direct ferry-schedule inquiries to FICA Public Safety at 305-535-6022.
When considering Palazzo della Luna, pair the residence visit with a practical review of arrival arrangements and the household’s expected routine. The question is not simply whether island living appeals, but whether its access requirements fit the life being planned.
The strongest cash strategy documents how to complete the purchase while retaining the liquidity the household wants afterward. Set an acquisition ceiling and a separate reserve for ownership and relocation. Do not mistake the absence of a mortgage payment for a modest carrying budget.
Request current figures for building HOA charges, FICA assessments, and club costs, keeping each category distinct. Historical indications of annual FICA or community charges in the tens of thousands of dollars warrant investigation; they are not current quotations for a particular residence. Confirm which amounts apply to the proposed purchase and whether any categories overlap.
For The Residences at Six Fisher Island, the same discipline applies: obtain the relevant transaction documents and property-specific cost information rather than importing assumptions from another address. Build the cash budget around the proposed purchase, not the island’s reputation.
Discuss securities-backed credit with the buyer’s financial institution and transaction counsel before making it part of an offer strategy. Do not assume availability, borrowing terms, collateral treatment, or acceptance within a proposed cash-purchase structure.
Ask the institution to document the proposed amount, pricing, collateral requirements, conditions for accessing funds, repayment obligations, and circumstances in which those arrangements could change. Verify these provisions in the buyer’s own agreement rather than inferring universal terms from the product’s name.
Then ask counsel to align the funding arrangement with the purchase contract. What must be confirmed before signing? What happens if the intended funds are unavailable on the closing date? Does the contract protect the buyer in that circumstance? A private funding plan should not be assumed to create a contractual right to delay or cancel.
For the Abu Dhabi side of the move, obtain case-specific banking, immigration, cross-border tax, and transfer advice. The property decision should follow a confirmed execution plan, without presuming any particular UAE requirement or banking timetable.
An appraisal and an appraisal contingency serve different purposes. The valuation informs the buyer; the negotiated contract determines what the buyer may do with that information. Ordering an appraisal alone does not secure a termination right.
A cash buyer can negotiate a standalone appraisal contingency without making the purchase contingent on obtaining a mortgage. Addendum F, Appraisal Contingency, is one form mechanism for doing so. Counsel should confirm the form version, its suitability, and the language incorporated into the actual agreement.
Set the valuation threshold deliberately. In this form, a blank threshold field defaults to the purchase price, but the executed document should control the analysis. Review the deadline for obtaining the appraisal separately from the deadline and procedure for exercising any cancellation right.
If considering The Links Estates at Fisher Island, decide before making an offer how much valuation uncertainty is acceptable. That decision should guide the negotiated protection, not emerge only after the appraisal arrives.
For a financed purchase, the financing contingency discussed here ties appraisal protection to the lender’s satisfaction with the valuation, if an appraisal is required. A valuation below the contract price does not necessarily prevent loan approval. Financing-contingency protection and standalone appraisal protection are not interchangeable.
An appraisal rider can provide a termination right for an insufficient appraisal regardless of financing approval, subject to its terms and deadlines. If a financed purchase appraises below the agreed price, potential responses include contributing additional cash, seeking a renegotiation, or terminating where the contract permits. A lower valuation does not itself guarantee a price reduction.
Ask counsel to map each possible outcome before signing: whether the loan remains available, whether extra cash would be acceptable, and which notice must be delivered by which deadline. The objective is a clear decision process, not merely a reassuring label on the contract.
A move from Abu Dhabi should not automatically be planned on the assumption that the buyer will qualify for Florida’s homestead property-tax exemption. Eligibility requires qualifying title and permanent residence as of January 1; purchasing the property alone does not establish eligibility. The homestead property-tax exemption is also distinct from homestead creditor protection.
Before committing, bring together the residence-specific ownership budget, confirmed funding plan, negotiated appraisal language, and island-access arrangements. Decide whether the intended use is a permanent home or a second home, and obtain advice suited to that choice. A considered acquisition rests on understanding both the commitment at closing and the life that follows.
For a discreet conversation about aligning your Fisher Island search with these priorities, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationA cash purchase removes the mortgage lender’s appraisal requirement, but a buyer can still obtain an independent valuation and negotiate appraisal protection.
Yes. A buyer can negotiate a standalone appraisal contingency without making the purchase contingent on obtaining a mortgage.
Addendum F, Appraisal Contingency, is a form mechanism for adding standalone appraisal protection. Counsel should confirm the applicable version and negotiated terms.
No. Any cancellation right depends on the executed contract, including its valuation threshold, notice requirements, and deadlines.
Not necessarily. A low appraisal may leave loan approval intact, while a standalone appraisal rider can provide separate termination rights subject to its terms.
Potential responses include additional cash, renegotiation, or termination where the contract permits. A low appraisal does not guarantee a seller will reduce the price.
Obtain written confirmation of the proposed institution-specific terms and access to funds. Have counsel review how the arrangement fits the purchase contract rather than assuming it qualifies for a particular cash-offer structure.
Review building HOA charges, FICA assessments, and club costs separately. Obtain current property-specific figures rather than relying on historical community estimates.
Fisher Island has no road connection to the mainland, so confirm current ferry and access arrangements for the household, guests, and service providers. FICA Public Safety handles ferry-schedule inquiries at 305-535-6022.
No. Florida’s exemption requires qualifying title and permanent residence as of January 1; ownership alone is insufficient.