A Melbourne-to-West Palm Beach move calls for more than a purchase-price comparison. Understand the post-purchase assessment reset, homestead eligibility, Florida portability and the carrying-cost implications of your intended resale date.
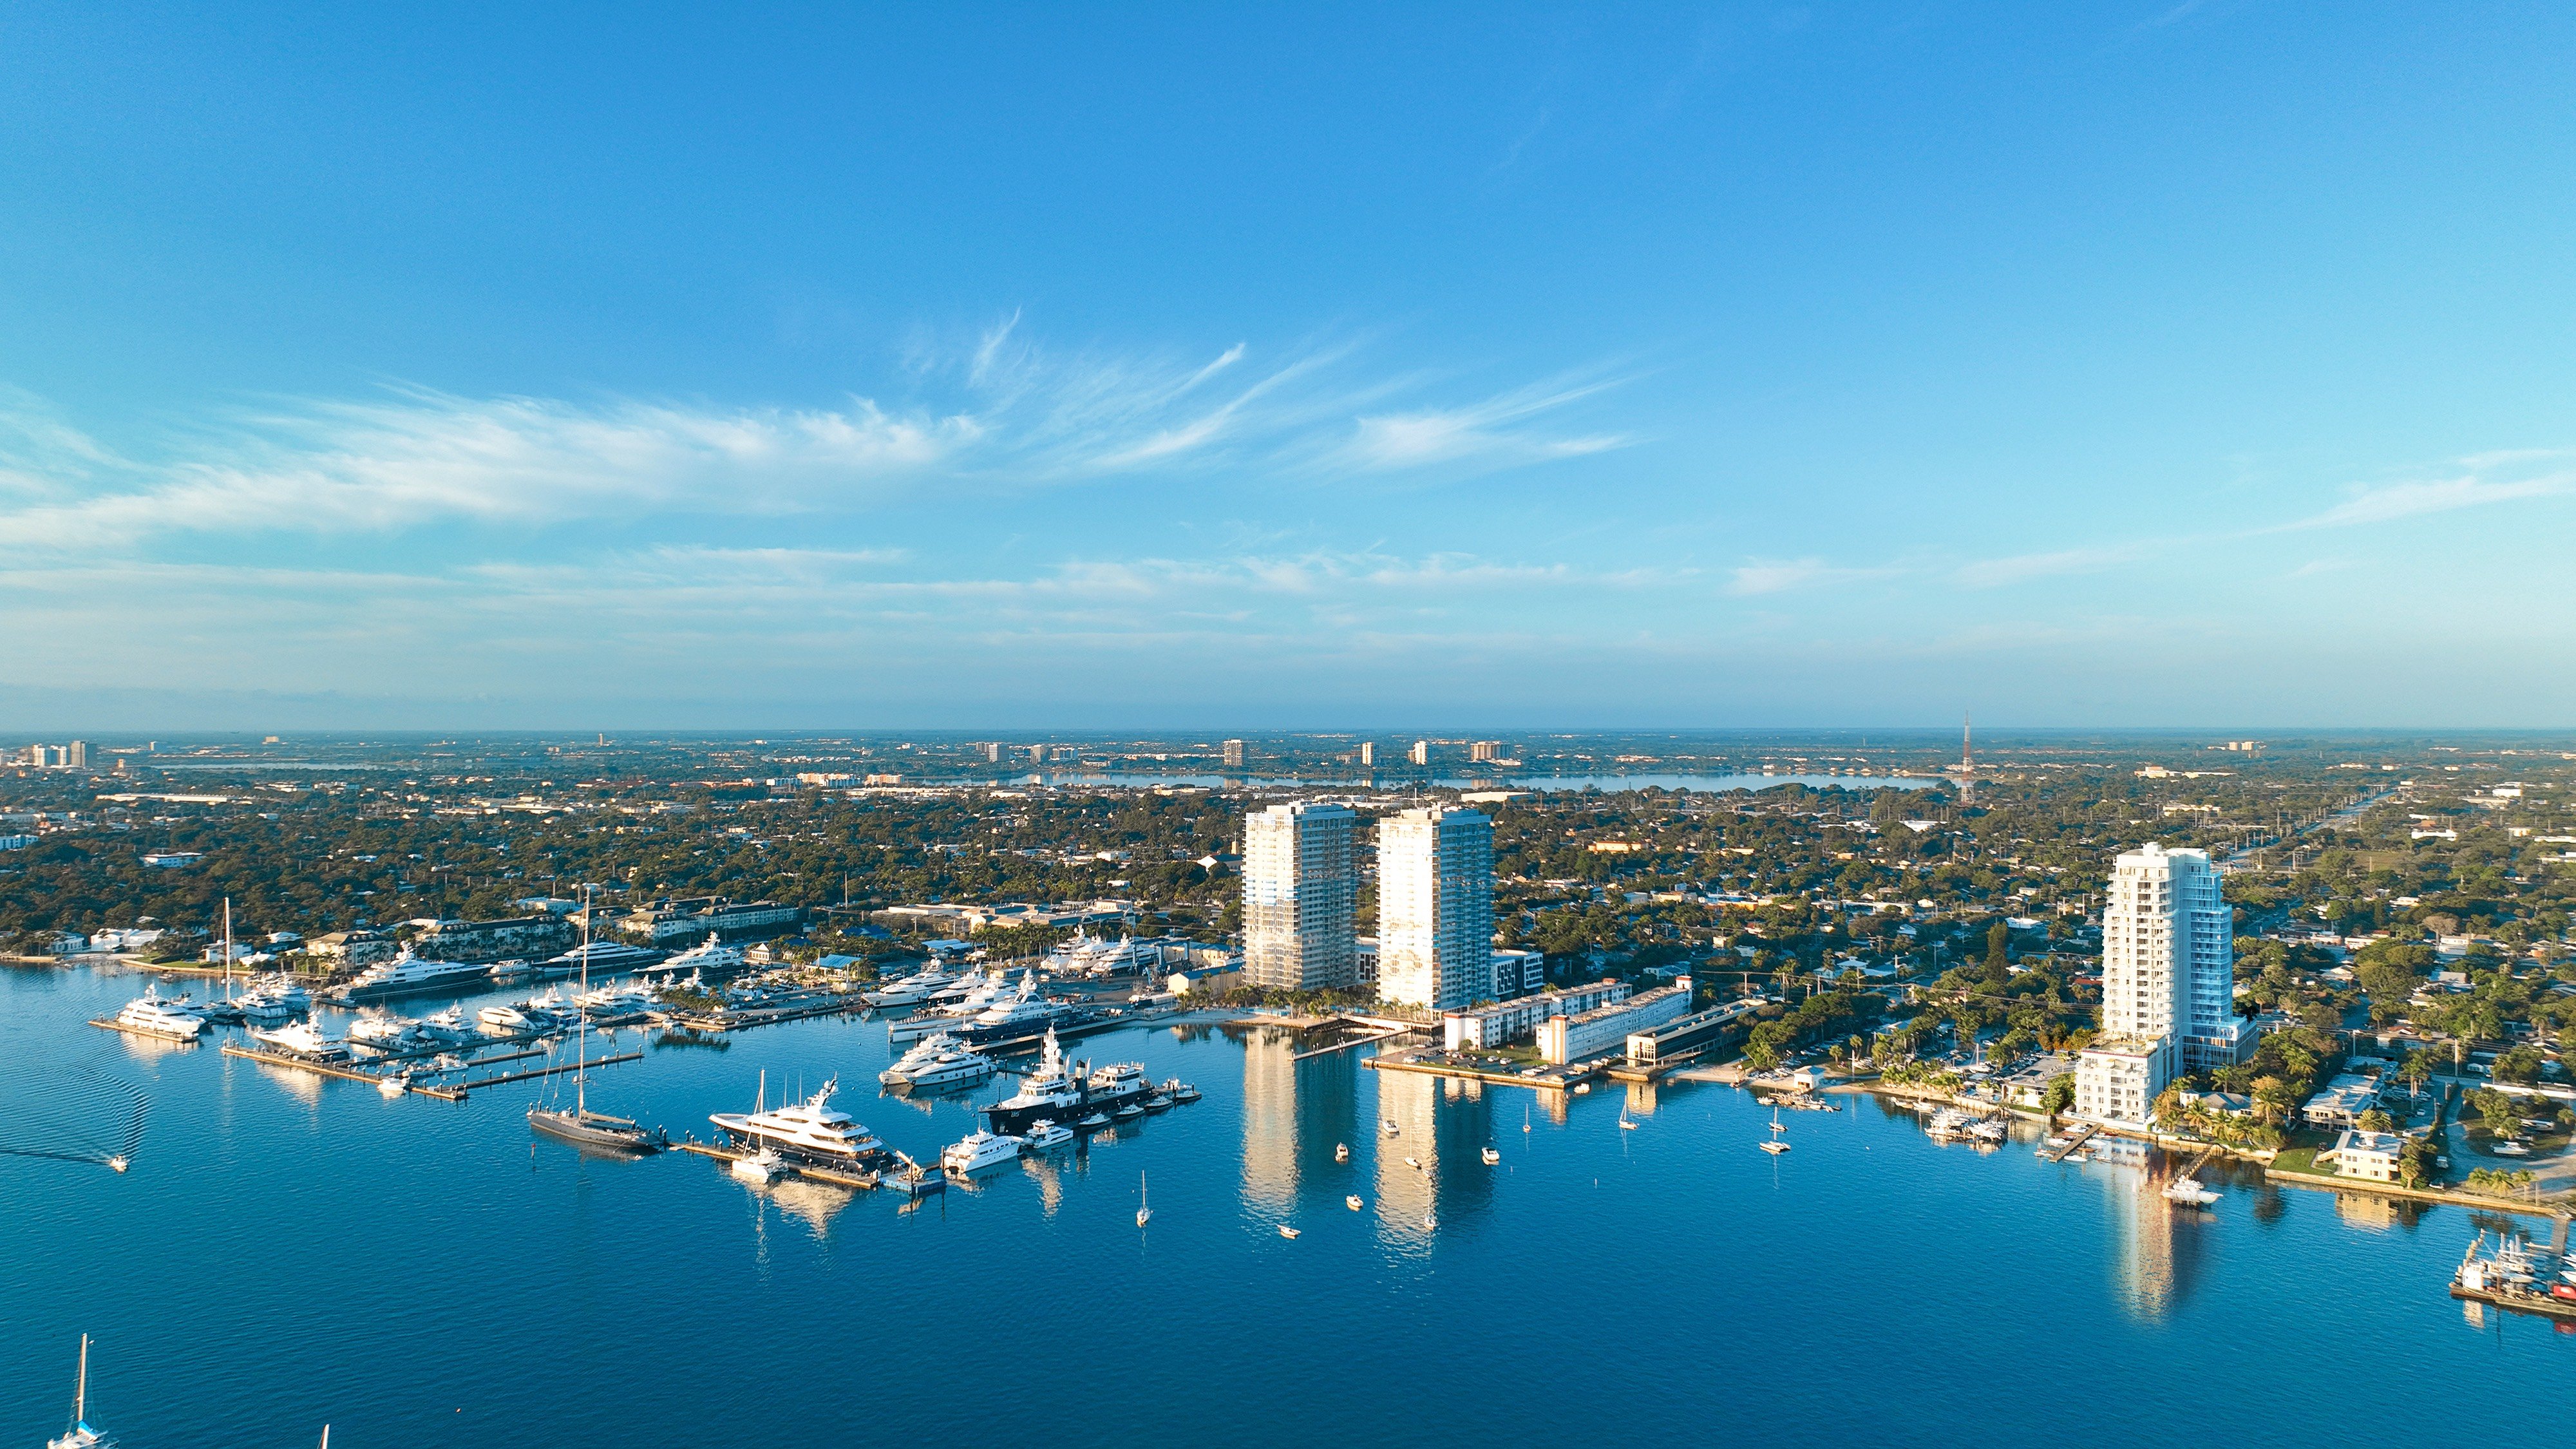
A move to West Palm Beach is a residential decision with a tax calendar attached. Beyond the residence itself, the questions are when it becomes your permanent home, which assessment protections you qualify for and how long you expect to own it. Those answers belong beside the purchase price-not in a file opened after closing.
First, clarify the departure point. Melbourne, Florida, may bring an existing Florida homestead history and potential Save Our Homes portability. A home in Melbourne, Australia, does not itself create those benefits. The relevant distinction is an eligible previous Florida homestead, not simply ownership elsewhere.
For a buyer considering Alba West Palm Beach, that distinction should shape the ownership budget before a particular residence is selected. Two purchasers considering the same property can face different assessment outcomes because their eligibility histories differ.
The seller’s tax bill reflects the seller’s circumstances. It is not a reliable forecast of yours. A purchase generally triggers reassessment at just value in the following tax year, so a long-held property’s capped assessment should not anchor your recurring-expense projection.
Separate that purchase reset from subsequent annual assessment caps. The first post-purchase reassessment can exceed the seller’s assessment by more than 10%. Treating the nonhomestead cap as protection against that reset is a consequential budgeting mistake.
Build the comparison around the anticipated post-purchase assessment, your own exemptions and any eligible portability. Request a property-specific estimate rather than extrapolating from a listing’s historical taxes. Keep the acquisition-year calculation distinct from the following tax year and later ownership years. That separation helps you evaluate an apparently modest tax expense without mistaking the seller’s assessment history for a durable saving.
Homestead is not automatic at closing. Eligibility generally requires ownership and use as a permanent residence on January 1, with an application due March 1 of the tax year claimed. A closing date alone does not establish both requirements.
If your relocation schedule misses January 1 eligibility, the exemption and Save Our Homes protection can be delayed. Before committing, align three dates: acquisition, actual permanent occupancy and the applicable filing deadline. For a phased move, model the interval before qualification rather than assuming homestead treatment begins when you receive the keys.
The first $25,000 of homestead exemption applies to all property-tax levies, including school taxes. The additional exemption excludes school taxes. Neither supports a universal dollar-savings estimate across properties.
When assessing Forté on Flagler West Palm Beach, keep the residence decision separate from the eligibility decision. Confirm your purchase and occupancy timetable rather than treating a preferred move date as proof of qualification.
Save Our Homes limits annual increases in a qualifying homestead’s assessed value to the lower of 3% or the applicable CPI change. The 2.9% cap for 2025 was a year-specific figure, not a permanent planning rate.
Nonhomestead property generally has a 10% annual assessment-growth cap-a substantially looser constraint. That does not mean assessments necessarily rise 10% every year, nor should the protection be assumed to apply uniformly to every levy.
Most importantly, both rules concern assessment growth, not the percentage increase in the final tax bill. Neither guarantees a ceiling on annual tax expense. A useful projection keeps assessment assumptions separate from the calculation of taxes due, rather than simply increasing last year’s bill by 3% or 10%.
For an eligible move from a previous Florida homestead, portability can transfer up to $500,000 of Save Our Homes assessment difference. That difference is the gap between the previous property’s just value and capped assessed value. It is not a cash credit, and it does not transfer the old tax bill.
Eligibility generally requires having received homestead exemption on the previous property on January 1 of one of the three preceding tax years. The new home needs its own homestead application, plus a portability application using Form DR-501T. The exemption itself does not transfer.
Moving to a higher-value homestead generally allows an eligible owner to transfer the assessment difference up to the statutory limit. Moving to a lower-value home generally produces a proportional transfer. Do not budget for a smaller purchase on the assumption that the entire previous difference follows unchanged.
Obtain the prior home’s just value, capped assessed value and qualifying homestead years before assigning a portability benefit to the next purchase.
A disciplined comparison uses the same intended holding period for three distinct scenarios. This is particularly useful when a shortlist includes Mr. C Residences West Palm Beach and the household has not decided whether the move will be immediate or phased.
Homestead in the first eligible tax year, with eligible portability.
Model the purchase reset, the confirmed portable assessment difference and applicable homestead treatment. Do not carry forward the seller’s assessment or assume the maximum portability amount.
Delayed homestead.
Account for the period before qualification, then distinguish the later homestead years. This reveals the carrying-cost consequence of a schedule that misses January 1 eligibility.
Permanent nonhomestead ownership.
Model the purchase reset and the generally applicable nonhomestead assessment-growth framework without adding homestead benefits. Use 10% as a cap where applicable, not as a forecast or universal tax-bill limit.
Compare cumulative property taxes across the intended ownership period, not merely the first annual figure. Keep that tax comparison within a separate, complete ownership budget.
Accumulated Save Our Homes protection is principally an ownership-period carrying-cost benefit. On a later sale, it generally does not pass to the purchaser, who faces a new assessment baseline and must establish independent eligibility. A favorable tax history cannot be promised as the next owner’s assessment advantage.
For a residence at Shorecrest Flagler Drive West Palm Beach, apply the same discipline to the eventual exit analysis: separate your projected costs from those a future buyer may face. Your protected assessment is no substitute for evaluating that buyer’s likely ownership budget.
These rules establish no universal three-, five- or ten-year resale deadline. Compare your intended exit with an earlier and a later alternative, calculating cumulative tax carry for each scenario. The right residence should remain a considered choice even if the relocation or resale calendar shifts.
For a considered West Palm Beach property search aligned with your relocation and ownership horizon, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Portability depends on an eligible previous Florida homestead; ownership in Melbourne, Australia, does not itself generate Save Our Homes benefits.
Not reliably. A purchase generally triggers reassessment at just value in the following tax year, so the seller’s capped assessment may not reflect your future baseline.
Eligibility generally requires ownership and use as a permanent residence on January 1. The application is generally due March 1 of the tax year claimed.
Homestead exemption and Save Our Homes protection can be delayed. Model the period before qualification separately from later homestead years.
For a qualifying homestead, annual assessed-value increases are limited to the lower of 3% or the applicable CPI change. This is not a ceiling on the final tax bill’s percentage increase.
No. The general 10% cap concerns annual assessment growth, does not prevent the purchase reset and should not be assumed to apply uniformly to every levy.
Eligible owners can transfer up to $500,000 of the difference between a previous Florida homestead’s just value and capped assessed value. It is not a cash credit or a transfer of the prior tax bill.
The new home requires its own homestead application and Form DR-501T for portability. Eligibility generally requires prior homestead exemption on January 1 of one of the three preceding tax years.
Not necessarily. Moving to a lower-value homestead generally produces a proportional transfer, while moving to a higher-value home generally allows transfer up to the statutory limit.
These rules do not establish a universal optimal resale deadline. Compare cumulative carrying costs over your intended holding period, recognizing that your accumulated assessment protection generally does not pass to the buyer.