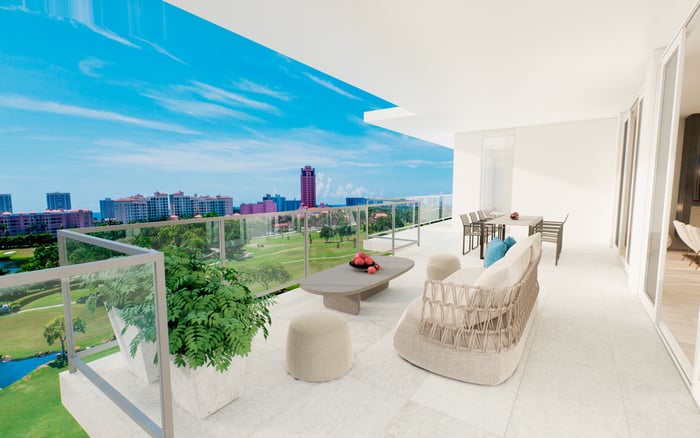
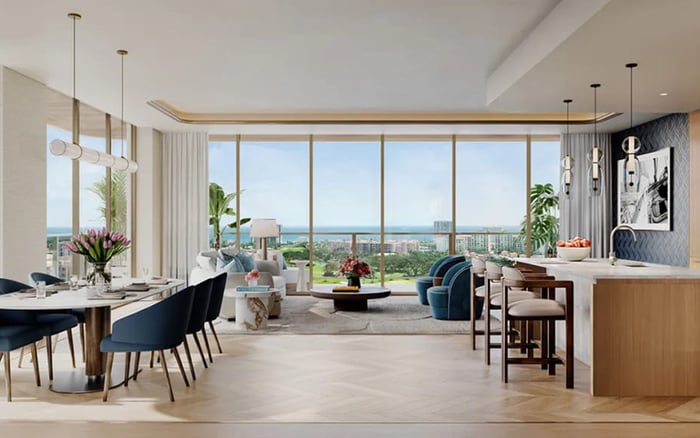
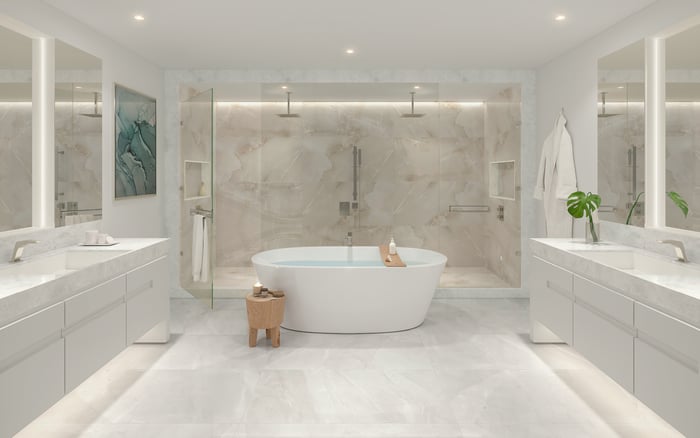
A discreet buyer-side framework for reviewing a Glass House Boca Raton acquisition, separating family-office authority, funding documentation, contract exposure, and independently verified wire instructions.
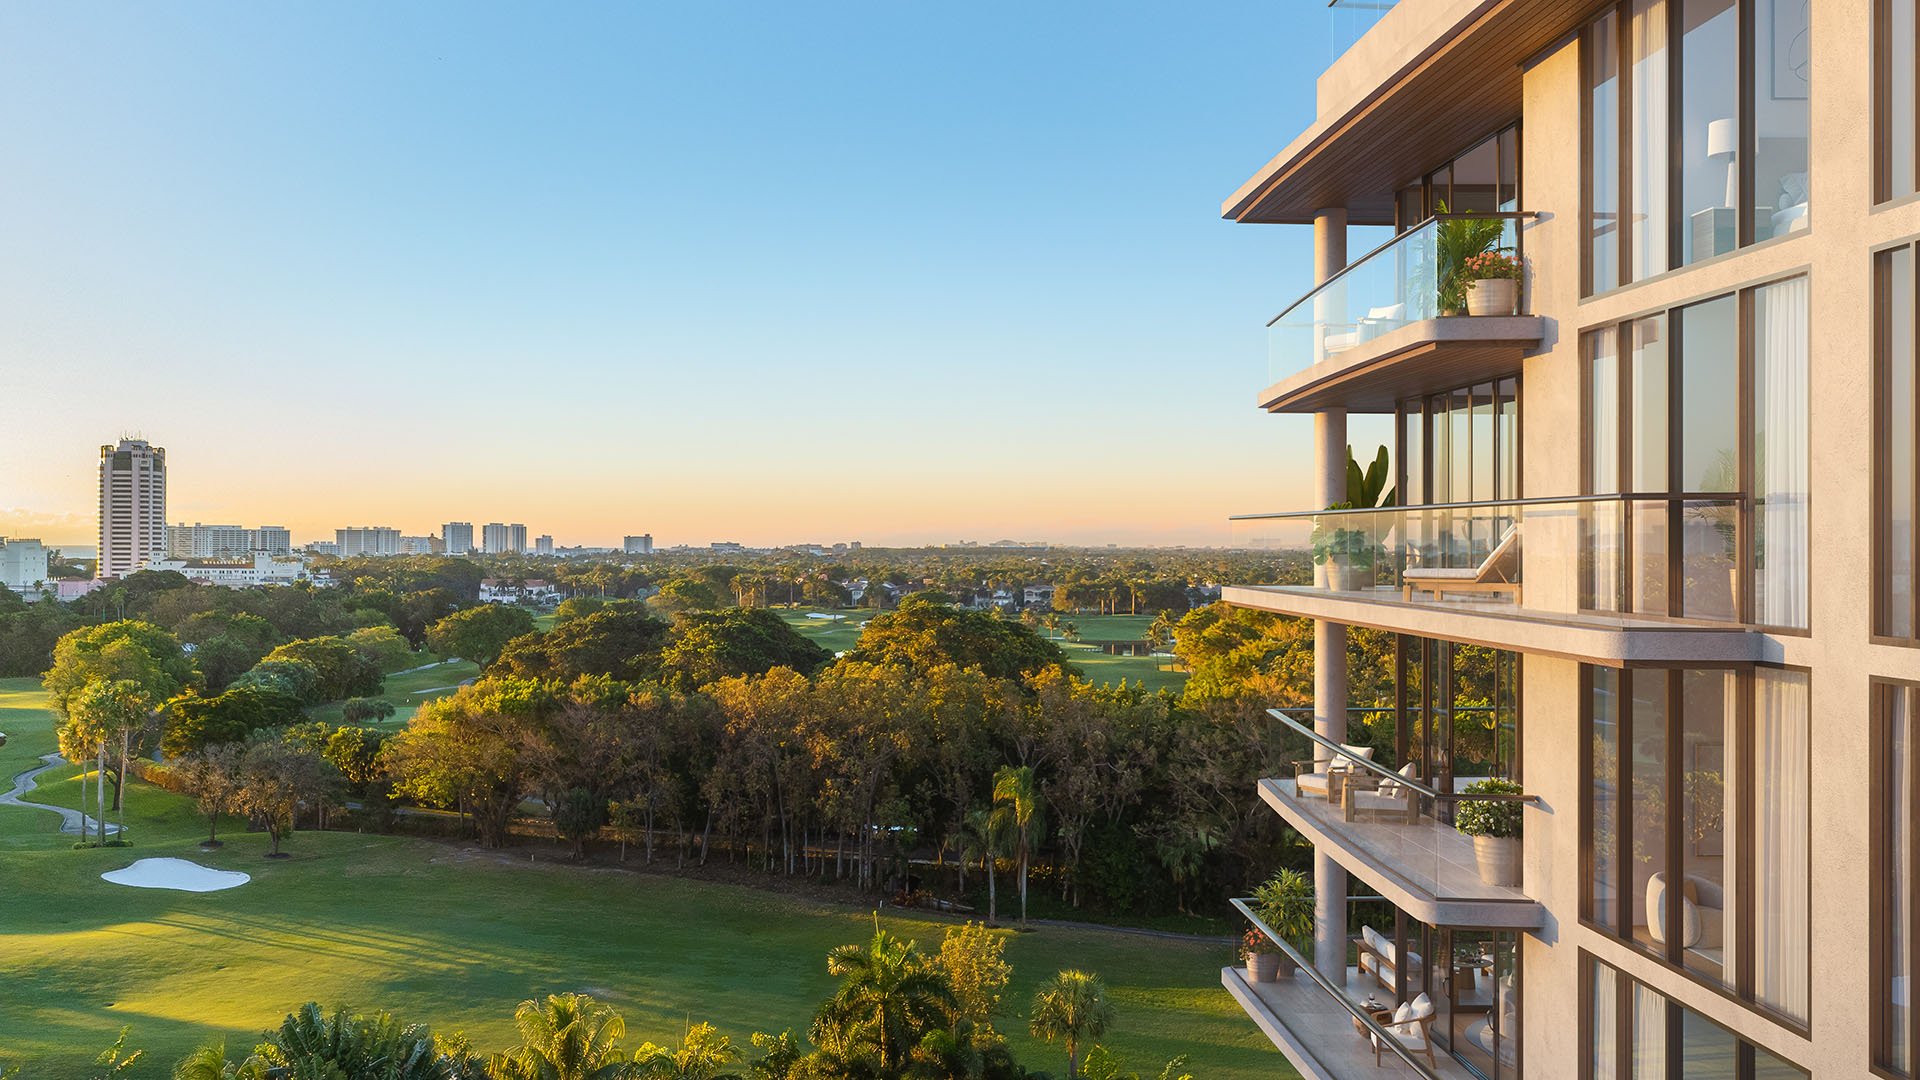
At Glass House Boca Raton, the appeal begins with a limited collection of 28 luxury residences in downtown Boca Raton. Advertised pricing ranges from $2.7 million to more than $8 million. These figures reflect marketing expectations, not verified transaction prices. For a family office, the purchase warrants a separate assessment of who may commit capital, how funds will move, and what must be confirmed before a deposit leaves the bank.
The objective is not to complicate a residential acquisition. It is to prevent enthusiasm for the property from becoming authorization for an unverified payment. The controls below are proposed buyer-side practices, not established Glass House policies or statements of legal requirements. Nothing here alleges fraud or misconduct by the project.
Start by distinguishing the development site at 280 E. Palmetto Park Road from the sales gallery at 221 E. Palmetto Park Road. The developer has been identified as 280 E. Palmetto Park Road LLC. These details belong in the acquisition file, but none independently authenticates a deposit recipient or bank account.
A useful family-office authority matrix separates three decisions: approving the acquisition, executing the contract, and releasing money. Assign a named decision-maker and a designated backup to each. Counsel should review the purchaser's governing documents to determine who can bind the intended entity or trust.
The investment approval memorandum should identify the residence under consideration, intended purchaser, agreed price, anticipated deposit obligations, funding plan, and unresolved conditions. Avoid a broad instruction such as “proceed with the purchase” when the office intends to approve only negotiations or contract review.
For payment control, consider separating the person preparing the transfer from the person authorizing its release. Neither should treat a principal's approval of the residence as confirmation of banking details. Record what was approved, by whom, and against which document version.
For a buyer also considering Alina Residences Boca Raton, the same internal approval template can support consistent evaluation. Carry the template between opportunities-not assumptions about another project's contract or payment arrangements.
A source-of-funds file should answer a practical question: how does the money proposed for this purchase connect to the purchaser? Before circulating sensitive records, agree with counsel, the bank, and the relevant transaction professionals on what documentation is needed.
As a proposed preparation checklist, consider:
The purchaser's legal name and relevant entity or trust authority documents.
Identification and ownership information requested by verified counterparties.
Evidence identifying the account expected to remit the deposit.
Documents explaining the origin of the purchase funds, where requested.
A written explanation of any difference between purchaser and account-holder names.
These are preparation categories, not a Glass House-specific checklist. A family office should not assume that every item must be supplied, that the list is exhaustive, or that acceptance by one participant satisfies every other participant.
If funds will move through multiple family-controlled accounts, map the route before initiating transfers. Ask counsel and the receiving party to address any proposed third-party remittance rather than improvising near a deadline. Maintain a controlled record of which documents were delivered, to whom, and through which verified channel.
Discretion matters here. Prefer a verified secure delivery method and limit access to people with a transaction role. A plausible email requesting additional financial records warrants authentication just as a payment request does.
Glass House celebrated its official groundbreaking on April 3, 2025. As of March 10, 2026, a $70 million construction loan had been publicly disclosed for vertical construction, with completion anticipated in 2027. That timetable is an estimate, not evidence of a contractual delivery guarantee.
These milestones provide useful context, but they do not establish the buyer's escrow-release terms, refund rights, or remedies. Ask counsel to explain the actual agreement: when deposits are due, who holds them, whether and under what conditions they may be released, and what happens if contractual deadlines change.
Review construction financing and purchaser protection separately. The existence of a loan does not authenticate an emailed payment demand. Likewise, a sales-gallery conversation should not substitute for a review of the documents governing the buyer's obligations.
If the shortlist includes The Residences at Mandarin Oriental Boca Raton, assess those contractual questions independently. A disciplined comparison focuses on each agreement rather than assuming comparable protections across Boca Raton residences.
Business-email compromise involves criminals taking over or spoofing legitimate business email accounts to redirect money. A familiar conversation is not proof that payment instructions are genuine.
Adopt a verification sequence before the first deposit:
Establish the authorized recipient and independently verified contact details before payment day.
Obtain instructions through an agreed channel and reconcile the recipient with the transaction documents.
Call a previously verified number, not one supplied in the payment email, to confirm the beneficiary and banking details.
Require a second authorized person to review the payment and verification record before release.
Confirm receipt through the established contact and retain the bank confirmation.
Treat any change in bank, account, beneficiary, or delivery method as a reason to pause and repeat verification. Urgency should not override the process. A polished signature block, recognizable logo, or accurate purchase amount should not replace independent authentication.
Document the circumstances that require escalation: an unexplained account-name mismatch, changed instructions, an unavailable verified contact, unclear signing authority, or unresolved contract language affecting the payment. Designate someone to hold the transfer while counsel and the bank address the issue.
If a suspicious transfer has already been sent, contact the sending bank immediately through a trusted channel to request its fraud-response process and a possible recall. Preserve the communications and alert counsel. Do not assume recovery is assured.
Before releasing funds, assemble a single decision record containing the approved transaction terms, signing authority, funding-file status, relevant contract review, verified payment instructions, and independent release approval. Keep unresolved questions visible rather than scattered across correspondence.
For a family office, the strongest purchase process preserves both decisiveness and restraint: approve the residence on its merits, then authorize the money on separately verified evidence.
For a discreet perspective on Boca Raton residences and your next acquisition, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationGlass House Boca Raton is marketed as a limited collection of 28 luxury residences in downtown Boca Raton.
Advertised residence prices range from $2.7 million to more than $8 million. These are marketing prices, not verified transaction prices.
No; the development site is 280 E. Palmetto Park Road, while the sales gallery is at 221 E. Palmetto Park Road, Boca Raton.
Completion was anticipated in 2027 as of March 2026, but that estimate does not establish a contractual delivery guarantee. Buyers should have counsel review the agreement's deadlines and remedies.
No; the $70 million construction loan does not establish purchaser escrow-release terms, refund rights, or the authenticity of payment instructions.
No; they are proposed buyer-side diligence practices, not established project policies or statements of legal requirements.
It should distinguish acquisition approval, contract-signing authority, and payment-release authority. Each decision should have an identified responsible person and a documented scope.
Proposed categories include purchaser identity, relevant authority documents, remitting-account information, and requested evidence explaining the funds' origin. Confirm actual requirements with verified transaction professionals before sharing sensitive records.
Confirm the beneficiary and banking details through a previously verified phone number rather than contact details supplied in the payment email. Use an independent second review before releasing the transfer.
Pause the payment and repeat independent verification. If a suspicious transfer has already been sent, contact the sending bank immediately, preserve communications, and alert counsel.