A discreet planning framework for a Milan-to-Bay Harbor Islands move, separating Florida domicile from tax residence and aligning travel calendars, housing decisions, and household records.
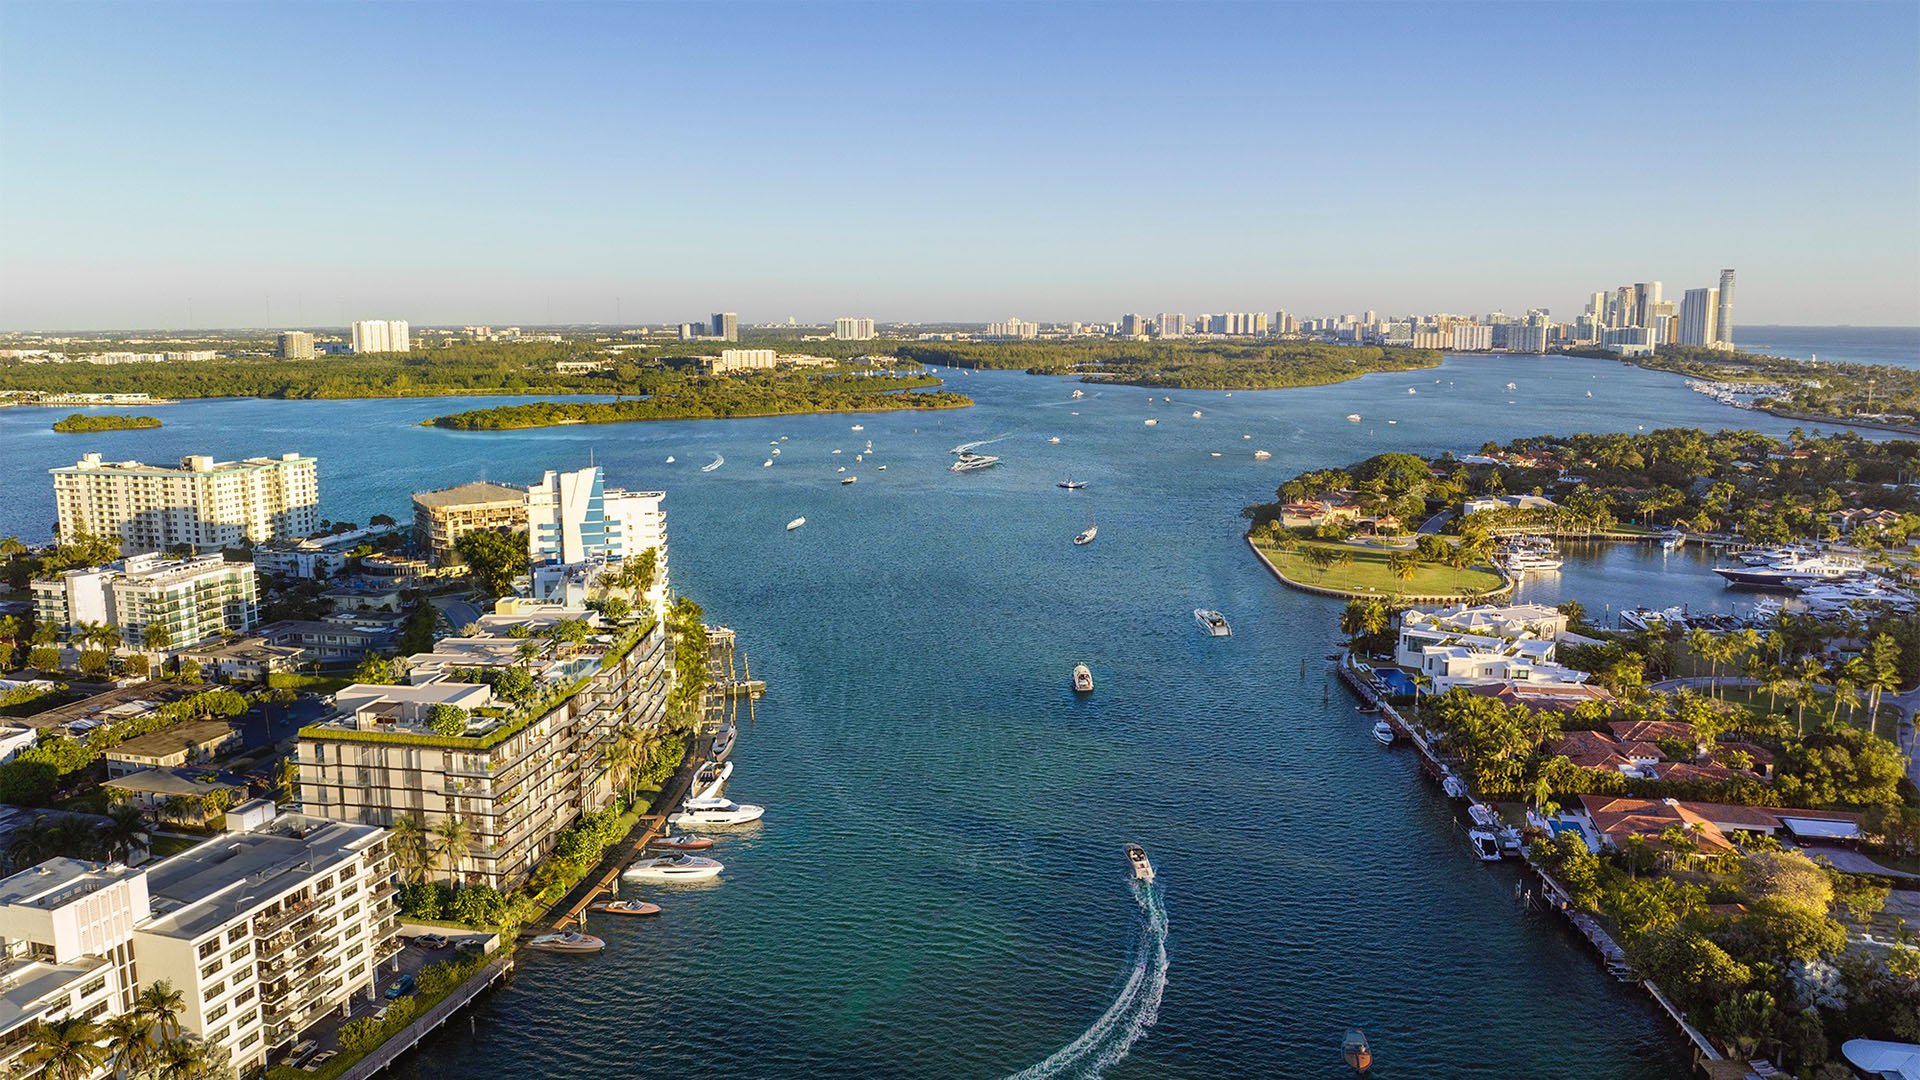
Rebasing from Milan to Bay Harbor Islands is more than an acquisition. For a household whose business, family, and possessions span countries, the central question is whether Florida has genuinely become its permanent home. The residence should support that decision; the calendar and documentary record should reflect it accurately.
Florida domicile does not generally require 183 days in the state. The governing concept is a true, fixed, and permanent home and principal establishment. Travel days still matter. But Florida domicile, another state's residency rules, and international tax residence are separate questions-not interchangeable labels.
A buyer considering Alana Bay Harbor Islands should therefore begin with intended use: a principal household base, a seasonal residence, or a property whose role will evolve. The purchase alone cannot answer the residency question.
Ask advisers to prepare a short decision sheet distinguishing the following:
Florida domicile: Has Florida become the household member's permanent home?
Other state residence: Could another state's statutory-residence or day-count rules still apply?
U.S. federal tax residence: How do citizenship, green-card status, and substantial presence apply to the individual?
Italian domestic residence: What do the applicable Italian rules mean for the person's circumstances?
Treaty residence: If both countries treat the individual as resident under domestic law, does the treaty resolve that overlap?
Florida's residency requirements are also program-specific. Domicile should not be treated as automatic eligibility for homestead treatment, in-state tuition, or another benefit.
The objective is a coordinated analysis, not a single number circulated among the household's advisers. A Florida conclusion does not displace another jurisdiction's inquiry, and treaty criteria do not replace Italy's domestic residency rules.
Maintain a full-tax-year ledger with distinct categories for Florida, other U.S. locations, Italy, and third countries. This is a recordkeeping recommendation, not a prescribed legal counting formula.
For each journey, record departure and arrival dates, local times, locations, and supporting travel records. Distinguish planned travel from completed travel. A revised itinerary should not leave the master calendar describing a trip that never occurred.
Do not apply a universal rule to partial days, overnight flights, or airport transit. Have advisers determine how each relevant jurisdiction treats those facts. The same itinerary may require different calculations for different legal purposes.
A useful household workflow is to:
Designate one person to maintain the factual ledger.
Retain supporting records alongside each journey.
Reconcile actual travel regularly rather than reconstructing it at year-end.
Flag changed plans for adviser review before relying on an earlier calculation.
Record locations accurately, even within Florida. A stay in Miami Beach should not be recorded as a night at the Bay Harbor Islands residence simply because both are in the same state.
For Florida homestead purposes, no single factor conclusively establishes or disproves permanent residence. A formal Declaration of Domicile can be relevant, but it remains one element of a broader factual picture.
Review driver's-license and vehicle-registration records, banking addresses, official correspondence, family location, and employment connections. Voter registration may also support the record, but it is appropriate only for eligible voters-not a universal relocation task.
Compare these materials with tax filings and estate documents for consistency. The purpose is not to make every document identical regardless of its function, but to identify unexplained contradictions and ensure that each statement reflects actual circumstances.
For a purchaser evaluating Bay Harbor Towers, the key distinction is between owning a residence and making it the principal home. Record actual use and relevant changes over time. Neither the property name nor a declaration substitutes for the household's underlying facts.
The Milan residence deserves its own factual review. Record whether it remains available for personal use, has been sold, or is genuinely leased. Retaining Italian property does not automatically determine tax residence, but an available home is material to the treaty analysis.
For an individual resident in both countries under their domestic laws, the U.S.-Italy income-tax treaty's residence analysis begins with where a permanent home is available. If a home is available in both countries, the next question is where the individual's personal and economic relations are closer-the center of vital interests.
If those tests do not resolve the issue, the sequence proceeds to habitual abode, nationality, and ultimately agreement between the competent authorities.
Do not reduce this analysis to which home is larger, more valuable, or newly purchased. Document availability and actual personal and economic connections. A purchase in Bay Harbor Islands does not, by itself, neutralize an available Milan home.
A credible relocation plan should describe ordinary life, not just arrival dates. Where will family members live? Where will work be conducted? Which banking relationships and official addresses will remain, and why?
These questions belong beside the property brief. When considering The Well Bay Harbor Islands, define the residence's intended role in the household calendar. Do not assume that choosing a particular building carries any residency advantage.
Family members may have different travel patterns or legal circumstances. Have advisers assess each person rather than applying one household conclusion to every individual. The resulting records should explain genuine differences, not conceal them.
Treaty residence is not a blanket exemption from U.S. tax. Qualifying treatment as a foreign-country treaty resident can affect U.S. income-tax calculations, including nonresident-alien treatment where applicable. Saving-clause provisions can nevertheless preserve U.S. taxing rights, particularly for U.S. citizens.
Likewise, living abroad does not itself remove applicable U.S. filing obligations for citizens and resident aliens. Florida domicile and federal tax residence require separate attention throughout the move.
Before relying on a position, ask the advisory team to reconcile the travel ledger, housing availability, personal and economic connections, and proposed filings. Resolve contradictions through the facts, not cosmetic address changes. This checklist is a planning framework, not individualized legal or tax advice.
The most persuasive relocation record is also the simplest to understand: the home, the household's movements, and its documents describe the same life.
For a considered approach to selecting your Bay Harbor Islands residence, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNot generally. Florida domicile concerns whether the state has become the person's permanent home, while other jurisdictions may apply separate day-count rules.
A purchase alone does not establish that Florida has become the permanent home. Actual use, personal circumstances, and supporting records remain important.
Yes. Claiming Florida domicile does not eliminate another state's residency analysis or applicable statutory-residence rules.
Record a full tax year of locations, arrival and departure dates and times, and supporting travel records. Separate Florida, other U.S. locations, Italy, and third countries.
No universal counting method should be assumed. Advisers should assign the appropriate treatment under each applicable jurisdiction's rules.
No. It is one factor, and no single factor conclusively establishes or disproves permanent residence for Florida homestead purposes.
Review licenses, vehicle records, banking and official addresses, family location, employment, tax filings, and estate documents. Voter registration is relevant only for eligible voters.
No. Its availability is a material treaty-residence fact, but the applicable domestic rules and the broader circumstances require separate analysis.
The sequence considers permanent-home availability, center of vital interests, habitual abode, nationality, and ultimately competent-authority agreement. Later tests apply when earlier tests do not resolve residence.
Not automatically. Qualifying treaty treatment can affect income-tax calculations, but saving-clause provisions can preserve U.S. taxing rights, particularly for citizens, and filing obligations require review.