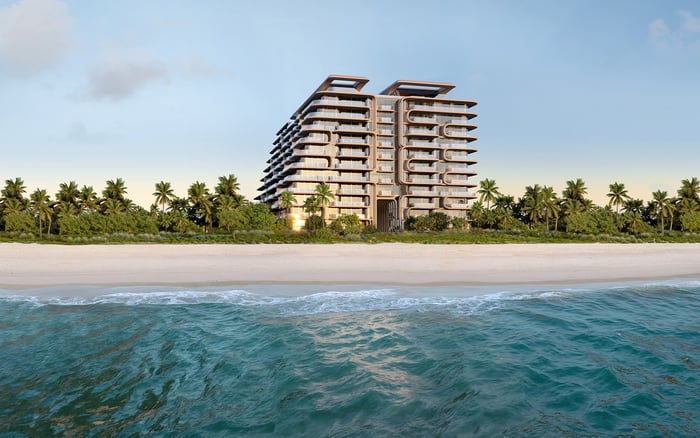
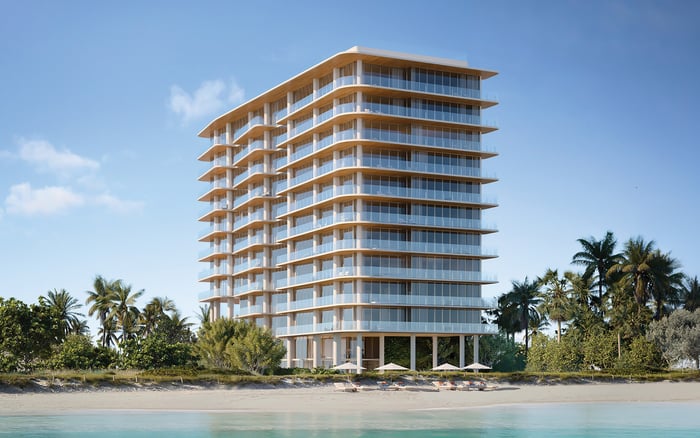
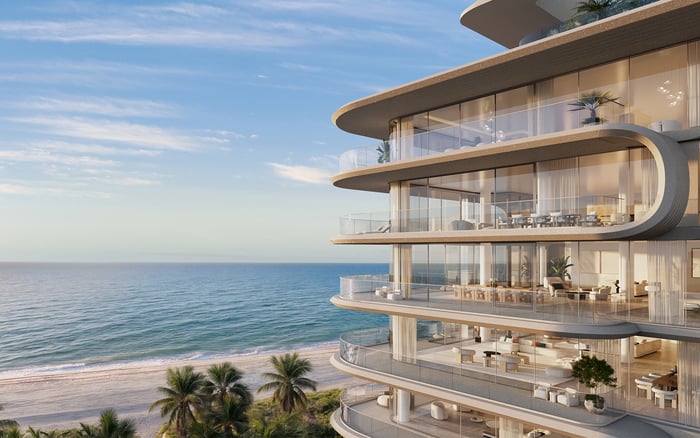
A buyer-focused guide to separating The Delmore’s purchase installments from move-in arrangements, securing written vendor-insurance requirements, and clarifying any refundable damage deposit before deliveries begin.
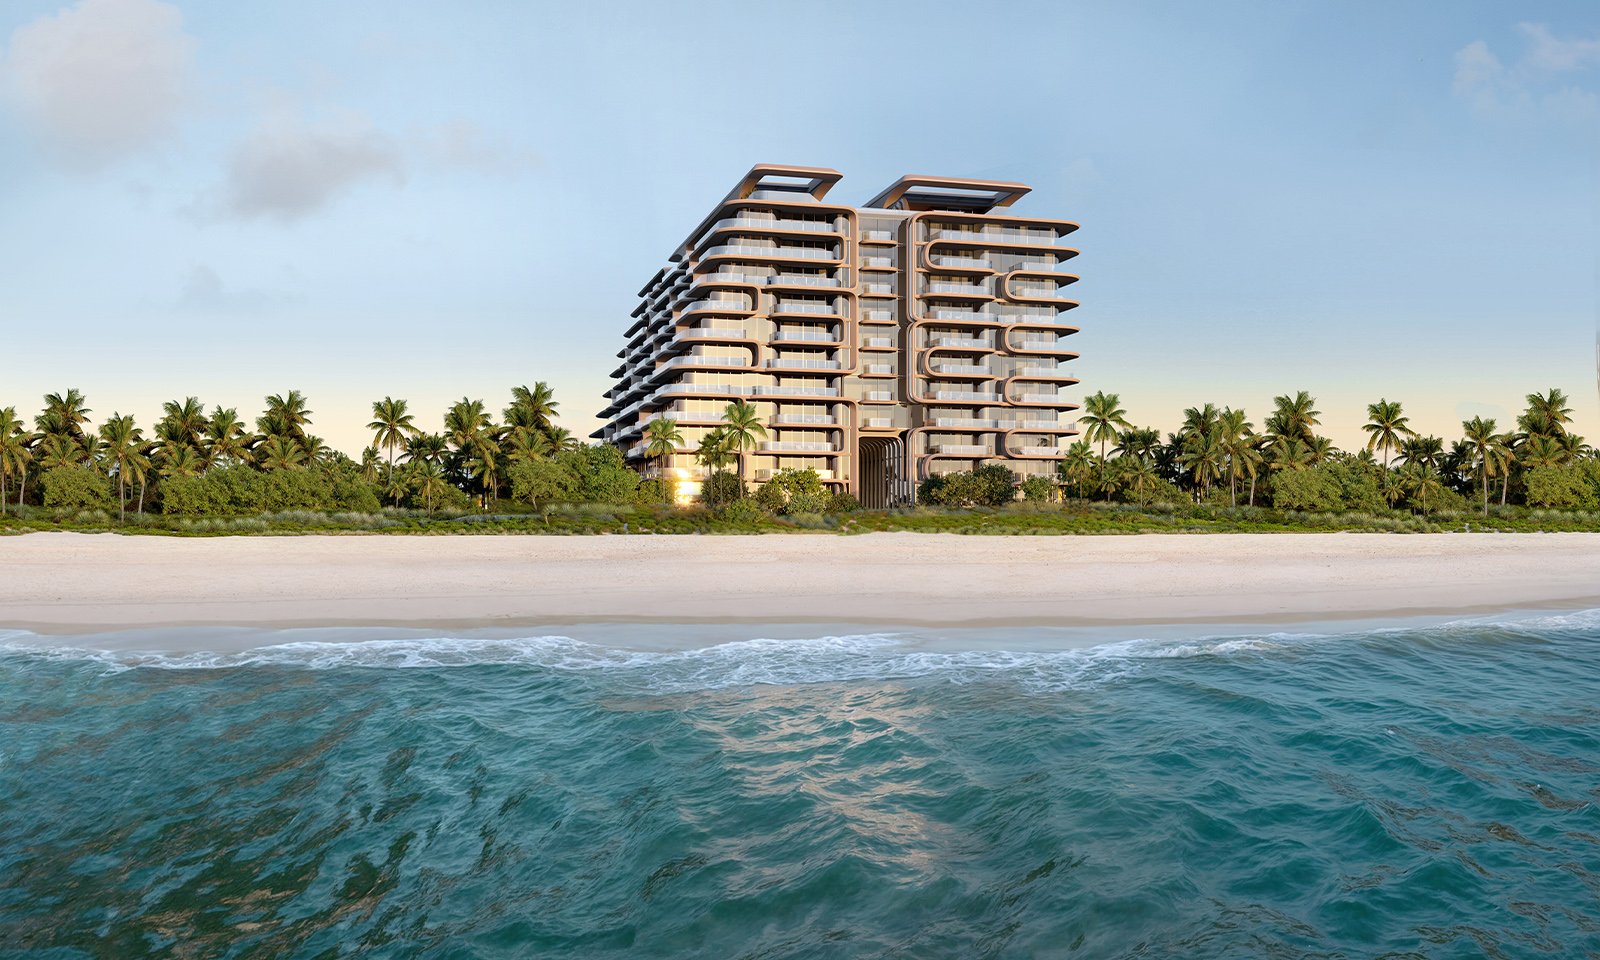
An oceanfront residence deserves a composed arrival: furnishings delivered in sequence, installers cleared for access, and financial obligations understood before the first truck appears. At The Delmore Surfside, preparation begins with a clear distinction between purchasing the residence and obtaining permission to move into it.
The project is planned at 8777 Collins Avenue, Surfside, Florida 33154, as a 12-story boutique tower with an oceanfront collection of 37 residences. It is in its pre-construction sales phase. These details establish the setting, but not the insurance limits, vendor-access procedures, or refundable damage-deposit terms that will govern an eventual move.
For purchasers, the objective is to assemble a written move-in file rather than rely on assumptions. A purchase installment, an insurance certificate, and a damage deposit serve distinct purposes. None substitutes for another.
The purchase-payment schedule sets out five installments: 20% upon contract signing, 10% 120 days after signing, 10% upon pouring the unit slab, 10% at topping off, and the remaining 50% at closing. These are acquisition payments, not charges for elevator access, furniture delivery, or protection against moving damage.
The schedule also includes a 1.75% developer fee. Buyers should have their advisers confirm its calculation base and payment terms in the purchase documents, rather than assume how it will appear on the closing statement.
No refundable move-in damage-deposit amount is identified in that schedule. This does not establish that no deposit will be required. Buyers should obtain the applicable move-in terms separately, rather than use purchase-deposit percentages to estimate them.
Keep separate budget lines for acquisition payments, the developer fee, personal insurance, vendor expenses, and any subsequently confirmed move-in charges. Until written terms are available, a provisional allowance remains a planning assumption-not a stated building fee.
“Move-in insurance” can blur two distinct questions: what coverage the purchaser needs and when it should take effect, and what documentation management may require from movers, furniture carriers, installers, or contractors entering the property.
Ask your insurance adviser to review your intended occupancy, delivery sequence, and any period when furnishings may be in transit or storage. Request written guidance on relevant coverage and effective dates. This is a planning recommendation, not a confirmed Delmore policy requirement.
For vendors, request the approved insurance checklist before commissioning certificates. Vendor certificate-of-insurance limits and approved certificate wording are not specified in the available project details. Do not assume a vendor’s existing certificate will satisfy the eventual building requirements.
Buyers also considering Ocean House Surfside should apply the same document-first approach to each property independently. A location in Surfside does not establish shared insurance or access rules.
Make the request specific: ask for the exact certificate-holder name and address, any additional-insured wording, applicable coverage limits, the submission deadline, and the person authorized to approve the paperwork. Confirm whether requirements differ among movers, delivery companies, installers, and contractors.
Additional-insured status, waiver of subrogation, workers’ compensation, and umbrella coverage are matters to clarify, not confirmed Delmore mandates. If the final instructions require any of them, have the vendor’s insurance representative review the requested language and supporting documents before scheduling the work.
Maintain a simple register of each vendor’s legal name, scope of work, proposed service date, paperwork status, and written approval. Ask whether subcontractors need separate submissions and whether certificates must be refreshed when delivery dates change.
Submitting a document is not the same as receiving approval. Request confirmation that the paperwork has been accepted and that any separate access authorization is complete. An unanswered email is not clearance to dispatch a truck.
If a move-in damage deposit is required, the amount is only the start of the discussion. Obtain written confirmation of who holds it, how it must be paid, what damage it may cover, and which deductions are permitted. Ask whether administrative or access charges are separate and nonrefundable.
Clarify the inspection procedure before moving day. Who records the condition of the delivery route? Can the purchaser or a representative attend? How are pre-existing marks distinguished from new damage, and what documentation supports a proposed deduction?
The refund process should be equally precise. Request the refund deadline, the event that starts that period, the payment recipient, and the procedure for questioning a deduction. Do not treat “refundable” as an unconditional promise before reviewing the written conditions.
As a practical precaution, ask permission to photograph relevant areas before and after the move, and retain delivery records. These are buyer-side recommendations, not assertions about Delmore’s eventual inspection protocol. The aim is a clear record that supports an orderly resolution if a disagreement arises.
Delivery estimates range from Q3 2029 to around 2030. Neither is a guaranteed completion or move-in date. Purchasers should review the contractual delivery provisions with counsel before making commitments tied to occupancy.
New-construction planning should preserve flexibility for storage, shipping, installation, and temporary accommodation. Ask each vendor about rescheduling terms before committing funds on the basis of a particular delivery window. Reconfirm insurance documentation and access arrangements once an actual service date is established.
For buyers weighing Rivage Bal Harbour alongside a Surfside purchase, the useful comparison is the clarity of each property’s written handover and access instructions-not an assumed common move-in standard. Apply the same questions, but keep the answers property-specific.
Before committing to the purchase, distinguish contractual payment obligations from anticipated operating arrangements. Avoid relying on oral representations; review the formal offering documents instead. A reassuring conversation should not replace a written provision on which counsel can advise.
As closing approaches, request the current move-in package and identify the contact authorized to resolve outstanding questions. Confirm personal insurance timing, vendor approvals, any damage-deposit terms, and the delivery-booking process. Keep the latest accepted versions together, with a clear record of changes.
Before dispatch, reconcile the vendor schedule with written access approval. After the move, follow the agreed inspection and refund process, retaining records until any deposit is resolved. This sequence protects the pleasure of arrival without turning unconfirmed requirements into supposed building rules.
For discreet guidance on your next South Florida residence, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe Delmore is planned at 8777 Collins Avenue, Surfside, Florida 33154. The project comprises an oceanfront collection of 37 residences.
Delivery estimates range from Q3 2029 to around 2030. Buyers should verify the contractual delivery provisions rather than treat either estimate as guaranteed.
The schedule lists 20% at signing, 10% after 120 days, 10% upon pouring the unit slab, 10% at topping off, and 50% at closing.
No, the listed installments are purchase payments. The supplied purchase schedule does not identify a refundable move-in damage-deposit amount.
The schedule identifies a 1.75% developer fee. Its calculation base and payment terms should be verified in the purchase documents.
The project details provided do not establish vendor insurance limits or approved certificate wording. Request the current written checklist before arranging certificates.
Neither is established as a mandatory Delmore requirement by the supplied project information. Ask whether the final management instructions require them.
Request the amount, holder, permitted deductions, inspection procedure, and refund deadline in writing. Clarify whether separate nonrefundable charges apply.
Buyers should not assume that submission establishes approval. Request written acceptance of the paperwork and confirmation of any separate access authorization.
Buyers should avoid relying on verbal assurances alone. Obtain written terms and have the relevant purchase provisions reviewed by counsel.