A discreet South Beach acquisition begins with disciplined payment controls. Align deposit schedules, independently verified wire instructions, approval authority, banking service and document retention before funds move.
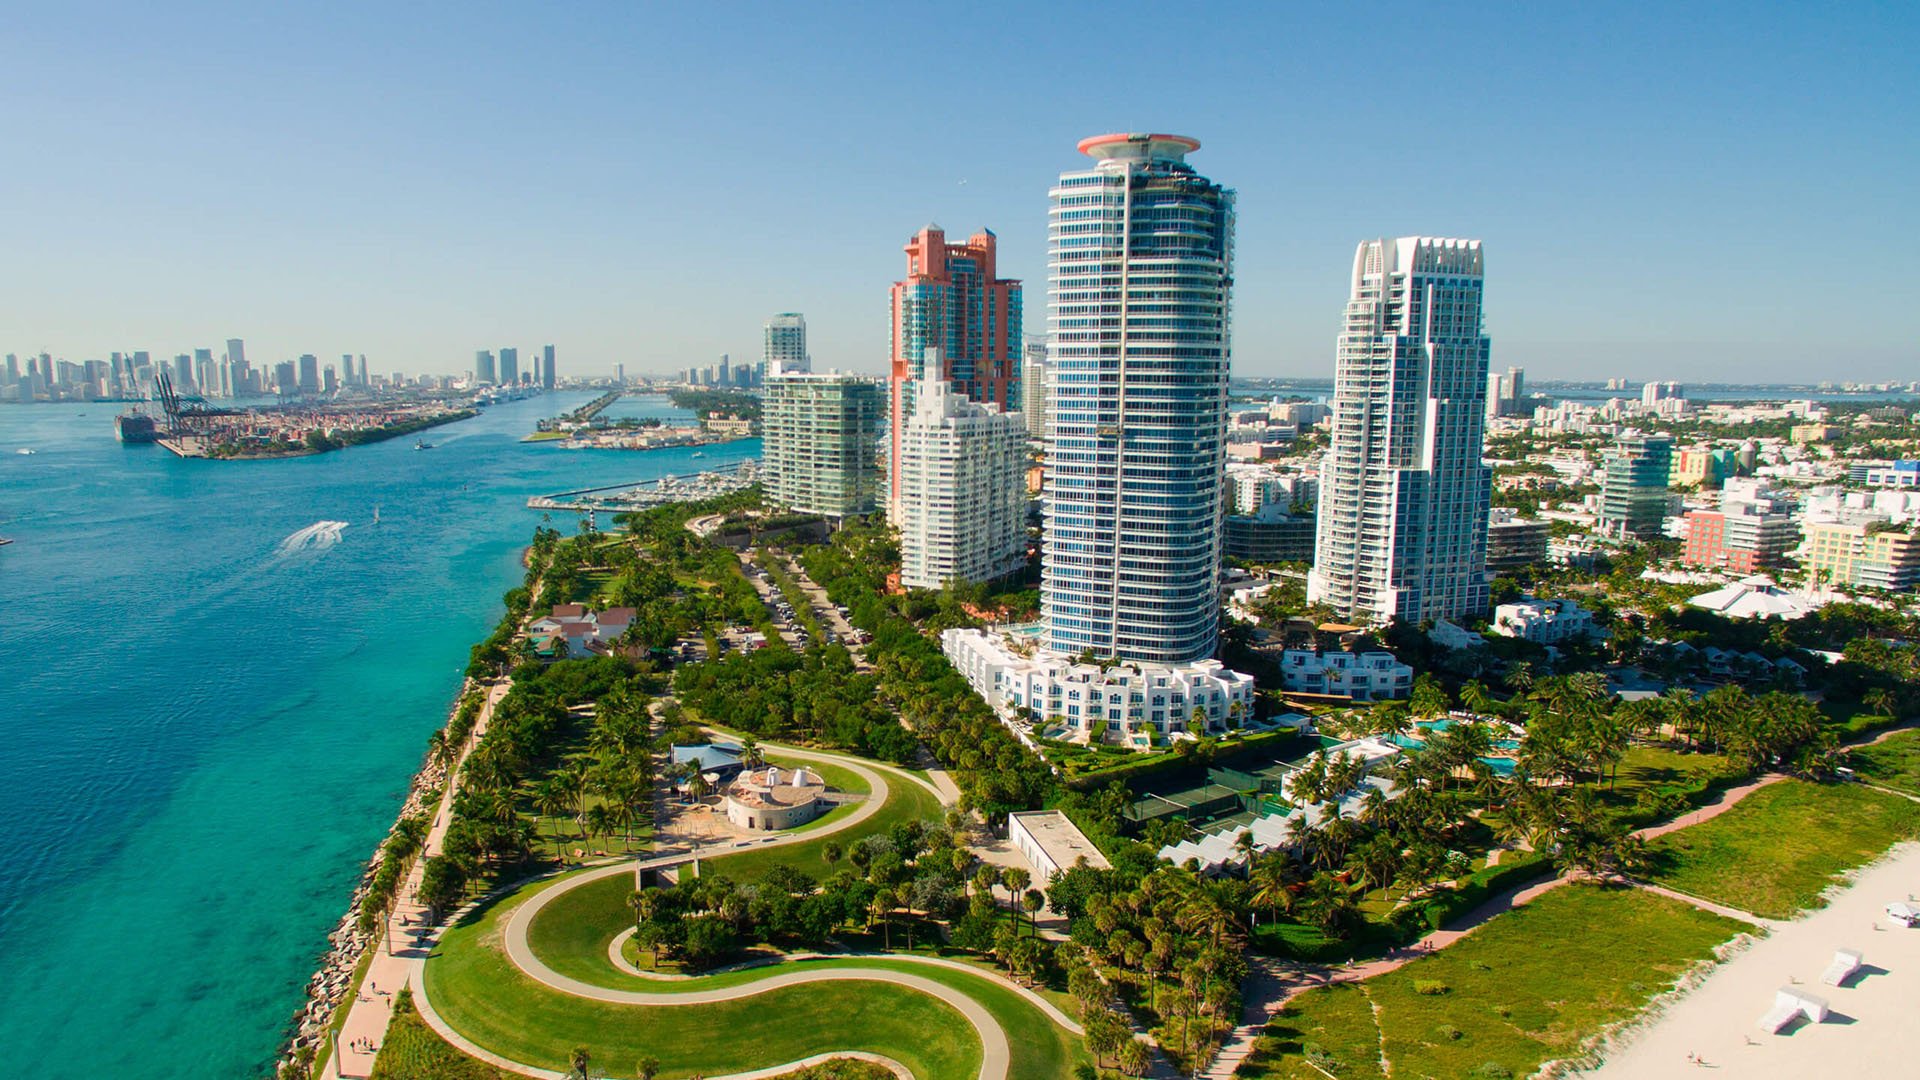
For a family office acquiring a South Beach residence, privacy should mean controlled access, not an incomplete record. The purchase deserves an operating framework as considered as the residence itself: clear authority over deposits, independently verified payment instructions and a retrievable record of every release.
Whether the search centers on Apogee South Beach or another address, establish the buyer’s controls before funds move. A property’s appeal does not determine who may approve a wire, and attentive service should never substitute for verification. The objective is a quiet, well-documented transaction that does not require the principal to supervise every administrative step.
The framework below is a proposed family-office operating policy, not a statement of universal legal requirements. Contract terms, banking capabilities and counsel’s advice should shape its implementation.
Start with a transaction register drawn from the executed agreement and any amendments. As an internal practice, record each deposit’s contractual trigger, amount, due date, designated recipient and responsible staff member. Keep the underlying obligation distinct from the bank instructions used to satisfy it.
For a prospective purchase at Continuum on South Beach, that distinction is useful without presuming a particular seller’s terms. Work from the actual agreement, not a remembered timetable or an informal message.
Assign someone to reconcile the approved payment, bank confirmation and recipient acknowledgment. Sending a wire does not complete the task. Contact the title company promptly after sending closing funds to confirm receipt; for other deposits, establish the appropriate acknowledgment process with the designated recipient.
Second-home purchases deserve the same discipline as other significant family assets. Build review time into the calendar so an approaching deadline does not become an informal exemption from controls.
Separating access-rights administration, payment initiation and payment approval is an established bank wire-control principle. A family office can adapt it to its own policy without treating bank examination standards as obligations imposed on every private buyer.
A practical proposed structure assigns payment preparation to one person and release approval to another, with access administration kept separate. Before choosing a bank or portal, ask for a demonstration of whether its permissions support that structure. Do not assume a prestigious relationship provides the required workflow.
Set internal approval thresholds around the family’s governance and transaction exposure, not an arbitrary industry number. Decide in advance which payments require principal approval, who acts when an approver is unavailable and how authority is documented.
As a proposed safeguard, require fresh verification and approval whenever recipient details change, regardless of amount. Record each exception’s reason, authorizer and resolution. Urgency should trigger escalation, not silently expand someone’s authority.
Confirm wire instructions by telephone before transferring funds. Obtain the verification number independently-for example, from the title company’s official website-not from the email containing the instructions.
Ask the bank to confirm both the receiving account number and the name associated with that account before sending. Establish what verification the bank can actually provide; entering a recipient name should not be assumed to guarantee a match.
Changed wiring instructions are a fraud warning sign, particularly when the requested recipient’s name differs from the title company’s name. Under the family office’s proposed policy, pause the release while the change is independently checked. A familiar email thread is not enough to resolve the concern.
Retain a verification note recording the independently obtained contact, the person reached and the details checked. Keep sensitive account information in the controlled transaction file rather than circulating it in a broad approval email. Verification should leave evidence without creating unnecessary copies of financial data.
For buyers considering Setai Residences Miami Beach, discretion translates into specific communication choices. Avoid ordinary email for sensitive financial information where possible; favor a secure portal, verified telephone communication or an in-person exchange.
Use multifactor authentication and unique, complex passwords for email accounts. Do not reply directly to a suspicious message. When email contact is necessary, manually enter an independently verified address.
Within the family office, a proposed need-to-know approach gives each participant only the information required for the assigned task. Counsel, treasury staff and the principal may need different views of the same transaction. Ask whether the chosen system can accommodate those differences, and review access when responsibilities change or the transaction closes.
Privacy and documentation are complementary: fewer uncontrolled copies, but a complete authorized record.
A Miami Beach search that includes Five Park Miami Beach also warrants a separate evaluation of the banking relationship supporting the purchase. Assess account, custody, wire, foreign-exchange, treasury-service and portal charges together. Request written terms relevant to the intended activity.
A useful comparison pairs each cost with a capability. Can the portal enforce separate approvals? Can authorized staff retrieve transaction records? Who handles an urgent verification issue, and what backup exists when the primary contact is unavailable? Seek clear answers rather than inferring operational service from relationship branding.
An office in Miami does not establish dedicated South Beach coverage or guaranteed response times. Confirm availability, escalation arrangements and service eligibility directly. No single fee should decide the comparison; identifying the lowest-cost option would require comparable quotes and a defined scope of service.
The better question is whether the proposed relationship supports the family office’s controls at an understood total cost.
Create one controlled transaction file containing the executed agreement, amendments, deposit register, verified instructions, approval evidence, bank confirmations, recipient acknowledgments and relevant closing documents. Include access decisions and exception records as proposed internal practices, not presumed legal requirements.
Have counsel and tax advisers help determine the retention schedule for the purchasing entity and transaction. Do not adopt a generic number of years without that review or assume immutable storage is universally mandatory. Select storage that supports appropriate permissions, reliable retrieval and the agreed retention policy.
Maintain a written wire-fraud response plan with current contacts and assigned responsibilities. If fraud is discovered, contact the banks, transaction parties and law enforcement immediately. Staff should know who initiates the response without waiting for the next routine approval meeting.
The desired result is understated but substantial: every payment has an owner, every destination is checked and every material decision can be reconstructed.
Explore South Beach residences with MILLION while keeping your family office’s acquisition controls firmly in view.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe proposed two-person approval structure is an internal governance policy, not a universal legal requirement. It adapts a bank wire-control principle to the family office’s needs.
Create a register from the executed agreement and amendments, recording amounts, triggers, due dates, recipients and responsible staff. Reconcile payments with bank confirmations and recipient acknowledgments.
Confirm them by telephone using a number obtained independently, not one supplied in the instruction email. Ask the bank to confirm the receiving account number and associated name before sending.
Treat the change as a fraud warning sign, particularly if the recipient name differs from the title company’s name. The proposed policy is to pause release pending independent verification and renewed approval.
Contact the title company promptly after sending closing funds to confirm receipt. A bank confirmation should not replace that recipient check.
Avoid ordinary email where possible and use a secure portal, verified telephone communication or an in-person exchange. Protect email accounts with multifactor authentication and unique, complex passwords.
Compare account, custody, wire, foreign-exchange, treasury-service and portal charges alongside approval capabilities and emergency support. Request comparable written terms rather than judging one fee in isolation.
No. Confirm South Beach coverage, availability, escalation arrangements and service eligibility directly rather than inferring them from an office location.
Set the schedule with counsel and tax advisers for the purchasing entity and transaction. The framework does not prescribe a universal retention period or require immutable storage.
Contact the banks, transaction parties and law enforcement immediately. A written response plan should identify current contacts and assign responsibility for initiating that response.