A discreet preparation guide for Onda owners and buyers, separating building-specific disclosures from regional insurance pressures and outlining a disciplined approach to renewal discussions and financing review.
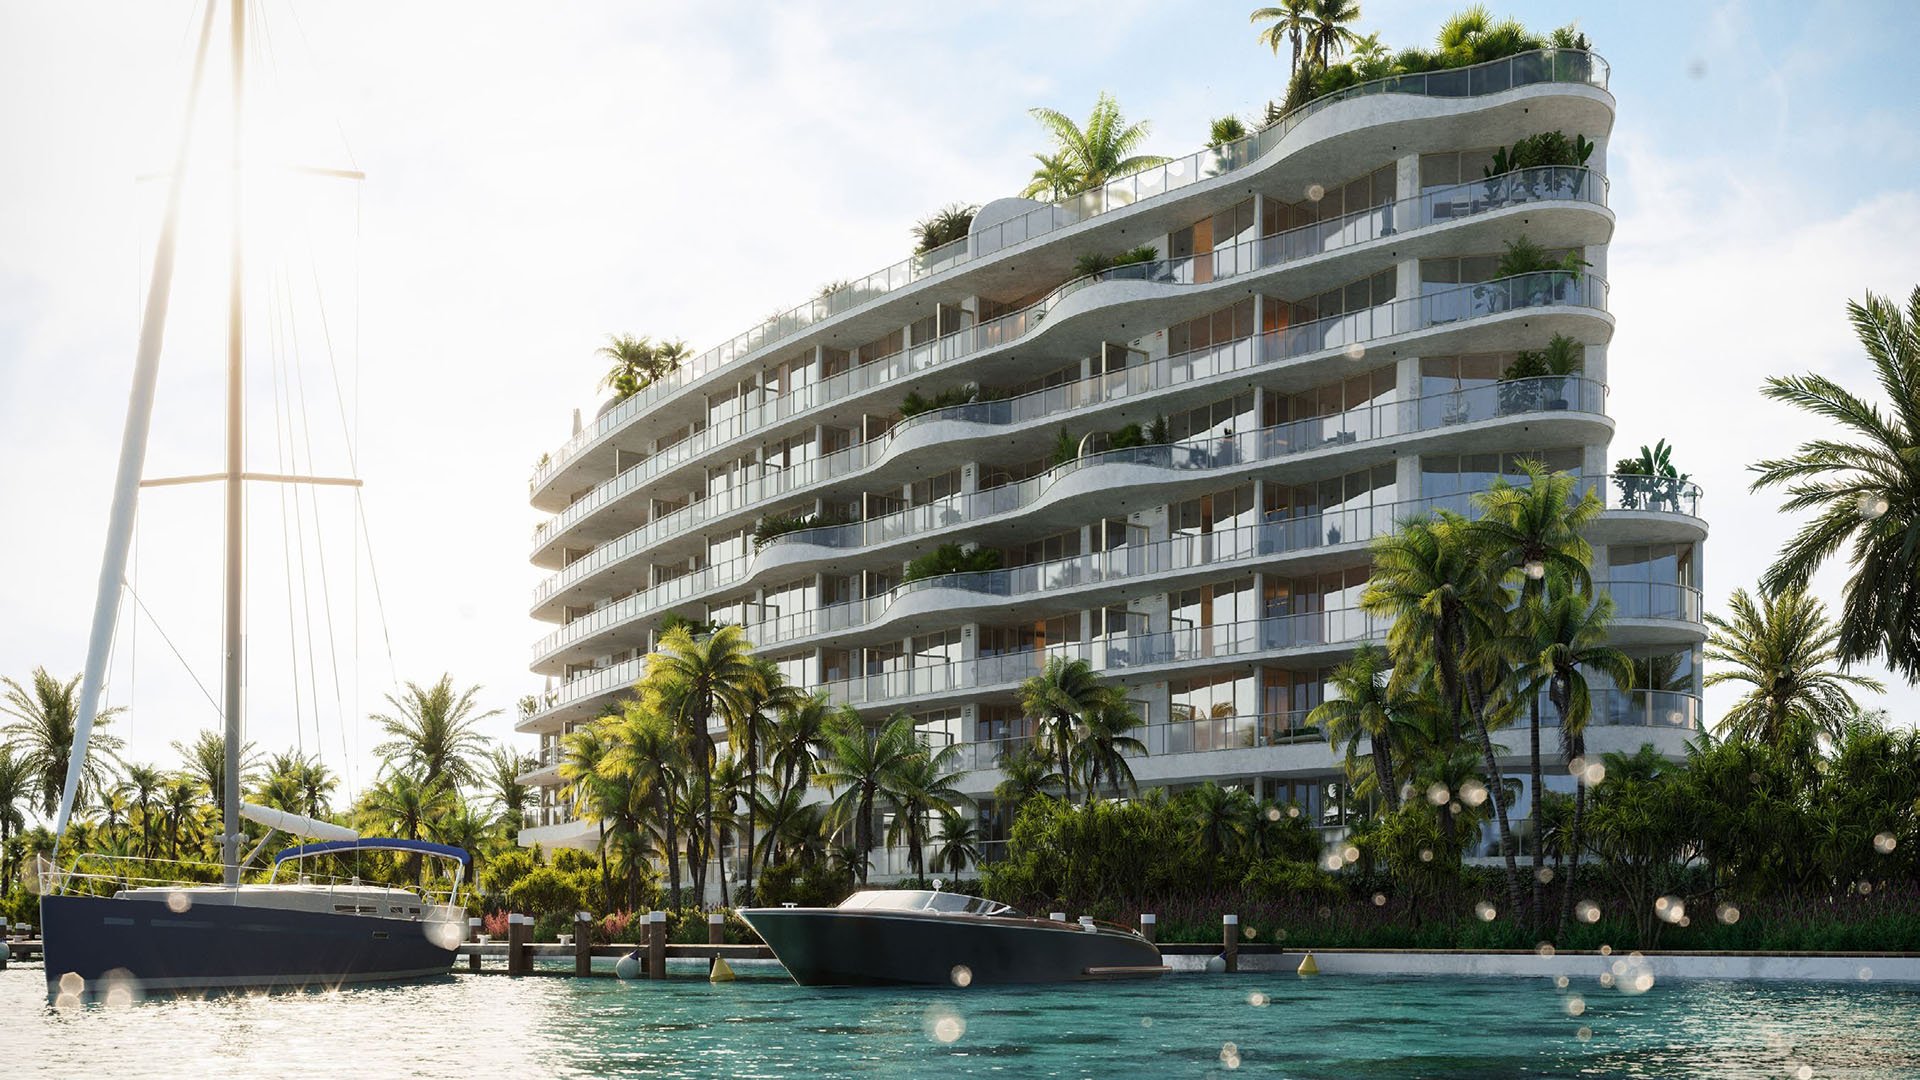
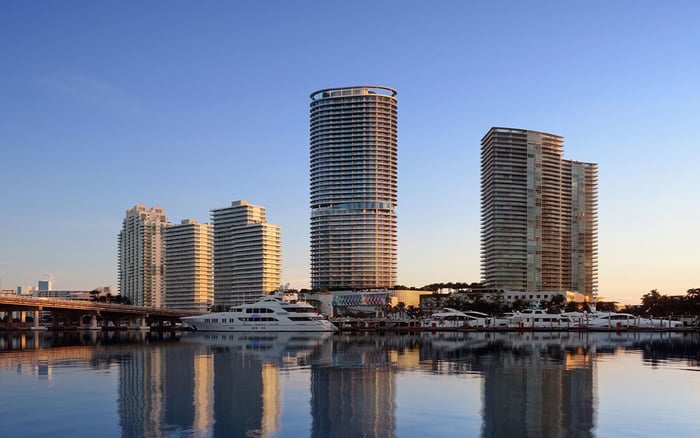
Preparing a high-value condominium for sale requires more than an assured presentation. At Onda Bay Harbor, the financial and legal record deserves the same attention as the residence itself. Completed in 2024 by CMC Group and Morabito Properties, Onda is an eight-story, 41-unit condominium at 1135 103rd Street in Bay Harbor Islands.
This is a preparation framework, not an assertion of litigation, structural defects, insurance difficulty or lender rejection at Onda. No such Onda-specific condition is established here. The essential distinction is between questions a prudent buyer should ask and conclusions that require current, building-specific evidence.
For an owner considering a transaction, the objective is straightforward: present a coherent picture of ownership without overstating certainty. An orderly file can support informed conversations, but it cannot promise a particular valuation, premium or financing outcome.
Before bringing a residence to market, request the association's current budget, reserve information, available engineering documentation, insurance declarations and renewal history. This is a suggested preparation package, not a universal lender checklist. Record each document's date and identify anything awaiting an update.
Separate association obligations from expenses belonging to the individual residence. Master-policy costs, reserve contributions and unit-owner insurance should not be folded into an unexplained monthly figure. Ask management to clarify what the association budget includes and what the owner pays separately.
For buyers also considering Bay Harbor Towers, apply the same document categories to each property. The comparison should not imply equivalent budgets, coverage or financial circumstances. Its purpose is to make differences visible, rather than let an attractive purchase price obscure unanswered ownership questions.
Historical inventory also needs a clear date. Onda had sold all but three residences as of August 6, 2024. That snapshot does not establish current availability or the terms of any present offering.
If a relevant dispute exists, ask qualified counsel to prepare or review a factual summary suitable for the transaction. Clarify who is involved, what is alleged, the procedural status and whether any financial obligation has actually been determined. Keep allegations, unresolved exposure and established obligations distinct.
Avoid casual assurances that a dispute is immaterial or fully insured. Ask counsel and the insurance adviser to confirm what can responsibly be said about coverage, costs and unresolved issues. A seller's narrative should not substitute for the underlying documents.
Do not treat an estoppel certificate as a complete litigation history. Ask counsel which disclosures and supporting records are appropriate for the specific transaction, rather than assume a single certificate must identify every pending or prior lawsuit.
Association disputes raise a separate insurance question: directors-and-officers liability coverage. D&O coverage is distinct from property insurance for the building. Neither its existence nor the association's master property policy establishes that a particular dispute is covered. That determination requires policy-specific review.
In Miami-Dade, average association commercial multi-peril premiums increased from $175,000 at the start of 2021 to $462,000 by the end of 2024, a 164% rise. These historical figures describe a defined market and coverage category. They do not establish Onda's premium, deductible, dues or renewal trajectory.
The distinction between association and individual insurance matters just as much. Association master policies cover common property such as roofs and building structures and are separate from unit-owner policies. Average individual condominium-owner premiums in Miami-Dade were approximately $2,300 annually at the end of 2024, compared with about $1,600 three years earlier.
None of these averages substitutes for an actual quotation on a high-value residence. For owners comparing Bay Harbor Islands with Miami Beach, they provide context for better questions, not a formula for estimating either property's costs.
The association's renewal discussion should begin with a clear comparison of existing and proposed coverage. Ask its insurance adviser to examine limits, exclusions, deductibles, loss history and any relevant remediation documentation. These are review topics, not guaranteed routes to a lower premium.
A useful comparison should explain whether a quoted saving comes with a change in coverage or retained risk. Ask how each deductible operates, which exclusions have changed and what questions remain unresolved. Keep the distinction between a preliminary quote and confirmed coverage explicit.
For the individual residence, request a separate review of the owner's insurance needs alongside the association policy. The aim is to understand how the two relate, not to assume the master policy covers every loss affecting a valuable interior.
A buyer weighing Alana Bay Harbor Islands alongside Onda should likewise seek property-specific insurance information. Proximity alone does not establish comparable premiums or policy terms. A disciplined negotiating position rests on documented coverage, not a promise that another building's experience can be replicated.
Sharply higher association insurance costs were linked to weaker South Florida condominium sales in December 2024. That regional pressure does not establish how a lender will respond to an Onda purchase or whether a particular financing request will qualify.
Ask the intended lender early which association, insurance and financial records it requires for the proposed loan. Where relevant, provide the counsel-reviewed dispute summary and distinguish confirmed costs from estimates. Seek clarification of unresolved conditions rather than treat an initial conversation as final approval.
For household planning, consider the current documented ownership cost alongside an explicitly hypothetical higher-cost scenario. This is a buyer's budgeting exercise, not a claim that every lender applies a particular debt-to-income stress test. Any financing conclusion should come from the lender reviewing the actual borrower, property and loan.
Insurance and reserve funding are significant drivers of condominium association fees. For an Onda transaction, ask qualified advisers which inspection and reserve requirements apply. Onda's 2024 completion is not a basis for assuming either the same inspection deadlines as an older tower or exemption from every relevant obligation. Obtain property-specific guidance.
Before presenting the residence, reconcile the budget, insurance information and any counsel-reviewed disclosures into one dated file. Label projections as projections and leave unresolved questions visible rather than smoothing them away. For a high-value transaction, precision is more persuasive than reassurance unsupported by documents.
For a considered perspective on South Florida's exceptional residences, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationOnda is at 1135 103rd Street in Bay Harbor Islands. The condominium has eight stories and 41 residences.
CMC Group and Morabito Properties completed Onda in 2024.
No Onda-specific lawsuit, settlement or structural defect is established here. The article offers a preparation framework, not a finding about the building.
Suggested records include association budgets, reserve information, available engineering documentation, insurance declarations and renewal history. Any relevant litigation summary should be reviewed by counsel.
Do not assume it does. Ask qualified counsel which disclosures and supporting records are appropriate for the transaction.
Association master policies cover common property such as roofs and building structures. They are distinct from the individual unit-owner policy, so both should be reviewed.
No. Historical regional averages do not establish Onda's actual premiums, deductibles, dues, reserves or current renewal terms.
Review coverage limits, exclusions, deductibles, loss history and any relevant remediation documentation with the insurance adviser. These reviews do not guarantee lower premiums.
No, D&O liability coverage addresses a separate insurance concern involving association leadership and disputes. Whether a particular matter is covered requires policy-specific review.
No Onda-specific lender rejection or financing-eligibility conclusion is established. Ask the intended lender to review the actual borrower, property records and proposed loan.