A buyer-focused guide to the insurance documents behind Five Park ownership, from appraisal provisions and percentage-based storm deductibles to Florida’s loss-assessment coverage requirements.
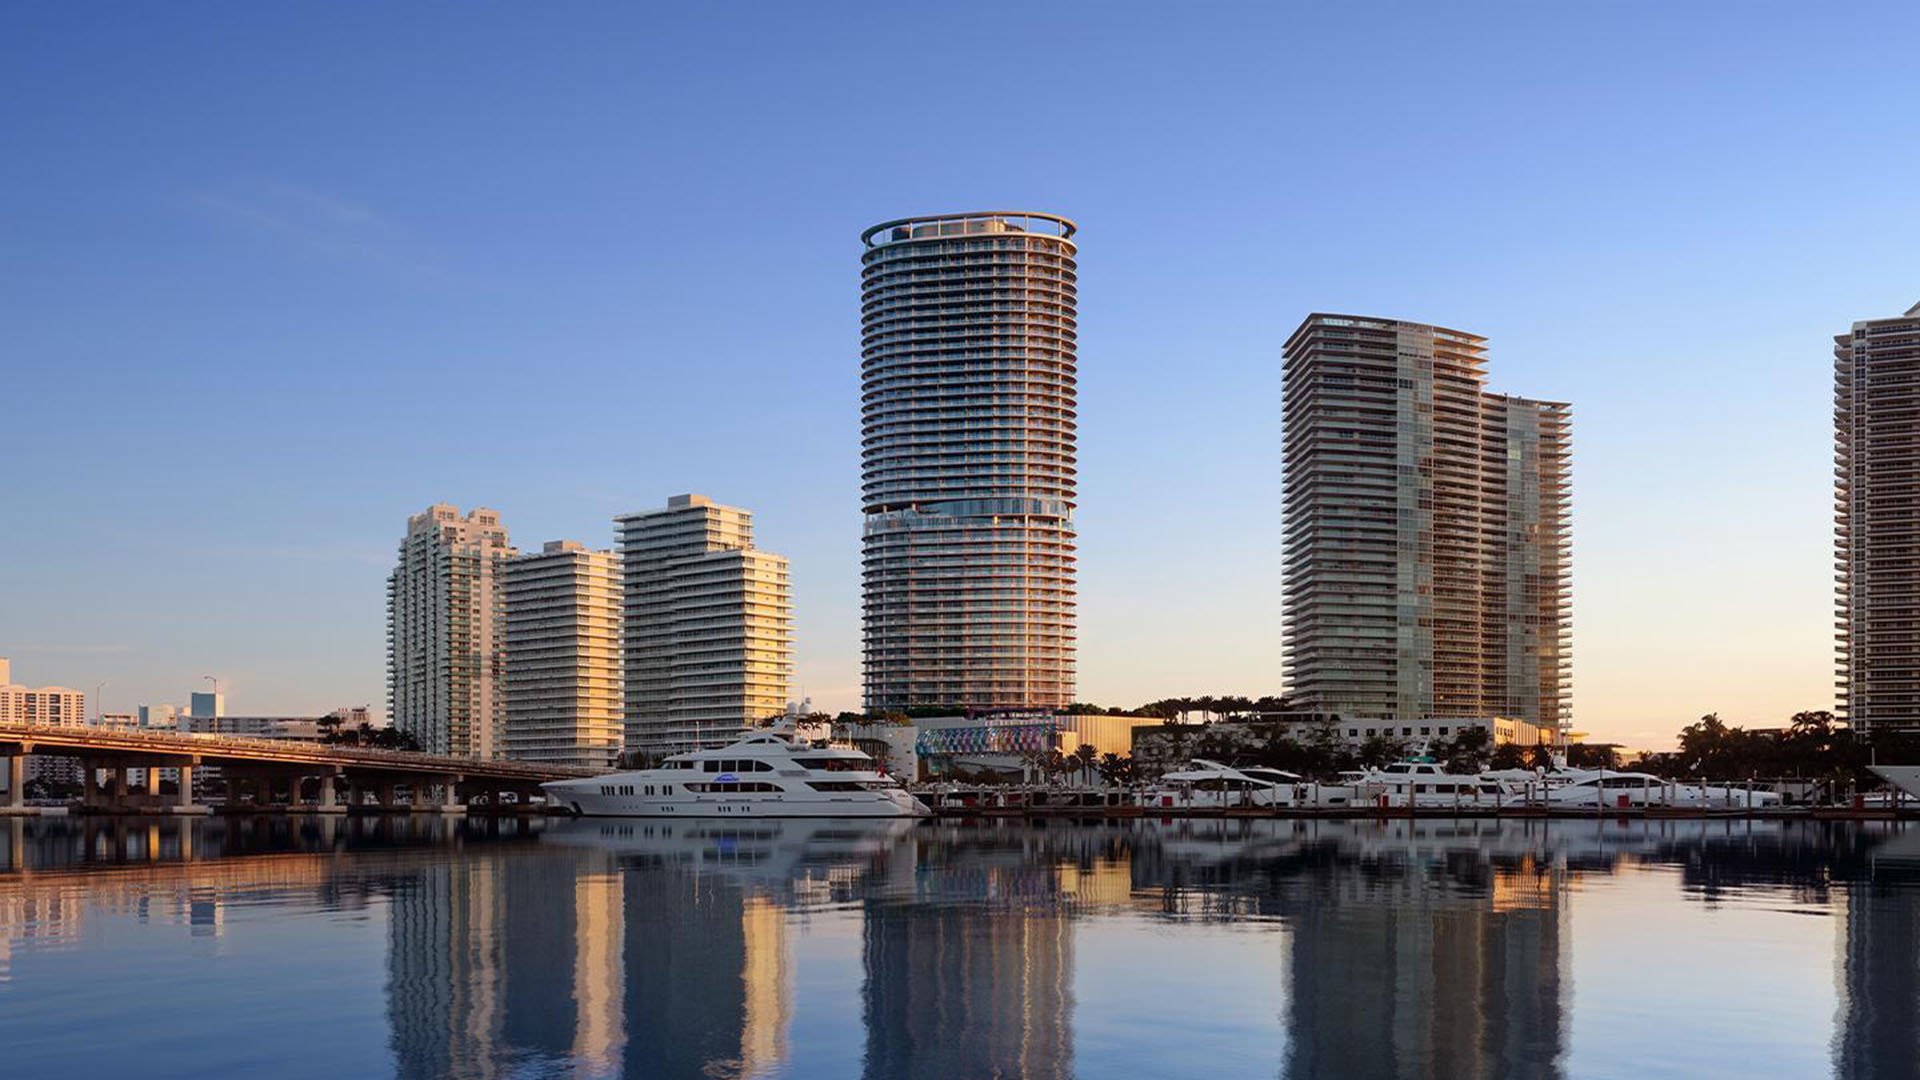
At Five Park Miami Beach, 500 Alton Road, the ownership conversation should extend beyond the residence itself. For a buyer evaluating a significant Miami Beach acquisition, insurance merits the same scrutiny as the condominium documents: what the association insures, what remains the owner’s responsibility, and how a disputed claim becomes a payment.
Building insurance is among the reported HOA-fee inclusions. That is a starting point, not a description of coverage. Confirm the current policy and expense allocation directly with the association; an insurance line in the budget is not a complete answer.
Three distinctions frame the review. Insurance appraisal is not a resale valuation. A percentage deductible does not define dollar exposure until its calculation basis is known. And loss-assessment coverage is not a promise to reimburse every association charge.
Residence 3703 has been described with “Complete Impact Glass” and “High Impact Door.” Those details document that residence, not every unit in the building. Nor do they establish the association’s storm deductible, the owner’s insurance terms, or the allocation of a future assessment.
Keep physical specifications and insurance obligations in separate parts of the ownership file. Verify the features of the residence being purchased, then ask the insurance adviser to evaluate the actual contracts. Building descriptions are no substitute for policy language.
Apply the same discipline to a comparison with Apogee South Beach. Review each property’s own documents rather than assuming the two addresses offer equivalent insurance protection. The useful comparison is contractual: covered property, deductibles, limits, and responsibility for the remaining expense.
In property insurance, appraisal addresses disagreements over property value or the amount of loss under the applicable clause. It is distinct from the market appraisal a purchaser might use to evaluate an acquisition price.
A clause may permit either the insured or the insurer to demand appraisal in writing when they disagree over value or the amount of loss. Under that form of provision, each selects a competent and impartial appraiser; the two appraisers then select an umpire. Agreement by any two panel members establishes the binding appraisal decision.
Do not assume this wording appears in Five Park’s master policy or in every unit-owner policy. Read each actual appraisal provision, including the requirements for initiating the process and selecting participants. Identify the policy involved before determining which rights the owner or association can exercise.
The appraised loss and the final insurance payment can differ. Some appraisal wording does not direct the panel to subtract deductibles or prior payments from its award. Do not automatically treat an award as the net amount available for repairs. Ask the adviser to explain how the loss determination translates into the payable claim.
A hurricane deductible can be percentage-based. Its practical meaning depends on the insured-value basis specified in the contract-not the purchase price of an individual residence.
Read the declarations and deductible schedule carefully for Hurricane, Named Storm, Wind, Other Wind, and Hail. Do not collapse these labels into one assumed storm deductible. The wording identifies what must be examined before calculating exposure, including the relevant trigger and any minimum or maximum.
For a deductible expressly based on total insured value, the calculation begins with:
Total insured value × deductible percentage = building-level deductible before applicable minimums or maximums.
The next question is allocation. Dividing that amount by the unit count produces only a rough equal-share estimate; it does not establish what a particular Five Park residence would owe. Review the condominium declaration, bylaws, applicable policy terms, and confirmed association allocation together.
For a purchaser also considering Continuum on South Beach, request a separate calculation using that property’s own policy. A percentage detached from its value basis and allocation rules is not a meaningful ownership-cost comparison.
For Five Park, obtain the current insured value, deductible wording, and residence-specific allocation before entering a storm-exposure figure into a personal liquidity plan. Keep an illustrative calculation clearly separate from a confirmed obligation.
Florida Statute § 627.714 requires at least $2,000 in property loss-assessment coverage under condominium unit-owner residential property policies issued or renewed on or after July 1, 2010. That amount is a legal floor, not a finding that $2,000 adequately protects a Five Park owner.
The statutory coverage concerns assessments arising from a direct loss to collectively owned condominium property when the loss results from a peril covered by the unit owner’s policy. An association’s decision to levy an assessment does not, by itself, establish that the owner’s insurer will reimburse it.
The statute permits a loss-assessment deductible of no more than $250. Distinguish that deductible from the association’s storm deductible: they operate at different levels of the insurance review.
Timing matters as much as the stated limit. The maximum payable for one loss is governed by the loss-assessment limit in effect one day before the occurrence. Increasing coverage after the event does not enlarge protection for that loss.
Nor do multiple assessments from the same direct loss require the insurer to pay more than the applicable coverage limit. Evaluate the limit against the potential loss, not simply the size of the first assessment notice.
A useful ownership file should contain the current master policy and endorsements, deductible schedule, condominium declaration and bylaws, association budget, and the owner’s HO-6 policy. Review them together rather than relying on isolated summaries.
Ask the association and insurance adviser to help answer three practical questions:
Which responsibilities fall under the master policy, and which fall under the owner’s coverage for interiors, belongings, liability, and covered loss assessments?
How does each relevant storm deductible translate into dollars, and how would an assessment be allocated to this residence?
What appraisal language and loss-assessment limits actually apply, including any relevant endorsements?
The objective is not to eliminate every uncertainty. It is to distinguish documented obligations from assumptions before committing capital. A carefully assembled insurance file supports more deliberate ownership decisions, with the residence and its financial responsibilities considered together.
For a considered approach to South Florida ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationFive Park is at 500 Alton Road, Miami Beach.
Building insurance is among the reported HOA-fee inclusions. Confirm the current coverage and expense allocation directly with the association.
No. Property-insurance appraisal addresses disagreements over property value or the amount of loss under the applicable insurance clause, rather than providing a real-estate market valuation.
Under one form of provision, the insured and insurer each select a competent and impartial appraiser, and those appraisers select an umpire. Agreement by any two panel members establishes the binding decision, but the actual policy wording must be checked.
No. An appraisal award may not subtract deductibles or prior payments, so the appraised loss and net payment can differ.
When expressly based on total insured value, multiply that value by the deductible percentage before applying relevant minimums or maximums. Confirm the policy’s calculation basis rather than using the residence’s purchase price.
That produces only a rough equal-share estimate. It does not establish the verified assessment allocation for a particular Five Park residence.
Florida Statute § 627.714 requires at least $2,000 under qualifying condominium unit-owner policies issued or renewed on or after July 1, 2010. It permits a loss-assessment deductible of no more than $250.
No. The statutory coverage concerns assessments from direct loss to collectively owned condominium property caused by a peril covered by the unit owner’s policy, subject to the applicable limit.
No. The maximum payable is governed by the limit in effect one day before the occurrence, and multiple assessments from the same direct loss do not require payment beyond that limit.