Moving from Montreal to Key Biscayne calls for more than a new address. A disciplined travel calendar, a review of Canadian residential ties, and consistent records help distinguish the home purchase from the cross-border residency analysis.
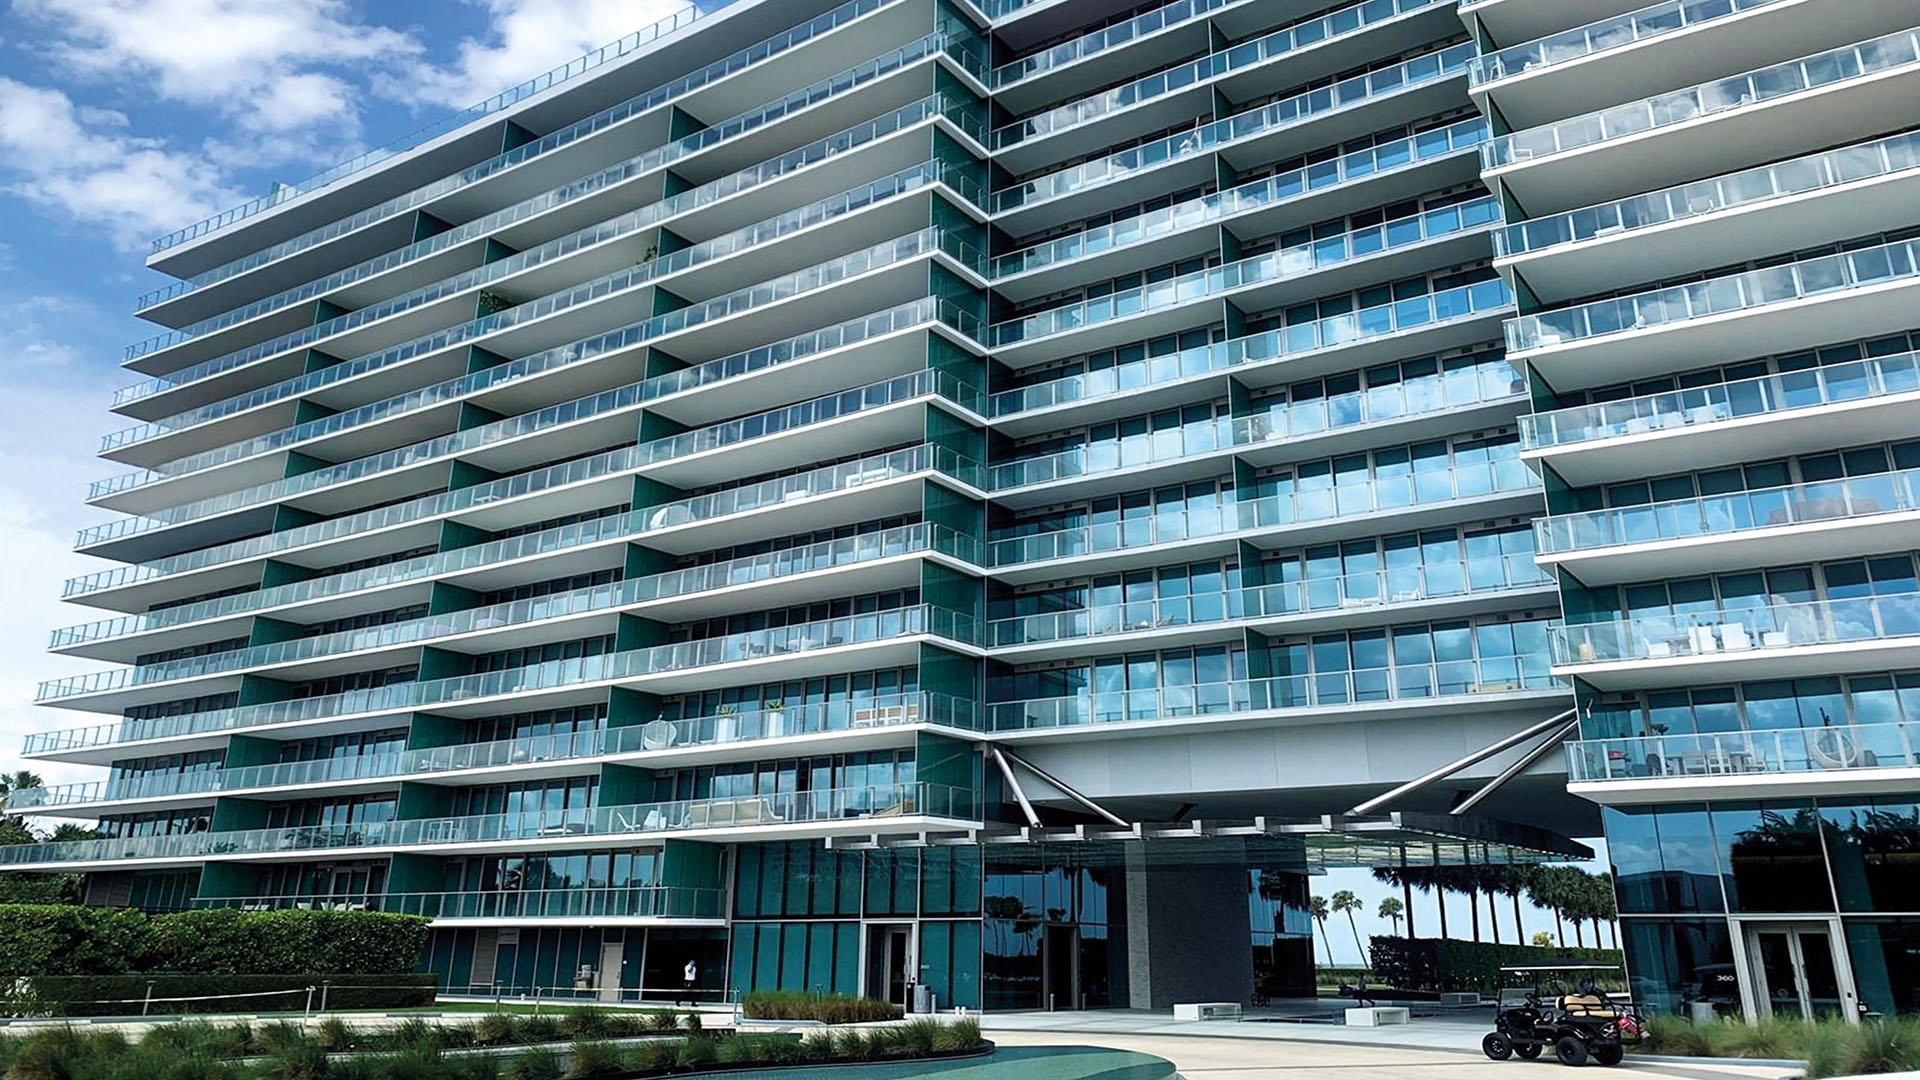
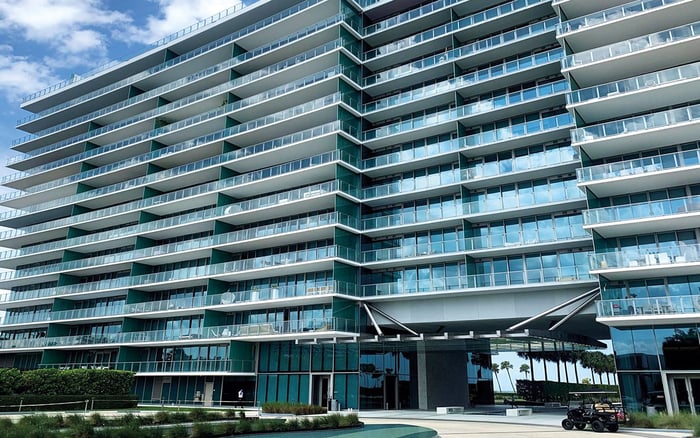
For a Montreal household making Key Biscayne its principal home, the transition is not simply from one property to another. It is from a seasonal pattern to an everyday life reflected consistently in travel records, household arrangements, and tax filings. A residence at Oceana Key Biscayne may anchor that decision, but the purchase alone does not resolve cross-border residency.
Three questions should remain separate: where the household actually lives, whether U.S. federal tax-residency rules apply, and whether Canadian residential ties continue to support Canadian residency. Florida domicile and local property requirements warrant their own legal review. The federal and Canadian thresholds discussed here are neither Florida day-count rules nor proof of entitlement to a local property benefit.
The objective is not to assemble a persuasive paper narrative. It is to make the records accurately reflect the move.
The U.S. substantial presence test generally requires at least 31 days of presence in the current year and 183 weighted days across the current year and the two preceding years. The calculation includes all current-year U.S. days, one-third of the preceding year's days, and one-sixth of the second preceding year's days.
That structure matters for households that already spent earlier winters in South Florida. Keeping current-year visits below 183 actual days does not necessarily prevent U.S. tax residency: earlier travel contributes to the calculation. Before choosing a relocation date, reconstruct the two preceding years rather than considering only the coming season.
U.S. presence generally includes any day on which a person is physically in the country at any time, subject to specified exclusions. A calendar based solely on overnight stays can therefore miss relevant days. Record arrival and departure dates explicitly, and have a cross-border adviser review any claimed exclusions separately.
This is a tax-residency calculation, not a substitute for immigration advice or a Florida domicile determination.
The closer-connection exception generally requires fewer than 183 actual U.S. days during the relevant year, a foreign tax home, and stronger connections to the foreign country than to the United States. Under the general rule, that foreign tax home must exist for the entire current year.
For a household genuinely shifting its primary life to Key Biscayne, those conditions warrant careful scrutiny. Establishing an actual U.S. tax home during the move can undermine reliance on a closer connection to Canada. Taking steps toward lawful permanent-resident status, or having a pending application, can also make the exception unavailable.
Avoid combining incompatible assumptions: treating Florida as the new center of life while automatically relying on a Canadian tax home to avoid U.S. residency. Have advisers evaluate the facts before the travel calendar becomes a filing position. Staying below one annual threshold is not, by itself, a complete strategy.
Canadian tax residency is determined case by case from residential ties and other relevant facts, not solely by a day-count threshold. Significant ties include a Canadian home, a spouse or common-law partner in Canada, and dependants in Canada. Secondary ties can include personal property, social memberships, employment or business involvement, bank accounts, credit cards, and investment accounts.
Someone who leaves Canada but retains residential ties is usually considered a factual resident rather than an emigrant. Fewer than 183 days in Canada does not independently establish non-resident status when significant ties remain. Repeated Montreal visits also matter in assessing the length, purpose, intent, and continuity of stays inside and outside Canada.
If the property search extends to Coconut Grove, a comparison with Park Grove Coconut Grove should remain a housing decision, separate from the analysis of retained Canadian ties. Neither choosing a particular residence nor changing a mailing address resolves whether the Montreal home and family arrangements still support Canadian residency.
Maintain one master travel calendar for each household member whose residency requires review. Record arrivals, departures, physical-presence days, overnight locations, and travel involving more than one jurisdiction. Separate planned itineraries from completed journeys so a changed flight or extended visit does not distort the annual tally.
Keep supporting travel evidence alongside the calendar. Tickets, itinerary changes, and other available records can help explain discrepancies, but the log should reflect actual travel, not reservations alone. Review it regularly rather than reconstructing the year only when returns are due.
Keep the U.S. and Canadian analyses distinct. The weighted U.S. calculation answers a specific federal question; the pattern and purpose of Montreal visits contribute to a broader Canadian assessment. One spreadsheet can support both reviews, but it should not imply that both countries apply the same test.
Treat the calendar as a documentation practice, not a legal safe harbor. Its value lies in making the facts accessible and internally consistent.
Create a relocation file documenting the Key Biscayne move date, changes to Montreal housing, household relocation records, and changes to family and economic ties. Distinguish the purchase date from the date the residence actually becomes the household's principal home. Record staged moves accurately if family members relocate at different times.
A secondary Florida address also needs a clear description. If a household considers Una Residences Brickell while retaining Key Biscayne as its intended primary residence, records should distinguish the actual use of each home. Brickell ownership should not become shorthand for where the household lives.
Review residency descriptions across adviser communications, household records, and tax filings for accuracy. Consistency does not require identical language in every document; it requires avoiding conflicting accounts of the same facts. A Montreal property described as available for ongoing household use should not simultaneously be treated as irrelevant without explanation.
Before filing, cross-border advisers should assess citizenship, immigration status, retained Montreal housing, the location of a spouse and dependants, business ties, and any treaty position. Treaty rules can affect Canadian residency treatment when someone retains Canadian ties but is considered resident in another treaty country. That possibility requires analysis-not an assumption that the move automatically settles the issue.
A Canadian departure return can require reporting the departure date and addressing potential departure-tax consequences. Review the move timeline, calendar, and evidence file together rather than treating them as unrelated administrative tasks.
For the buyer, the result is a clearer distinction between acquiring a home and establishing a primary residence: a property that supports the intended life, and records that faithfully document it. Explore South Florida residences that fit your next chapter with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe purchase alone does not resolve U.S. or Canadian tax residency. Physical presence, residential ties, and the household's actual circumstances require separate review.
The test generally requires at least 31 current-year U.S. days and 183 weighted days across the current year and two preceding years, subject to applicable rules and exclusions.
The calculation counts all current-year U.S. days, one-third of the preceding year's days, and one-sixth of the second preceding year's days.
Yes. Prior-year days contribute to the weighted substantial presence calculation, so the current year's actual count is not the only consideration.
No. U.S. presence generally includes any day when a person is physically in the country at any time, subject to specified exclusions.
It generally requires fewer than 183 actual U.S. days, a foreign tax home, and stronger connections to the foreign country. Under the general rule, the foreign tax home must exist throughout the current year.
Taking steps toward lawful permanent-resident status, or having a pending application, can make the exception unavailable.
Not by itself. Significant Canadian residential ties, including a home, spouse or common-law partner, and dependants, remain important to the analysis.
Keep the move timeline, Montreal housing changes, household relocation evidence, and records of family and economic ties. Maintain a travel calendar covering arrivals, departures, physical presence, and overnight locations.
Advisers should assess citizenship, immigration status, retained housing, family and business ties, and treaty positions. A Canadian departure return can require a departure date and consideration of potential departure-tax consequences.