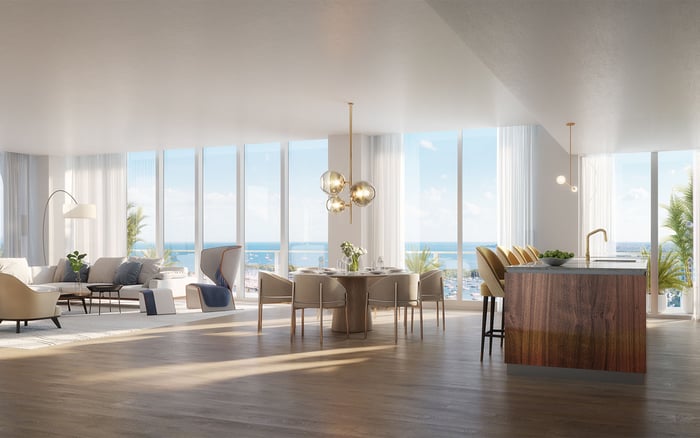
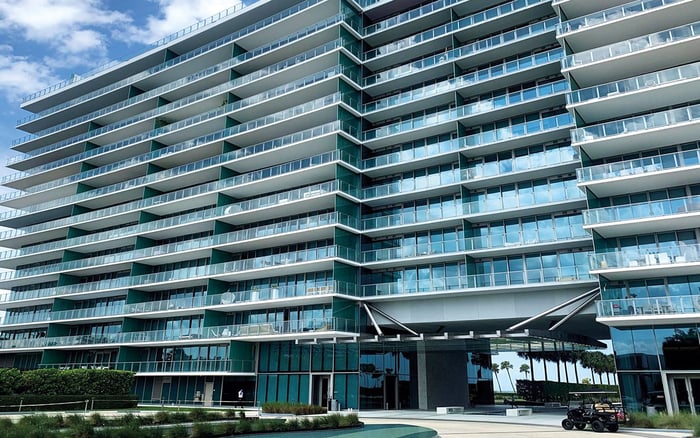
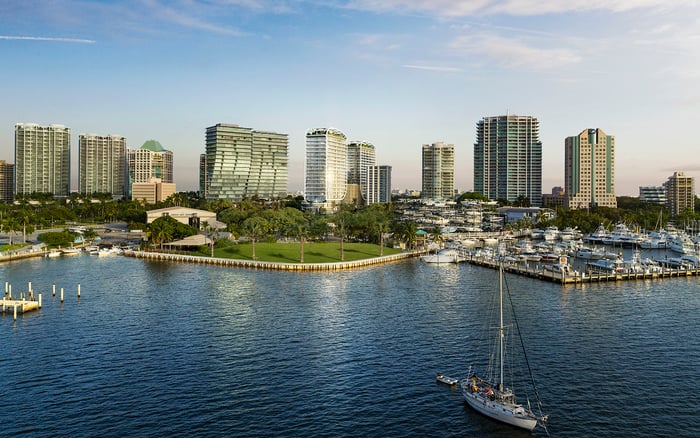
For a family dividing its life between Geneva and Key Biscayne, a considered residence strategy starts with intended use, precise deed vesting, and a coordinated review of trust, insurance, and succession documents. Florida homestead eligibility requires its own analysis, separate from the appeal of the address.
For a family moving between Geneva and Key Biscayne, choosing a residence is an exercise in continuity. The question is not simply where to spend the winter, but how the home fits within the family’s ownership arrangements, intended use, and succession plans. A considered strategy begins with documents that reflect the life being planned.
A buyer considering Oceana Key Biscayne should separate the appeal of the residence from the legal decisions surrounding it. Who will hold title? Is the property intended as a permanent Florida residence or a seasonal retreat? Which advisers will review the ownership structure before the deed is finalized?
These questions should come before assumptions about tax benefits or inheritance outcomes. The framework below addresses Florida homestead and trust-title considerations, while treating insurance and Swiss succession as matters for individualized professional review.
Miami-Dade homestead eligibility requires legal or equitable title as of January 1 of the applicable tax year. The property must also generally be the owner’s permanent Florida residence on that date. Purchasing a seasonal residence, however substantial the investment, does not by itself establish eligibility.
For a Geneva-based household, that distinction deserves an early conversation. An intention to spend more time in Florida does not confirm that the permanent-residence requirement has been met. Ask counsel to evaluate the actual circumstances rather than starting with a desired exemption outcome.
The standard homestead application deadline is March 1 of the tax year, and applications are filed with the county property appraiser. January 1 is the eligibility reference date; March 1 is the standard filing deadline. They are not interchangeable milestones.
A simple planning calendar can place those dates alongside the anticipated acquisition and any proposed title transfer. Use it to identify questions early, without assuming that a closing date alone establishes eligibility.
A signed trust instrument is not the same as a property titled to its trustee. Funding a revocable trust with Florida real estate normally requires a new deed transferring title from the individual owner to the trustee in that capacity. The transfer deed must be recorded with the county clerk.
Precision matters in the vesting language. It should identify the trustee, the trust’s name, and the trust’s date-not merely name the individual without trustee capacity. Ask the attorney preparing the deed to reconcile that language with the governing trust instrument before execution.
For a family also considering Coconut Grove, a residence at Park Grove Coconut Grove raises the same planning question: does the intended ownership arrangement appear correctly in the title documents? A different address does not eliminate that review.
As an administrative safeguard, request a closing-file checklist that includes the approved vesting language and, after recording, the recorded deed. This is a suggested organizational practice, not a substitute for counsel’s assessment of the transfer.
Property-tax homestead benefits and constitutional homestead protection are not interchangeable. A trust transfer requires careful drafting to preserve constitutional homestead protection; trust ownership should not be assumed sufficient on its own.
For property-tax eligibility, Miami-Dade requires a copy of the trust document when title is held in trust. Florida’s homestead application expressly asks whether the property is trust-held. The practical implication is straightforward: anticipate a review of the trust, not merely the name on the deed.
Ask Florida counsel to address two distinct questions: whether the arrangement supports the intended property-tax treatment, and whether the drafting preserves the relevant constitutional protection. Keep the answers separate in the family’s decision file.
Neither an attractive purchase nor a completed trust instrument resolves both questions on its own. The objective is an ownership arrangement reviewed for the particular residence and family-not one selected because trust ownership sounds inherently protective.
The first $25,000 of the homestead exemption applies to all property taxes, including school taxes. Separately, after the first year of homestead, Save Our Homes generally limits annual assessed-value increases to the lower of 3% or the annual CPI change.
That is a limit on assessed-value increases, not a promise that the total tax bill will rise by no more than 3%. Keep this distinction explicit when discussing long-term carrying costs.
Miami-Dade also provides online applications for homestead exemption and homestead assessment-difference portability. An application’s availability does not confirm that a particular owner qualifies. If portability is relevant to an existing Florida ownership history, make it a specific question for the adviser reviewing eligibility.
Insurance warrants a separate review; it is not an assumed consequence of signing the deed. Before approving an ownership arrangement, ask the insurance adviser to review the proposed title wording, intended occupancy, and any contemplated trust transfer against the actual policy terms.
Ask whether the policy needs any change to reflect trustee ownership, how the intended use should be described, and whether the proposed transfer calls for further underwriting review. These are questions for the insurer-not assertions that a particular endorsement or coverage outcome is universally required.
For buyers comparing Key Biscayne with Brickell and Una Residences Brickell, apply the same discipline. Seek property-specific advice rather than carrying assumptions from one potential purchase to another.
A Florida title plan does not establish conclusions about Swiss succession or cross-border taxation. Invite Florida and Swiss advisers to review the proposed residence ownership together, with the family’s objectives clearly stated.
Consider preparing a document inventory for that discussion: existing wills, trust instruments, proposed deed language, and any other documents the advisers identify as relevant. Ask which documents require review, whether changes are advisable, and how proposed changes should be coordinated before signing.
Frame the discussion around the family’s actual intentions. Who should benefit from the residence? Who does the family want to manage it if circumstances change? Are those intentions expressed consistently across the documents under review? Leave the assessment of their legal effect to the relevant advisers.
Before closing or transferring title, consider assembling a concise decision file covering intended use, approved vesting, trust documentation, insurance questions, and succession-review responsibilities. Assign each unresolved point to the appropriate professional so it is not lost between separate conversations.
The aim is not documentation for its own sake. It is a residence whose ownership has received the same care as its selection, with a clear distinction between established Florida requirements and matters requiring tailored advice. This framework is general information, not legal, tax, or insurance advice.
Explore a considered approach to South Florida residence selection with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Homestead generally requires the property to be the owner’s permanent Florida residence on January 1, along with legal or equitable title on that date.
The standard deadline is March 1 of the applicable tax year. Applications are filed with the county property appraiser.
Trust ownership requires an eligibility review rather than an automatic assumption of qualification. Miami-Dade requires a copy of the trust document when title is held in trust.
Funding normally requires a new deed transferring title from the individual owner to the trustee in that capacity. The deed must be recorded with the county clerk.
It should identify the trustee, the trust’s name, and the trust’s date. Naming the individual without trustee capacity does not express the intended trust vesting.
No. These require distinct consideration, and transferring a homestead into a trust requires careful drafting to preserve constitutional protection.
The first $25,000 applies to all property taxes, including school taxes.
After the first year of homestead, it generally limits annual assessed-value increases to the lower of 3% or the annual CPI change. It is not a matching cap on total tax-bill increases.
Ask the insurance adviser to review proposed title wording, intended occupancy, and any contemplated transfer against the actual policy terms. Do not assume a universal endorsement requirement or coverage outcome.
It should not be treated as doing so. Ask Florida and Swiss advisers to coordinate their review of the intended ownership and relevant succession documents.