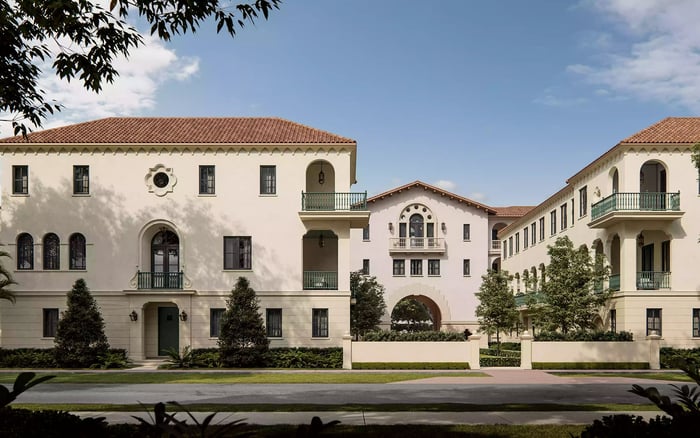
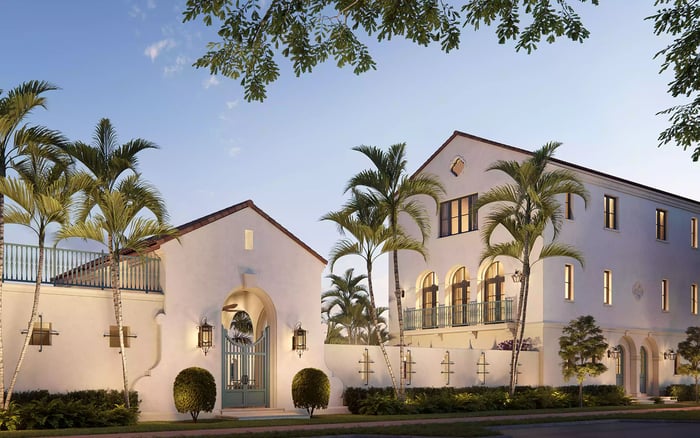
For a Houston buyer moving to Coral Gables, condominium diligence should connect statutory disclosures, engineering findings, reserve funding, and insurance history before contractual protections are waived.
Leaving Houston for Coral Gables is more than a change of address. For a condominium purchaser, it also means taking on shared capital obligations, building maintenance, and insurance exposure. A residence may meet every aesthetic requirement, but the association’s records reveal the commitments behind it.
If Ponce Park Coral Gables is on your shortlist, establish the transaction type and applicable disclosures before assuming a particular review framework applies. The resale process discussed here is not interchangeable with a developer purchase. Investment discipline begins with that distinction-not with assumptions about any named property’s condition or finances.
The central task is to connect four files: condominium documents, structural findings, reserve funding, and insurance history. None should be reviewed in isolation. The implications of a repair recommendation depend on whether funding is available, financing is unresolved, or coverage questions remain open.
Request the resale package promptly once under contract. Florida law entitles a contracted condominium purchaser to specified current documents at the seller’s expense, including governing documents, financial information, and applicable inspection and reserve-study disclosures.
The package must include the inspector-prepared milestone inspection summary, if applicable, and the association’s most recent structural integrity reserve study, or a statement that it has not completed one. That statement does not resolve whether the building must have a study or which requirements currently apply.
Have Florida counsel reconcile statutory document-delivery and cancellation provisions with the purchase contract. Ask counsel to calculate deadlines before waiving protections. Record what arrived, when it arrived, and which questions remain unanswered.
For a buyer considering Cora Merrick Park alongside other options, apply the same discipline: establish the purchase structure, identify the applicable document package, and distinguish mandatory delivery from additional requests. Request insurance histories and complete engineering files as diligence; do not presume they are automatic seller-delivery obligations.
Confirm the building’s age and number of habitable stories early. Florida’s milestone-inspection and structural integrity reserve-study requirements principally concern condominium and cooperative buildings at least three habitable stories tall.
Covered buildings generally require an initial milestone inspection at 30 years and subsequent inspections every 10 years, subject to applicable statutory and local requirements. Do not apply a universal coastal age trigger or assume one deadline governs every building. Ask counsel and the appropriate technical adviser to confirm the requirements for the specific property.
The statutory milestone summary is a starting point, not a complete engineering review. Request the full inspection report, repair recommendations, any phase-two findings, board responses, and evidence of completed work.
The practical question is whether each material finding has a documented resolution. For work that remains open, identify the scope, expected timing, and funding. Review pending disputes, repair claims, warranties, and remediation commitments alongside the findings. A promise to address an issue is not evidence that it has been addressed.
A completed structural integrity reserve study and an adequately funded repair plan are separate questions. Florida’s deadlines and funding rules have changed over time, so verify current requirements rather than relying on an older explanation in a sales conversation or meeting record.
Review the study’s treatment of roofs, structural systems, fireproofing, plumbing, electrical systems, windows, and waterproofing. An aggregate reserve balance can obscure the timing and scale of individual obligations.
For each significant component, compare remaining useful life and estimated replacement cost with available cash, restricted funds, deferred maintenance, and planned projects. Connect those figures to the current and proposed budgets. The objective is to determine whether money is expected to be available when the work is expected to occur.
Request explanations where engineering recommendations and the financial plan do not align. A study may identify an expense not yet clearly reflected in the budget. Conversely, funds reserved for one purpose should not be assumed available for another. Obtain written clarification rather than resolving discrepancies through assumptions.
The monthly association charge is only one part of the ownership commitment. Request board and owner-meeting minutes, budget notices, assessment resolutions, and relevant engineering correspondence to identify assessments already approved or under discussion.
Separate approved obligations from proposals. Record each obligation’s purpose, payment schedule, and unresolved questions, then have counsel review how the contract allocates responsibility between buyer and seller.
Ask about association loans, credit facilities, and other payment arrangements. Repair financing can make the immediate cash requirement appear manageable while affecting future assessments or monthly charges. Review the financing alongside the work it supports, not as an isolated balance-sheet item.
For a relocation buyer coordinating a Houston departure, this review should proceed alongside moving arrangements-not wait until they are fixed. An unanswered capital question deserves attention before the closing schedule becomes the dominant consideration.
The budget’s insurance line does not explain the master policy. Request declarations, coverage limits, exclusions, deductibles, carrier information, and renewal terms. Have an insurance professional review those materials independently of the association’s financial presentation.
Then request prior policies, claims summaries or loss runs, renewal proposals, and cancellation or nonrenewal notices as additional diligence. Read that history alongside engineering records and repairs to identify matters requiring clarification. Do not assume every historical insurance document belongs in the statutory resale package.
Clarify how wind, water, flood, and named-storm deductibles or uninsured losses could become owner obligations under the governing documents and applicable law.
The association’s policy does not replace the buyer’s coverage review for personal property, interior improvements, liability, and loss assessments. Ask about HO-6 coverage and deductible reimbursement as policy-specific questions. Neither should be treated as guaranteed protection, and experience with a Houston policy should not substitute for reviewing the Florida property’s actual terms.
Before closing, compare the milestone findings, reserve study, budgets, assessment history, meeting minutes, and insurance documents. Assign unresolved legal, engineering, and coverage questions to the relevant adviser and obtain written answers.
If The Village at Coral Gables remains under consideration, apply this reconciliation to the specific residence and ownership structure rather than drawing conclusions from the project name. Apply the same principle across the shortlist: compare documented obligations, not simply finishes and monthly charges.
A well-coordinated review does not promise an obligation-free purchase. It gives the buyer a clearer basis for deciding which commitments are acceptable, which require clarification, and which should affect the decision to proceed.
Explore your Coral Gables residential options with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationRequest the statutory resale documents promptly once under contract. Have Florida counsel review delivery requirements and cancellation deadlines alongside the purchase contract.
The inspector-prepared summary of the milestone inspection report must be included if applicable. Request the complete inspection report separately for a fuller review.
Required resale documents include the association’s most recent structural integrity reserve study, or a statement that it has not completed one. Counsel should help confirm the building’s applicable requirements.
The requirements principally concern condominium and cooperative buildings at least three habitable stories tall. Confirm applicability for the specific building rather than assuming a universal rule.
Covered buildings generally require an initial inspection at 30 years and subsequent inspections every 10 years. Applicable statutory and local requirements must be checked.
No. Compare the study’s component costs and timing with available reserves, restricted funds, budgets, and the association’s repair-funding plan.
Request meeting minutes, budget notices, assessment resolutions, and engineering correspondence. Distinguish approved assessments from proposals still under discussion.
Loans, credit facilities, and payment arrangements can affect future assessments or monthly charges even when immediate cash demands appear manageable.
Do not assume it is. Request prior policies, loss runs or claims summaries, renewal proposals, and cancellation or nonrenewal notices as additional diligence.
No. Review personal property, interior improvements, liability, and loss-assessment coverage separately, and treat HO-6 deductible reimbursement as a policy-specific question.