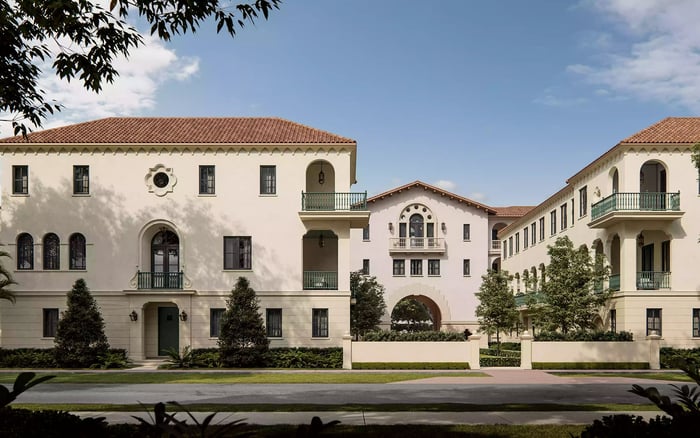
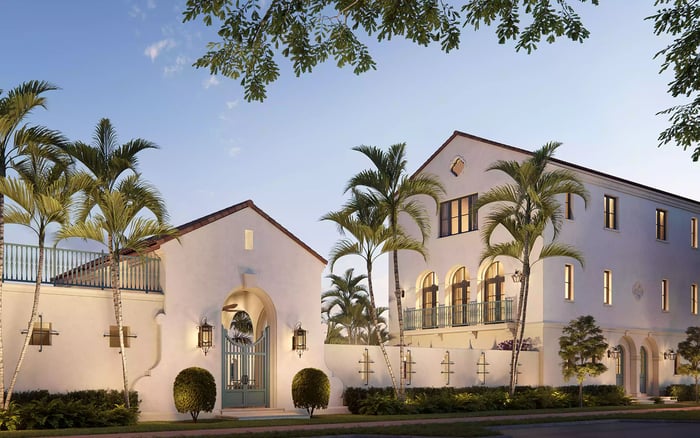
A private-client guide to aligning Coral Gables ownership, permanent residency, homestead filing and deed decisions, with a clear distinction between Florida portability and California assessment benefits.
A move from Los Angeles to Coral Gables involves more than selecting an address. For a household establishing a permanent Florida residence, the acquisition calendar, homestead application and ownership structure warrant coordinated attention before closing. The essential distinction is straightforward: buying a home does not, by itself, establish eligibility for Florida’s property-tax homestead benefits.
Whether the search includes Ponce Park Coral Gables or another residence, separate the property decision from the eligibility determination. A home may meet the family’s lifestyle requirements well before the household establishes permanent Florida residency.
For private clients, the objective is not simply to complete an application. It is to align the facts of residence, the deed and the tax-year calendar so that the expected benefits rest on a defensible foundation.
Florida homestead eligibility requires ownership and permanent residence, either for the owner or a legal or natural dependent. January 1 is the key eligibility date: the applicant generally must own the property and have established permanent Florida residency by that date for the relevant tax year.
The standard application deadline is March 1 of the applicable tax year. The dates serve different purposes: January 1 concerns eligibility; March 1 concerns filing. Meeting the filing deadline does not replace the need to satisfy the ownership and residency requirements.
A buyer who closes before relocating should not treat the closing date as the automatic start of homestead eligibility. Nor should an anticipated move be treated as an established residence. Have the household’s actual timeline reviewed before factoring an exemption into the ownership budget.
Second-home planning requires particular care. A property initially intended for occasional use should not be assumed to qualify merely because the owner expects to make it a permanent home later.
Residency evidence can include Florida identification, voter and vehicle registrations, a declaration of domicile, federal tax information and records concerning the prior permanent residence. The task is to assemble a coherent account of the relocation, not rely on a single document as a substitute for the underlying facts.
Keep the purchase and residency files connected. Before filing, review when ownership began, when permanent residence was established and whether the supporting records accurately reflect those events. If the Los Angeles home remains in the family’s portfolio, records concerning that prior residence may still be relevant to the application.
Coral Gables homeowners apply through the Miami-Dade County Property Appraiser, which accepts online homestead and portability applications. Confirm the applicable documentation requirements and retain the submitted application and supporting materials. Make filing a defined part of closing-stage planning, rather than leaving it until the deadline approaches.
The homestead exemption and Save Our Homes perform different functions. The exemption reduces taxable value. Save Our Homes generally limits annual increases in assessed value after homestead is established to the lower of 3% or the applicable Consumer Price Index change.
That distinction matters when reviewing a residence at The Village at Coral Gables. The question is not simply whether homestead benefits exist, but which benefit the purchaser may qualify for and when it becomes relevant.
The assessment limitation is not a promise that the entire property-tax bill can rise by no more than 3%. Its function is to limit assessed-value increases. Keep the exemption, assessed value and ultimate tax liability distinct when reviewing projected carrying costs.
For a relocating owner without a qualifying former Florida homestead, the relevant path is a new Florida homestead exemption and the subsequent Save Our Homes limitation-not the continuation of a California assessment history.
A seller’s historical assessment can be an unreliable guide to the purchaser’s future position. A qualifying ownership change generally triggers reassessment at just value the following January 1. Buyers should not assume that the seller’s accumulated Save Our Homes assessment advantage will survive the acquisition.
For a resale purchase, ask the advisory team to distinguish the existing owner’s assessment from the assumptions appropriate to the incoming owner. The seller’s tax bill is useful background, but it should not become the buyer’s operating budget without review.
This is especially important when a transaction and relocation straddle January 1. The acquisition, reassessment and homestead questions belong on the same timeline, even though each addresses a different aspect of ownership.
A Los Angeles homeowner cannot transfer a Proposition 13 assessment benefit into a Coral Gables property. Florida portability concerns an eligible assessment difference from a qualifying former Florida homestead, not savings accumulated on a California residence.
Portability can transfer up to $500,000 of the eligible difference between the former Florida homestead’s market value and assessed value. That amount is an assessment-transfer ceiling, not a cash payment or a dollar-for-dollar property-tax credit. It should not be presented as guaranteed tax savings.
The new Florida homestead must be established within the applicable three-assessment-year window. A client arriving from Los Angeles should investigate portability only if there is also a qualifying prior Florida homestead within the permitted period.
The exemption itself does not transfer, even between Florida homes. A new homestead application, Form DR-501, is required. Where portability applies, Form DR-501T accompanies that application, generally by March 1 of the applicable tax year. Have the former property’s eligibility, timing and transferable difference reviewed rather than assuming the maximum applies.
Ownership planning belongs before recording, not after the household has assumed a particular tax outcome. Whether considering individual ownership, a revocable trust, an LLC or a marital deed arrangement, request a property-specific review of the proposed structure and its implications for the intended homestead claim.
For a purchase at Cora Merrick Park, the same discipline applies: establish the intended ownership arrangement alongside the residency and filing plan. Project selection does not resolve the title question.
Later deed restructuring also warrants review. Ownership changes can affect an existing Save Our Homes assessment, and qualifying changes generally lead to reassessment. That does not mean every title amendment produces the same result. Ask counsel to assess the proposed instrument before it is recorded.
The final checklist is compact: confirm January 1 eligibility, calendar March 1, assemble residency evidence, test any prior Florida homestead for portability and review the deed before execution. This discussion concerns property-tax benefits, not separate creditor-protection or inheritance rules, and is not individualized legal or tax advice.
For a considered approach to your Coral Gables property search, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Eligibility requires ownership and permanent residence for the owner or a legal or natural dependent, not simply a completed purchase.
The applicant generally must own the property and have established permanent Florida residency by January 1 for the relevant tax year.
The standard deadline is March 1 of the applicable tax year. Filing on time does not replace the January 1 eligibility requirements.
They apply through the Miami-Dade County Property Appraiser, which accepts online homestead and portability applications.
Evidence can include Florida identification, voter and vehicle registrations, a declaration of domicile, federal tax information and records concerning the prior permanent residence.
The exemption reduces taxable value. Save Our Homes generally limits annual assessed-value increases after homestead is established to the lower of 3% or the applicable Consumer Price Index change.
No. Florida portability requires an eligible assessment difference from a qualifying former Florida homestead; California assessment benefits cannot be imported.
No. It is the maximum eligible assessment difference that may transfer, not a cash payment or a dollar-for-dollar property-tax credit.
The new Florida homestead must be established within the applicable three-assessment-year window. Form DR-501T is filed with the new homestead application, Form DR-501, generally by March 1 of the applicable tax year.
Yes. Qualifying ownership changes generally trigger reassessment, but not every title amendment automatically does so; review the proposed change before recording.