Choosing between Miami Beach and Palm Beach requires more than comparing monthly dues. A disciplined review of service obligations, structural reserves, association borrowing, and assessment timing reveals the economics behind the lifestyle.
Waterfront ownership should make life feel simpler. The financial structure behind that ease deserves scrutiny. Between Miami Beach and Palm Beach, the meaningful comparison extends beyond monthly association charges to the relationship between services, accumulated reserves, anticipated repairs, and obligations that may arrive after closing.
Neither municipality offers an automatic advantage in condominium finances. Both share Florida’s statewide inspection and reserve framework; the actual exposure rests with the individual building. A lower recurring assessment is not, by itself, evidence of better value. A higher one demands a clear explanation of what it funds.
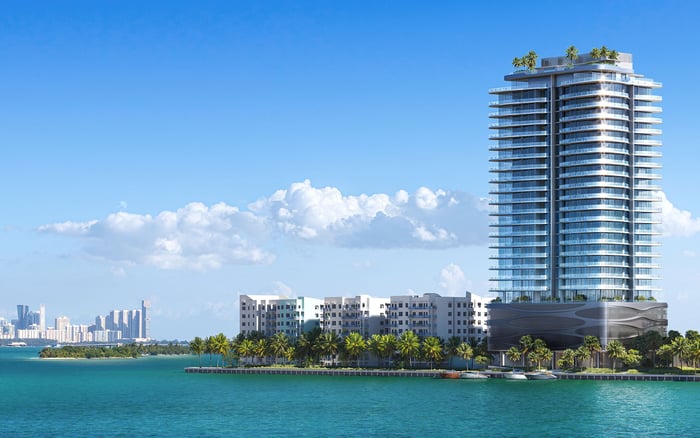
For a buyer considering 57 Ocean Miami Beach, the next step is a building-specific financial review, not an assumption based on the address. Apply the same discipline to every Palm Beach candidate. Let lifestyle establish the shortlist; let documented obligations determine which residence merits the commitment.
An amenity matters financially in two ways: what it costs to use and what an owner must contribute to sustain it. Those amounts are not interchangeable.
For each candidate, classify valet, parking, beach services, clubs, golf, tennis, marina access, and hospitality services as mandatory, optional, separately billed, or inapplicable. Then ask whether declining a service also removes its operating and capital charges. Never assume non-use creates an exemption.
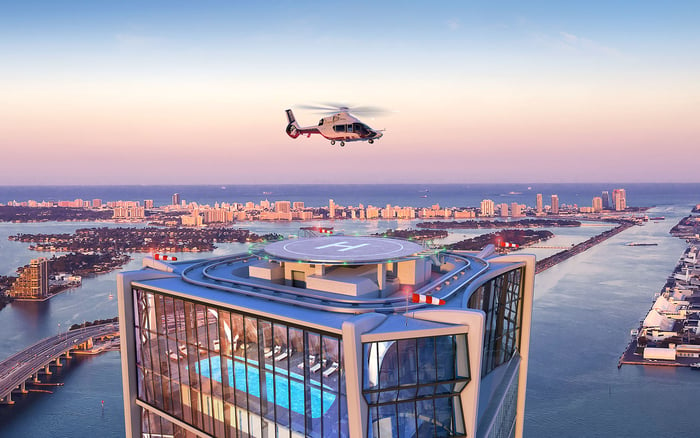
When evaluating Setai Residences Miami Beach, request the applicable service agreements and charge schedule rather than inferring the financial arrangement from the residential name. The same question belongs in every comparison: which costs follow ownership, and which follow personal consumption?
This distinction is especially useful when two residences appear to offer similar convenience. One buyer may willingly pay for extensive services; another may prefer fewer commitments. The objective is not the smallest service budget, but a clearly understood one that reflects how the residence will be used.
Build a single annual ownership schedule for each residence. Include regular assessments, separately billed amenities, property taxes, owner insurance, utilities, parking, and scheduled special assessments. Identify what dues already include so that insurance, services, or debt payments are not counted twice.
Keep three categories visible: recurring ownership costs, discretionary usage, and scheduled capital payments. A single total is useful, but the categories reveal which expenditures are adjustable and which are unavoidable.
For a Palm Beach shortlist that includes Palm Beach Residences, use the same categories and comparison period as for Miami Beach. Consistency makes the comparison meaningful without implying that either location has lower average costs.
Model the upcoming year alongside the disclosed multiyear funding schedule. A temporarily modest payment should not obscure a later contribution increase, assessment installment, or borrowing obligation. For a seasonal owner, the key question is what remains payable while the residence is unoccupied.
A milestone inspection and a Structural Integrity Reserve Study, or SIRS, answer different questions. The inspection evaluates structural condition. The SIRS estimates funding needs for covered building components. Neither substitutes for the other.
Residential condominium buildings of three or more habitable stories generally fall within the milestone framework, with a standard age trigger of 30 years and recurring inspections thereafter. Confirm the schedule for the particular building rather than relying on a generalized coastal-age rule.
For owner-controlled associations existing on or before July 1, 2022, the general initial SIRS deadline was December 31, 2025, for qualifying buildings of three or more stories. Associations required to complete a milestone inspection by December 31, 2026, may complete the SIRS concurrently, but no later than that date.
Covered components include roofs, structural systems, waterproofing, plumbing, and electrical systems. Substantial structural deterioration identified through a Phase Two milestone inspection can require repairs and additional association spending. These rules concern qualifying condominium and cooperative buildings; they do not automatically apply to every single-family HOA, estate, or private club.
A completed SIRS is not proof that repairs are funded. Compare its estimated needs and timing with accumulated reserves, the adopted funding plan, and outstanding work. A reserve balance is meaningful only when measured against the obligations it must meet.
Ask management to distinguish accumulated reserve cash from borrowed funds. Florida’s 2025 condominium-law changes permit loans, lines of credit, or special assessments for reserve funding, subject to applicable approval requirements. Borrowing can leave owners with future debt-service exposure; it does not eliminate the underlying cost.
Under specified conditions, associations completing a milestone inspection may pause or reduce reserve contributions for up to two consecutive budgets, subject to a member vote and additional requirements. If a budget reflects that relief, ask what contributions are expected afterward. Temporary relief is not evidence of permanently lower ownership costs.
The additional reserve-item threshold increased from $10,000 to $25,000 under the 2025 changes, with annual inflation adjustments. This is not a blanket exemption for smaller expenses involving specifically listed structural components. Have counsel confirm how the applicable requirements affect the building’s plan.
Request the current budget, financial statements, board minutes, SIRS, milestone inspection findings, repair-completion evidence, insurance documents, assessment notices, and association debt details. Read them together. The budget shows planned collections; the structural and reserve documents help explain the obligations behind them.
For identified work, establish whether it is proposed, approved, underway, or completed. Ask how it will be funded and which amounts are already reflected in regular assessments. Distinguish approved liabilities from possible future spending without dismissing either.
Review association borrowing separately, focusing on payment schedules and how debt service is passed to owners. Examine insurance documents alongside the budget to understand the association’s coverage and the owner’s separate insurance needs.
Before signing or closing, have Florida condominium counsel address responsibility for assessments approved before closing but payable afterward. That allocation belongs in the transaction documents, not in an informal understanding between buyer and seller.
The stronger purchase is not necessarily the residence with the lowest dues. It is the one whose service obligations, structural condition, reserve resources, and future payments are clear enough for the buyer to make a deliberate commitment.
Choose Miami Beach or Palm Beach for the life you intend to lead. Choose the building only after understanding the financial obligations that accompany that life.
Explore residences aligned with your lifestyle and ownership priorities with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNeither municipality provides an automatic advantage. Compare each building’s obligations, reserves, structural condition, and funding plan rather than relying on its location.
Include regular assessments, separately billed amenities, property taxes, owner insurance, utilities, parking, and scheduled special assessments. Avoid counting any expense already included in dues twice.
Not necessarily. Confirm whether opting out removes only usage charges or also any operating and capital obligations attached to ownership.
A milestone inspection evaluates structural condition. A Structural Integrity Reserve Study estimates funding needs for covered building components.
Residential condominium buildings of three or more habitable stories generally fall within the framework, with a standard age trigger of 30 years and recurring inspections thereafter. Confirm the particular building’s applicable schedule.
For qualifying owner-controlled associations existing on or before July 1, 2022, the general deadline was December 31, 2025. An association required to complete a milestone inspection by December 31, 2026, may complete its SIRS concurrently, no later than that date.
No. Compare the study’s estimated needs and timing with accumulated reserves, the adopted funding plan, and outstanding work.
Florida’s 2025 changes permit loans, lines of credit, or special assessments for reserve funding, subject to applicable approval requirements. Borrowing can create future debt-service exposure for owners.
Under specified conditions, an association completing a milestone inspection may pause or reduce contributions for up to two consecutive budgets, subject to a member vote and additional requirements. Review the expected contributions after that relief ends.
Florida condominium counsel should address the buyer’s and seller’s responsibilities in the transaction documents. Do not leave the allocation to an informal understanding.