A Tokyo-to-Key Biscayne relocation requires more than a closing. Align permanent-residence evidence, departure records, ownership structure, and Florida’s first property-tax calendar before assuming homestead relief.
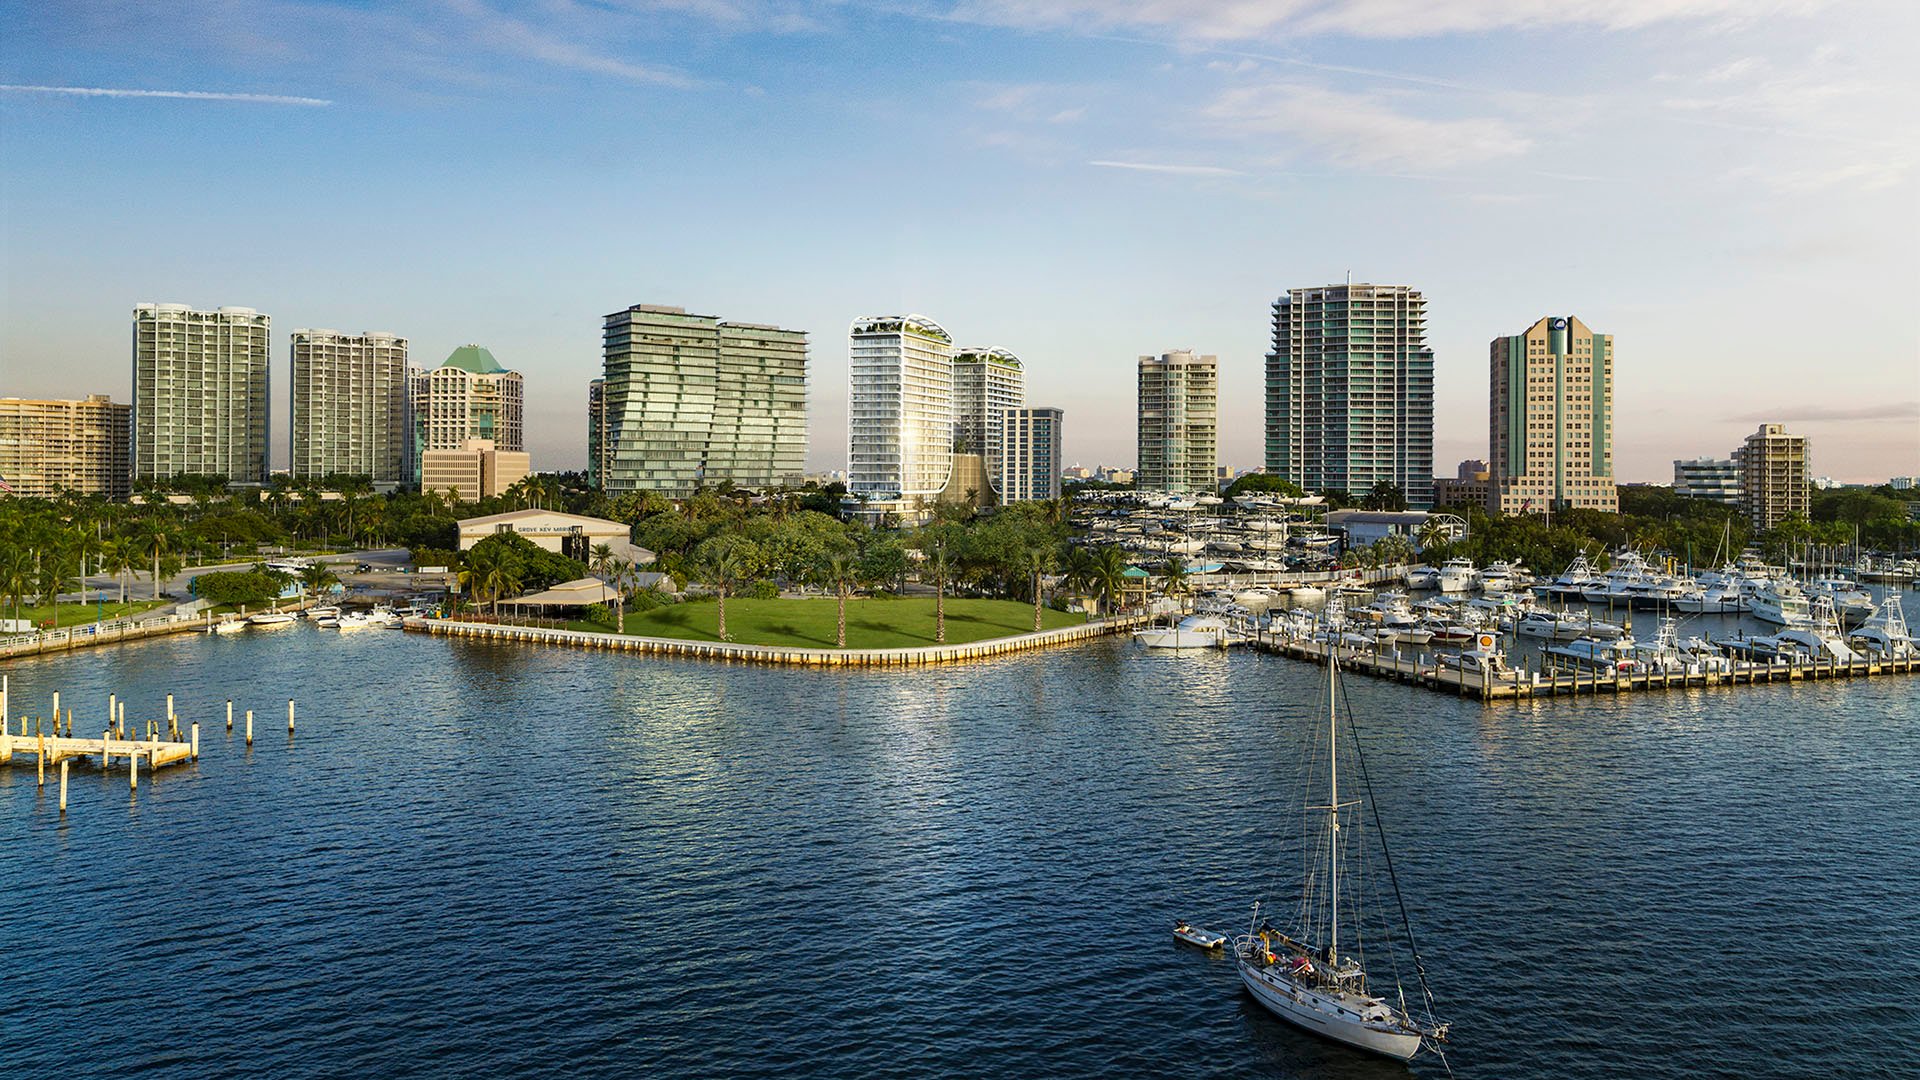
For a family office coordinating a move from Tokyo to Key Biscayne, selecting the residence is only part of the transition. The more consequential task is to align ownership, actual permanent residence, and the documentation supporting both. A completed purchase does not, by itself, establish Florida homestead eligibility.
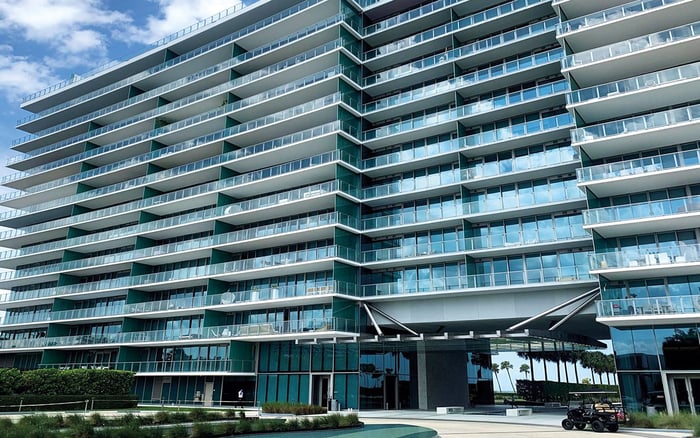
Even when the search centers on Oceana Key Biscayne, the family’s acquisition calendar should run alongside a separate residency calendar. Closing, occupancy, identification changes, and exemption filing are distinct events. Treating them as interchangeable can obscure the first year’s property-tax position.
The objective is a coherent record of the move, not merely a collection of Florida addresses. For a household retaining international connections, that distinction warrants attention before closing-not after the first tax notice arrives.
Florida generally assesses and values property as of January 1. Homestead eligibility generally requires qualifying ownership and permanent residence on that date, whether the residence is the eligible owner’s permanent home or that of a qualifying dependent.
The standard application deadline is March 1 for the relevant tax year, subject to limited exceptions. The dates serve different purposes: January 1 governs eligibility and assessment; March 1 governs filing. Meeting the filing deadline does not substitute for satisfying the January 1 requirements.
A purchase after January 1 generally makes the following January 1 the critical eligibility date for the buyer’s own homestead claim. The family office should distinguish the acquisition-year budget from the later year in which the buyer may qualify for relief.
Before settling the ownership structure, obtain advice on the proposed title. Do not assume that an entity-owned residence qualifies. Coordinate acquisition and exemption planning without treating a family-office purchasing vehicle as automatically suitable for homestead purposes.
No single residency factor is conclusive. A recorded declaration of domicile is relevant evidence, but it does not replace the broader facts showing an intention to establish permanent residence.
Build the file around dated, applicable records:
A declaration of domicile and its recording date.
Florida driver-license or identification documentation, with prior U.S. state license surrender where relevant.
Florida vehicle-registration information and voter-registration information where applicable; voter registration applies only to U.S. citizens.
The address on the latest federal income-tax return and mailing addresses for bank statements and checking accounts.
Current employer information, dependent children’s school location, and evidence of utility payments at the homestead address.
These indicators do not substitute for actual residence. They should accurately reflect the household’s circumstances, including the timing of changes. Place documents updated at different stages of the relocation in a chronology rather than presenting every change as though it occurred on closing day.
The internal review should ask a clear question: do the records tell a consistent story about when Key Biscayne became the permanent home?
The homestead application asks about previous residency outside Florida and the date it terminated. For a Tokyo departure, lease-surrender papers, sale-closing records, and utility-termination confirmations can corroborate the transition where those events occurred. They are not a separately prescribed Florida checklist.
Departure evidence should not be read as a universal requirement to sell every residence outside Florida. The task is to document the actual transition and explain retained connections accurately-not manufacture a cleaner-looking history.
The phrase “state-exit documentation” requires particular care here. Tokyo is not a U.S. state. Surrender of another state’s driver license matters only where applicable. Japanese departure filings and any separate U.S. state tax-exit obligations require their own review; the Florida homestead process does not establish those requirements.
Likewise, homestead approval does not resolve Japanese tax residence, U.S. immigration status, federal taxation, or a family office’s corporate-management questions. Keep those advisory assignments separate while ensuring their underlying factual timelines remain consistent.
A broader search may include Park Grove Coconut Grove. If Coconut Grove remains an alternative to Key Biscayne, the comparison should extend beyond the residences themselves to realistic acquisition and occupancy schedules, proposed ownership arrangements, and the evidence available for the intended permanent home.
The same discipline applies when considering Una Residences Brickell. Evaluate a Brickell option on its own facts, without assuming that a preferred address or signed purchase agreement establishes residency.
For each candidate, ask the advisers to identify the relevant January 1, the intended applicant, and the proposed title structure. This connects the residential decision to the family’s practical timetable without implying that any particular project guarantees an exemption.
Do not assume that the seller’s homestead exemption and Save Our Homes assessment benefit transfer automatically with the property. A historic tax bill can inform the discussion, but it should not become the buyer’s unexamined assumption for recurring costs.
Save Our Homes is an assessment limitation, not a freeze on the tax bill. Homestead property continues to be reassessed annually on January 1. Keep assessed value, exemptions, and the eventual amount payable distinct in the family office’s budget.
Key Biscayne is a separate taxing authority within Miami-Dade’s property-tax structure. Use the adopted millage schedule for the applicable tax year rather than carrying an older rate into a new forecast. Confirm exemption amounts for that tax year as well, rather than relying on a familiar headline figure.
Assign responsibility for four distinct milestones. January 1 establishes the assessment date and relevant homestead eligibility facts. March 1 is the standard exemption filing deadline. August ordinarily brings the Notice of Proposed Property Taxes, commonly called the TRIM notice. The subsequent tax-bill and payment cycle requires its own follow-through.
The TRIM notice is not the final bill. Review its values, exemptions, proposed taxes, and public-hearing information rather than simply forwarding it for payment. Retain the homestead filing receipt alongside the documents supporting the application.
Maintain one dated chronology connecting Tokyo departure, purchase, Key Biscayne occupancy, declaration recording, identification changes, utilities, banking, and filing. Assign a family-office team member to maintain it and coordinate questions with the appropriate advisers.
A well-managed move does not compress every legal question into a Florida address. It gives the household a documented residential transition and a clear first-year tax calendar.
For a discreet discussion of your South Florida residential search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Eligibility generally requires qualifying ownership and permanent residence on January 1; a purchase alone does not satisfy those requirements.
Florida generally assesses and values property on January 1. It is also the critical date for qualifying ownership and permanent residence for homestead purposes.
The standard deadline is March 1 for the relevant tax year, subject to limited exceptions.
The following January 1 generally becomes the critical eligibility date for the buyer’s own homestead claim. The acquisition-year budget should be considered separately.
No single residency factor is conclusive. A recorded declaration is relevant evidence considered alongside the household’s other circumstances.
Lease-surrender, sale-closing, and utility-termination records can corroborate departure where applicable. They are practical supporting documents, not a separately prescribed Florida checklist.
Departure documentation should not be treated as a universal requirement to sell every outside residence. The file should accurately document the transition and any retained connections.
No. Japanese tax residence, U.S. immigration status, federal taxation, and family-office corporate-management questions require separate review.
Buyers should not assume that the seller’s exemption or assessment benefit automatically transfers. Save Our Homes limits assessment changes; it does not freeze the tax bill.
Review values, exemptions, proposed taxes, and public-hearing information. The TRIM notice is not the final tax bill.