For Aspen-based buyers establishing a Surfside residence, the most consequential decisions begin before closing. Coordinate deed vesting, trust provisions, homestead eligibility, insurance and succession documents as one plan rather than separate administrative tasks.
A Surfside residence can give an Aspen household a different seasonal rhythm without changing its legal home. The purchase nevertheless calls for more than a property search and a signing appointment. Who owns the residence, who can act during incapacity and who receives it at death should be considered together before the deed is prepared.
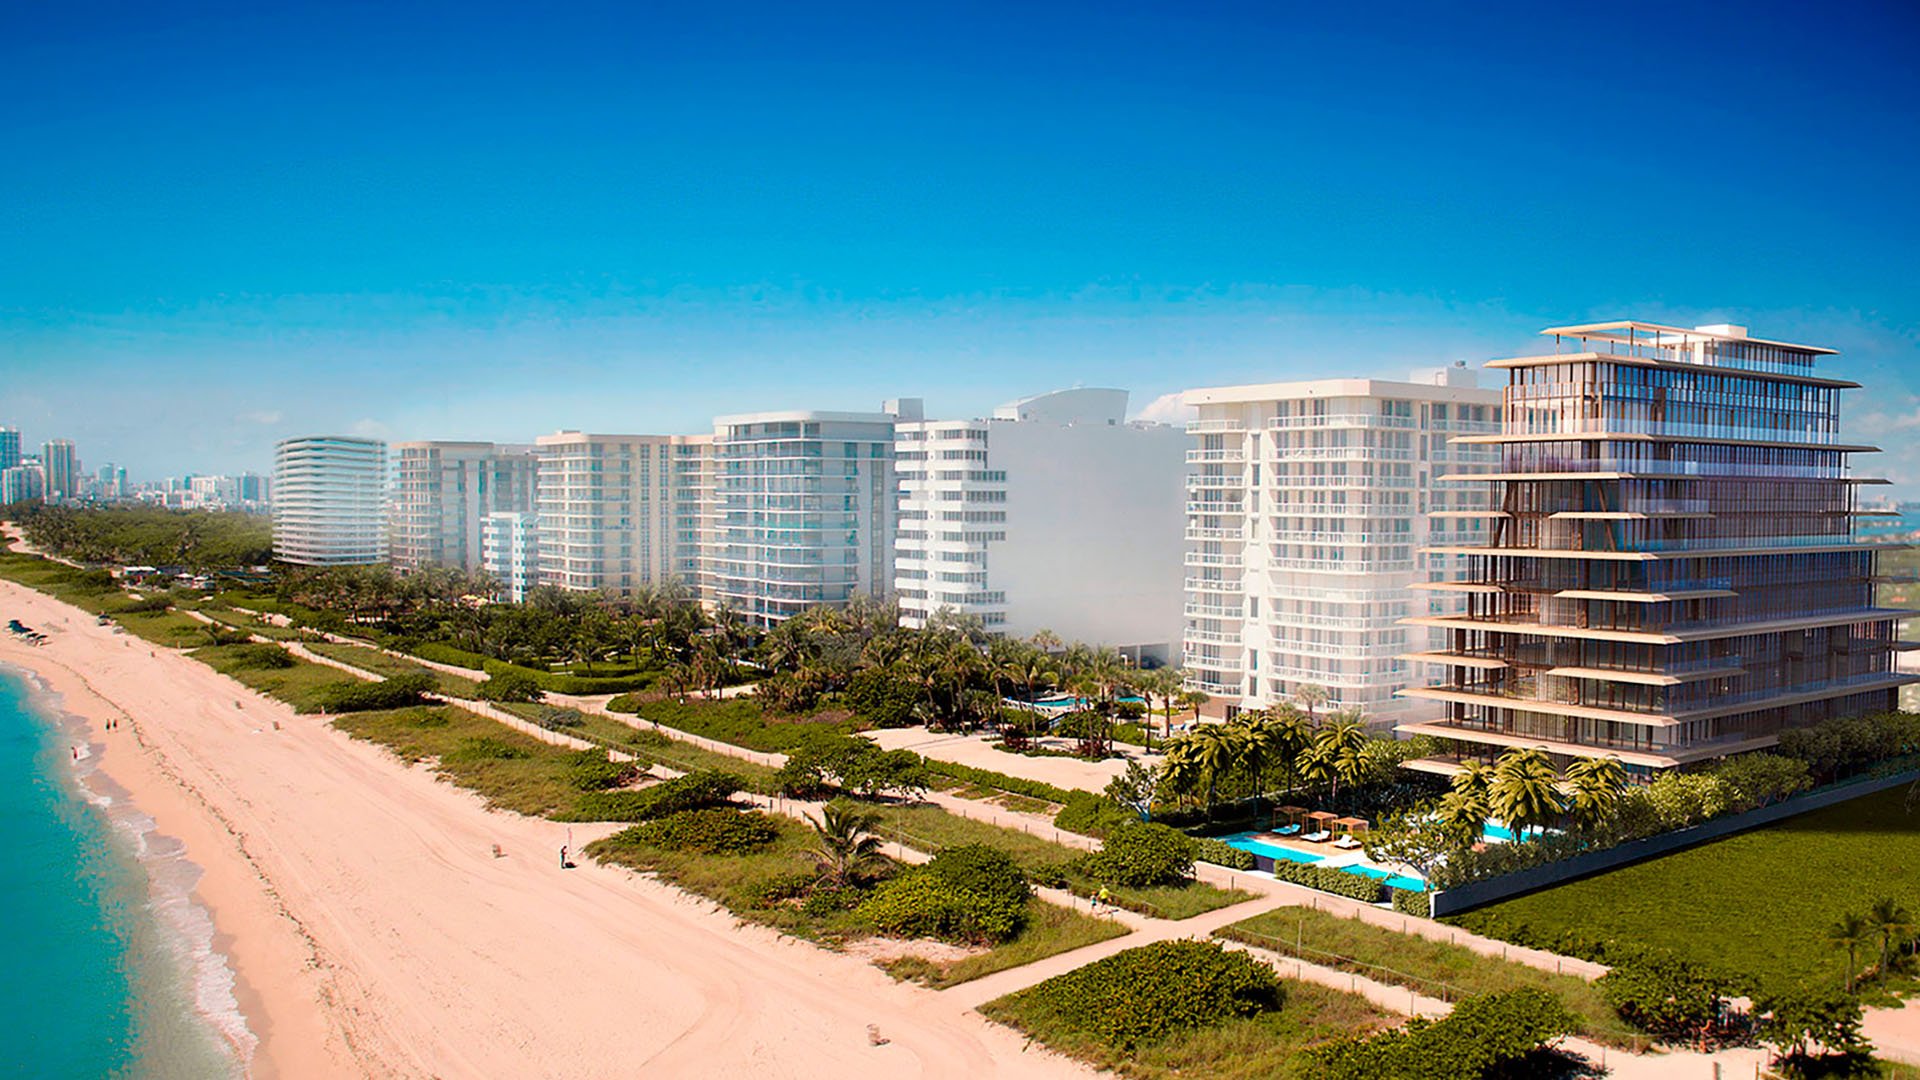
For a buyer considering The Surf Club Four Seasons Surfside, the essential questions extend beyond personal preferences: will the residence remain a seasonal base, might it become a permanent home, and how should it fit within the family's existing estate plan? Second-home ownership and a permanent-residence strategy are not interchangeable.
The most useful pre-closing exercise is a coordinated review with the buyer's Colorado estate counsel, Florida counsel, closing team and insurance adviser. The objective is not necessarily a new estate plan, but an ownership arrangement that works with the existing one.
Deed vesting identifies how title will be held. A revocable trust may simplify incapacity and succession administration, but the existence of a trust does not, by itself, mean that a newly purchased residence is covered by it. The deed and the trust's provisions must support the intended arrangement.
Before closing, ask counsel to review the proposed title holder, the relevant trust terms and the person expected to act if the buyer becomes incapacitated or dies. That review should distinguish present ownership and occupancy rights from future inheritance expectations.
For a household evaluating Arte Surfside, the question is not simply whether to buy in a trust. It is whether the proposed vesting, authority provisions and succession instructions work together for this purchase. No ownership structure should be selected solely for its apparent administrative convenience.
Ask the legal team to explain the proposed structure in plain language: who controls the property now, who may occupy it and what changes when the current decision-maker can no longer act.
Closing personally and transferring the residence into a trust or entity afterward is not routine housekeeping. Florida provides no specific documentary stamp-tax exemption merely because a real-estate transfer serves an estate-planning purpose.
Tax exposure can depend on consideration, mortgages, assumed debt and the transfer structure. A transfer intended to simplify succession may therefore require a separate tax review. Neither the family purpose of the transaction nor the absence of an ordinary sale determines the outcome on its own.
Ask advisers to compare the intended closing structure with any anticipated later transfer before approving the deed. If the plan is likely to change, clarify what must be reviewed again rather than assuming the second deed will be a neutral administrative step.
For an Aspen-based buyer, the first homestead question is whether the Surfside property will meet qualifying permanent-residence requirements. Do not assume a seasonal residence is eligible for the homestead tax exemption simply because it is owned personally or used regularly.
Trust ownership does not automatically prevent tax eligibility. The applicant may qualify with the required beneficial or equitable interest and a present right to occupy the home. Being only a future or contingent beneficiary does not necessarily establish that present possessory right.
Maintaining an exemption after a trust transfer may also require supporting documents and appropriate language in both the trust and deed. Confirm the applicable Miami-Dade requirements directly; another county's documentation guidance should not be treated as the local filing procedure.
The broader distinction is equally important: homestead tax treatment, creditor protection and transfer-at-death restrictions are separate legal questions. An answer in one category does not settle the others. Spousal rights and homestead devise restrictions can constrain a proposed succession arrangement, including one involving a trust. Transferring homestead property into a revocable trust may also jeopardize creditor protection in bankruptcy.
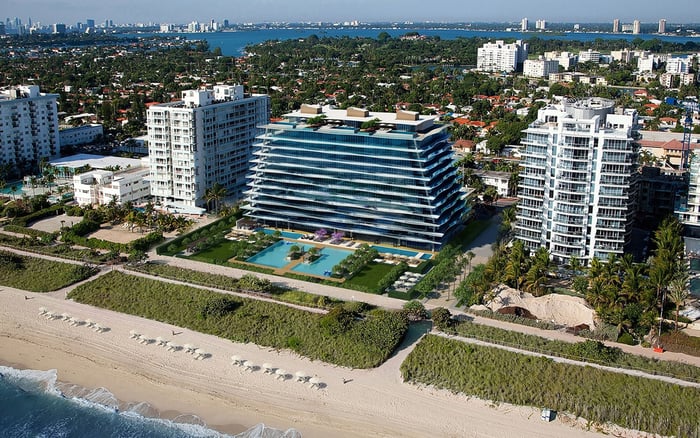
For buyers considering Fendi Château Residences Surfside, these distinctions are a reason to define the intended use early-not to assume that any particular residence or ownership structure produces a preferred legal result.
A nonresident who dies owning Florida real estate may leave an estate requiring Florida ancillary administration in addition to probate in the home state. That possibility belongs in the acquisition discussion, particularly if the existing plan was designed around Colorado assets.
The choice of executor deserves its own review. A person not domiciled in Florida generally cannot serve as personal representative unless a specified family or relationship exception applies. Check an Aspen-based nominee's eligibility rather than assuming that being named in the will is sufficient.
Florida also permits an authenticated nonresident's will devising Florida real estate to be recorded in the property's county, subject to statutory probate, timing and other conditions. This is a conditional legal route, not a universal substitute for administration.
Buying in Florida does not, by itself, mean that every Colorado document needs replacement. Have counsel review the will, trust, powers of attorney and succession appointments to determine whether amendments, supplemental documents or no changes are appropriate. The answer should follow the documents and circumstances, not the state line alone.
Insurance warrants a separate review alongside ownership planning. For a condominium purchase, distinguish the unit-owner policy from the association's master policy. Ask the insurance adviser to examine the actual coverage, exclusions and deductibles rather than infer protection from the building's address or purchase price.
Where a condominium unit-owner policy is exempt from a statutory flood-insurance purchase requirement, that exemption does not establish that the unit has no flood exposure or coverage need. Likewise, a flood-insurance threshold expressed in dwelling replacement cost should not be read as a threshold based on acquisition price.
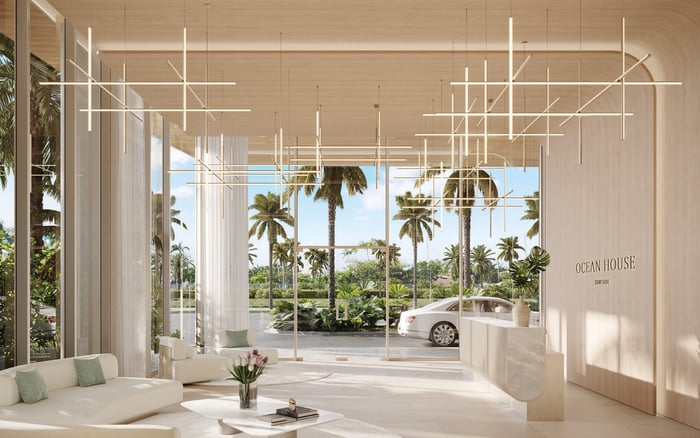
When evaluating Ocean House Surfside, request the documents relevant to the contemplated purchase and have the adviser explain how personal and association coverage relate. General statements about insurance cannot establish a particular property's premium or master-policy terms.
The final deliverable should be a usable record, not merely a collection of signed documents. Ask the advisory team to reconcile the recorded ownership, operative trust provisions, reviewed succession appointments and insurance arrangements. Keep the relevant documents accessible to the people expected to act.
Revisit that coordination if the residence changes from seasonal use to a permanent home or if a later deed transfer is proposed. The goal is straightforward: a South Florida base that fits the family's life without leaving its legal administration unresolved.
Explore your South Florida residential options with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationA nonresident who dies owning Florida real estate may require Florida ancillary administration in addition to probate in the home state. The ownership arrangement should be reviewed before closing.
The trust's existence alone is not sufficient. The deed and trust terms must be coordinated to support the intended ownership and succession arrangement.
No specific exemption applies merely because the transfer is for estate planning. Consideration, mortgages, assumed debt and the transfer structure can affect the analysis.
Seasonal use alone should not be assumed to qualify. Eligibility depends on meeting the applicable permanent-residence requirements.
It may qualify when the applicant has the required beneficial or equitable interest and a present right to occupy the home. Future or contingent beneficiary status does not necessarily suffice.
No. Tax treatment, creditor protection and transfer-at-death restrictions are distinct, and spousal rights may also constrain the succession plan.
A person not domiciled in Florida generally cannot serve unless a specified family or relationship exception applies. Counsel should check the nominee's eligibility.
An authenticated nonresident's will devising Florida real estate may be recorded in the property's county, subject to statutory probate, timing and other conditions.
The purchase alone does not establish that replacement is necessary. Counsel should review the existing documents and determine whether changes are appropriate.
No. An exemption from a statutory purchase requirement does not establish an absence of flood exposure or coverage need, and unit-owner coverage should be reviewed separately from the association's policy.