A founder’s secondary share sale can create a path to a South Florida residence, but the purchase budget should follow confirmed liquidity, tax planning, ownership review, and property-level diligence.
A secondary share sale can bring a South Florida residence within reach without requiring a founder to exit the business entirely. The critical distinction is between the transaction’s headline value and the cash available for a property purchase. A signed share-sale agreement is not the same as unrestricted funds ready for closing.
Before selecting a residence, set a purchase budget that accounts for transaction expenses, tax reserves, any holdbacks, closing costs, and a post-purchase liquidity reserve. The objective is not simply to afford the acquisition, but to own the home comfortably without relying on another liquidity event.
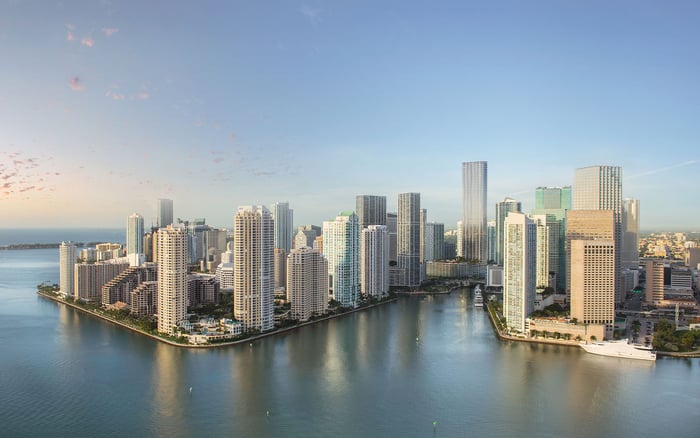
For a search that includes The Residences at 1428 Brickell, the starting number is neither the share-sale price nor the maximum property price. It is the amount the founder can commit while preserving financial flexibility.
A private-company secondary share sale generally must be registered or qualify for an exemption under federal and applicable state securities laws. Agreement between buyer and seller does not, by itself, establish that the resale is permissible.
Section 4(a)(1) and Rule 144 are potential resale pathways, but their availability depends on the transaction’s facts and applicable conditions. Ask securities counsel to confirm the relevant holding period, affiliate status, information requirements, and resale restrictions before treating the proceeds as committed purchase capital.
Separately, have the transaction team identify what remains between signing and access to cash. Confirm the expected funding date, any holdbacks, and the amount expected to be unrestricted. Ask property counsel to review deposit obligations and closing deadlines against that timetable. Structure the home purchase around confirmed access to funds, not the most optimistic share-sale schedule.
A sizable capital gain does not automatically require a quarterly estimated federal tax payment. The answer depends on the founder’s overall tax position, including withholding, credits, and applicable safe-harbor rules.
Estimated payments are generally required when expected tax due after withholding and credits is at least $1,000 and payments fall below the applicable threshold. The safe harbor generally compares payments with 90% of current-year tax or 100% of prior-year tax. For certain higher-income taxpayers, the prior-year threshold rises to 110%.
Ask the CPA for two distinct conclusions: how much to reserve for the eventual tax liability, and the payment amounts and dates needed to address estimated-tax obligations. Meeting a safe harbor does not eliminate the underlying tax bill.
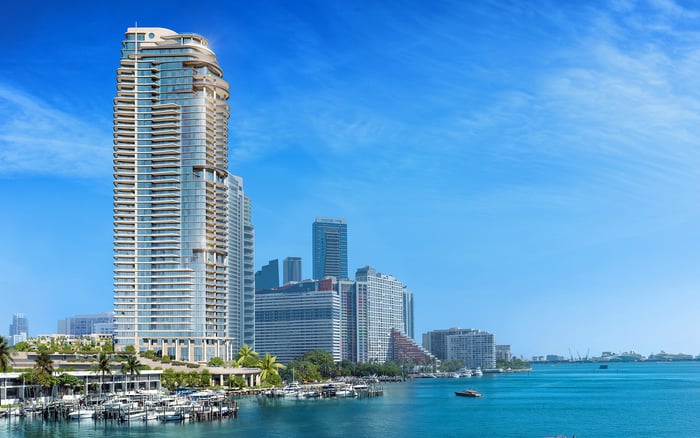
For a Miami Beach search that includes The Perigon Miami Beach, keep that reserve outside the acquisition budget. Select a residence based on the after-tax balance, not cash that may later be needed for taxes.
Request a transaction-specific closing estimate rather than applying a single percentage to the purchase price. Florida’s general documentary stamp tax rate on real-property transfers is $0.70 per $100, or fraction thereof, of consideration. Confirm the applicable county treatment rather than assuming one statewide calculation.
Consideration can include debt or other obligations, not merely the cash paid at closing. Ask the closing team to confirm the calculation, the contract’s allocation of the expense, and the amounts included in the estimate. Documentary stamp taxes due on recordable instruments must be paid before recording.
Resolve the proposed ownership structure at the same time. Do not assume personal, trust, and LLC ownership produce identical homestead consequences. Florida counsel and the county property appraiser should confirm how the intended structure relates to the buyer’s circumstances before the deed is prepared.
Florida homestead property-tax eligibility generally requires legal or beneficial title and qualifying permanent-residence status as of January 1. Do not budget for a purchase intended initially as a second home as though permanent-residence eligibility were already established.
The deed or other ownership instrument must also be recorded in the county’s official records before the exemption may be granted. The base exemption is up to $25,000 of assessed value, but that amount is not necessarily the owner’s entire available exemption.
For a founder considering Alba West Palm Beach, distinguish the property decision from the residence-status decision. Have advisers confirm eligibility and filing steps rather than building an assumed benefit into the carrying-cost estimate. These property-tax considerations are not a complete analysis of homestead creditor protection.
The residence and the association deserve separate review. Before the due-diligence deadline, request association budgets, reserves, meeting minutes, special-assessment information, insurance materials, litigation information, inspection materials, and planned capital projects. This is a practical diligence framework, not a claim that every document is universally required by law.
Apply the same discipline to a Fort Lauderdale search that includes Four Seasons Hotel & Private Residences Fort Lauderdale. Evaluate the documents available for the specific purchase rather than inferring financial condition from a project’s identity.
If financing is contemplated, ask the lender which building-level approval conditions remain unresolved and when approvals expire. Insurance, reserves, litigation, inspections, and repairs can affect condo financing. Treat personal borrowing capacity and project approval as separate questions.
Review flood and windstorm exposure alongside the association’s master policy, including deductibles and exclusions. Have an insurance adviser identify the unit owner’s coverage needs and clarify how they interact with the association’s coverage.
Compare homes by total carrying costs: property taxes, association dues, insurance, maintenance, and special assessments. Keep potential capital obligations explicit rather than folding them into a general contingency. A cash purchase does not remove the need to understand these expenses.
Before proceeding, consolidate the advisers’ conclusions into one purchase plan: confirmed spendable proceeds, tax reserves and payment dates, closing costs, ownership structure, homestead assumptions, association review, insurance, and any financing conditions.
The final question is whether the residence remains comfortable to own after those obligations have been funded. A post-purchase reserve protects flexibility and avoids making the home dependent on the next share sale. That is the distinction between celebrating liquidity and planning around it.
For a considered South Florida property search, explore residences with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe purchase budget should exclude transaction expenses, tax reserves, holdbacks, closing costs, and a post-purchase liquidity reserve. Confirm how much cash will actually be unrestricted.
No. Securities counsel should confirm registration or an applicable exemption under federal and applicable state law, including relevant resale conditions.
No. A CPA should evaluate overall withholding, credits, and safe-harbor eligibility before determining payment requirements.
The general comparison is 90% of current-year tax or 100% of prior-year tax. The prior-year threshold rises to 110% for certain higher-income taxpayers.
No. Keep the reserve for eventual tax liability separate from the calculation of required estimated payments.
Florida’s general real-property transfer rate is $0.70 per $100, or fraction thereof, of consideration. Confirm county treatment and the transaction-specific calculation with the closing team.
Eligibility generally requires legal or beneficial title and qualifying permanent-residence status as of January 1. The ownership instrument must also be recorded before the exemption may be granted.
They should not be assumed to. Confirm the proposed structure with Florida counsel and the county property appraiser.
Request budgets, reserves, meeting minutes, special-assessment details, insurance, litigation information, inspection materials, and planned capital projects before the due-diligence deadline.
Yes. Building-level insurance, reserves, litigation, inspections, and repairs can affect financing, so ask the lender about unresolved project conditions and approval expiration dates.