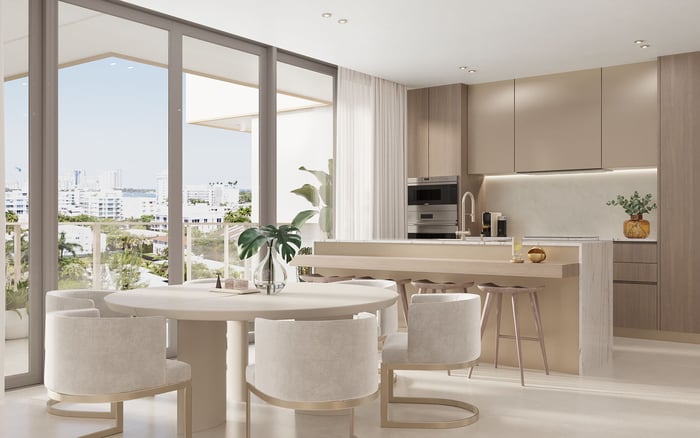
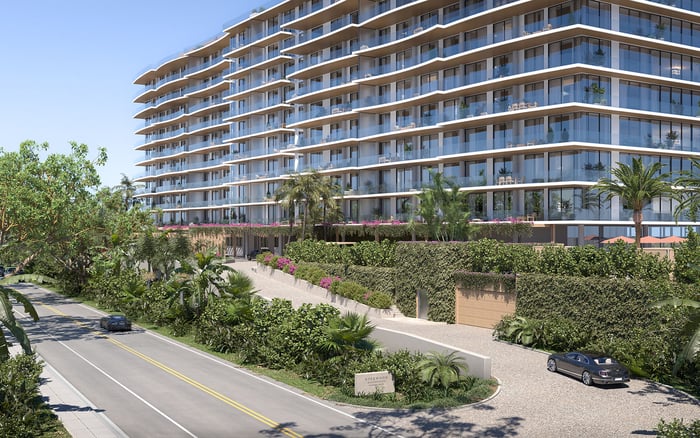
Five Edgewater residences merit a closer look for multigenerational, lock-and-leave living. Their layouts and building profiles offer distinct advantages, but reserve funding, insurance coverage and assessment exposure require association-specific review before purchase.
For a multigenerational family, a lock-and-leave residence must do more than remain attractive between visits. It should accommodate different routines, preserve privacy and make extended absences manageable. In Edgewater, the choice is as much about the association behind the front door as the view beyond the glass.
The five candidates below offer distinct starting points: substantial family layouts, boutique scale, newer construction or furnished flexibility. This is a screening shortlist, not a verified ranking of reserve strength, insurance transparency or protection from surprise assessments. None should be considered financially superior without a review of its own association records.
Buyers considering Aria Reserve Miami alongside established residences should separate three decisions: whether the apartment works for the family, whether management supports unattended ownership, and whether the financial obligations are sufficiently clear. A compelling answer to the first does not settle the other two.
1. Missoni Baia: 700 NE 26th Terrace
Missoni Baia leads this shortlist for its bayfront setting and documented family-sized inventory. The building has approximately 246 residences and approximately 200 feet of Biscayne Bay frontage. A reviewed offering for Unit 5401 included three bedrooms, 4.5 bathrooms and 2,362 square feet, with an asking price of $3.25 million.
That combination merits attention from families balancing shared living with individual space. Bedroom separation, bathroom accessibility and guest arrangements still require a floor-plan review. The asking price is a listing snapshot, not a guarantee of current availability or an indication of total ownership costs. Reserve adequacy and assessment exposure remain unverified.
2. Elysee Miami: Boutique scale at 788 NE 23rd Street
Elysee offers a smaller-building alternative, with 94 units and a stated 2021 build year. Its emphasis on privacy makes it worth screening for households that prefer a more intimate residential environment to a larger community.
Boutique scale is a lifestyle characteristic, not proof of financial resilience. Before favoring Elysee, examine the association's budget, reserve funding and planned work. Then confirm how management handles absences, visiting relatives and emergency entry. Relatively recent construction does not establish that future costs are fully funded.
3. Gran Paraiso: Four-bedroom potential at 480 NE 31st Street
Gran Paraiso has approximately 317 units and a stated 2018 completion year. A reviewed residence offered four bedrooms and 4.5 bathrooms, generous living and dining areas, floor-to-ceiling windows, and high-floor water and city views.
The fourth bedroom makes this a useful candidate for families seeking space for grandparents, adult children or a caregiver. The specific apartment's circulation and bedroom placement still matter more than bedroom count alone. Association financial statements, maintenance records and assessment notices should determine whether its ownership profile is as suitable as its layout.
4. Aria Reserve Miami: Newer construction at 700 NE 24th Street
Aria Reserve has a stated unit count of 782 and a 2025 build year. Two reviewed three-bedroom offerings illustrate why buyers should compare apartments individually: Unit 1206 had three bathrooms and 1,306 square feet, while Unit 1405 had four bathrooms and 1,760 square feet, with an asking price of $2.2 million.
Those differences can materially affect multigenerational comfort. Newer construction and development scale are screening characteristics, not evidence of funded reserves or stabilized operating expenses. Review the applicable association's budget, reserve assumptions and insurance terms rather than treating newness as protection against future assessments.
5. Paraiso Bay: Penthouse flexibility at 650 NE 32nd Street
Paraiso Bay earns its place through reviewed rental inventory that included a renovated, furnished, turnkey penthouse with three bedrooms, a full second living room and private-elevator arrival. Separately identified rental inventory for Unit UPH5302 showed three bedrooms, three bathrooms and 2,108 square feet, advertised at $26,000 per month.
A second living room is particularly worth evaluating when generations keep different schedules. The rental evidence supports consideration of a furnished stay, not a purchase valuation or an assurance about association finances. Review records for the specific Paraiso Bay tower; do not extend its characteristics or financial conclusions to Paraiso Bayviews or the broader development.
Evaluate reserve strength against anticipated obligations, not an isolated balance. Request the budget, financial statements, reserve studies, applicable inspection materials, board minutes and assessment notices. Include litigation disclosures and delinquency information, and ask which planned projects have funding in place.
The practical question is whether expected work, funding assumptions and owner contributions tell a consistent story. Ask your advisers to distinguish funded commitments from proposed projects and unresolved costs. A low monthly charge is no substitute for that analysis.
If the search also includes EDITION Edgewater, apply the same discipline without assuming that one property's financial conclusions transfer to another. Have counsel confirm which documents and inspection materials apply to the particular transaction; legal obligations should not be inferred from building age alone.
Request master-policy declarations, coverage limits, deductibles, exclusions, claims history and renewal terms. Ask for a clear explanation of the division between association and owner responsibilities, including what your own coverage must address.
Transparency requires more than a policy summary. Have an insurance adviser explain potential owner obligations under the disclosed terms and identify unresolved questions. Review renewal assumptions alongside the operating budget rather than treating insurance and association finances as separate conversations.
These steps cannot promise an assessment-free future. They can help a family understand the exposure it is accepting before committing to ownership.
Walk through bedroom separation, accessible bathrooms, elevator access, parking and storage. Confirm guest policies and rental restrictions against the family's intended use, especially when relatives may arrive separately or stay while the primary owner is away.
Then request written answers about emergency-entry permissions, leak response, storm preparation, concierge coverage and post-storm inspections. Ask who authorizes access, who contacts the family and which services must be arranged separately. Do not assume any candidate provides these functions without confirmation.
For buyers also exploring Villa Miami, carry the same household brief into the comparison. The right choice is not necessarily the newest tower or largest apartment. It is the residence whose layout, operating arrangements and documented financial obligations best match the family's expectations.
For a discreet conversation about your Edgewater shortlist, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo candidate has verified superior reserves in this shortlist. Compare association financial statements, reserve studies and planned obligations before drawing a conclusion.
Its bayfront setting and documented family-sized inventory make it a strong first screening candidate. That placement does not establish better insurance or lower assessment exposure.
Elysee has 94 units and privacy-oriented positioning. Families should still confirm apartment layouts, guest policies and management arrangements.
A reviewed Gran Paraiso offering included four bedrooms and 4.5 bathrooms. Current availability and the suitability of a particular layout require confirmation.
Its stated 2025 build year does not establish lower assessment risk. Buyers should review reserve funding, budget assumptions and insurance terms.
They are listing snapshots, not verified current availability or transaction prices. They also do not represent total ownership costs.
Reviewed rental inventory described a furnished, turnkey penthouse with three bedrooms and a second living room. Confirm the specific residence's availability and terms.
No financial conclusion should be transferred between the buildings. Request records for the specific tower and applicable association.
Request master-policy declarations, limits, deductibles, exclusions, claims history and renewal terms. Clarify association versus owner responsibilities with an insurance adviser.
Confirm emergency access, leak response, storm preparation, concierge coverage and post-storm inspections. Obtain clear answers about who acts and who contacts the family.