A Miami primary residence does not switch off UK tax on London rent. Five essential questions clarify withholding, rental expenses, cross-border reporting and the separate role of Florida homestead relief.
For a London homeowner establishing a primary residence in Miami, the property purchase and the tax position deserve separate attention. Retaining a London home as a rental can preserve an asset while a new household takes shape across the Atlantic. It also carries a continuing UK tax obligation that a Florida purchase does not remove.
The essential distinction is between where the owner lives, where the rental property sits and which rules govern each obligation. UK tax residence, Non-Resident Landlord Scheme status, U.S. tax residence and Florida homestead eligibility are separate questions. None substitutes for another.
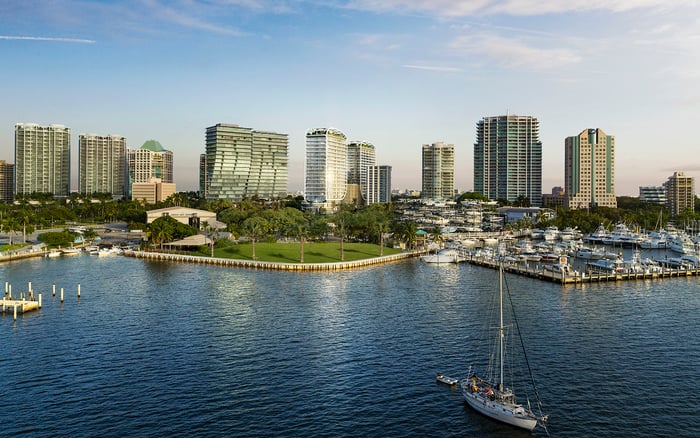
For a buyer considering 2200 Brickell, the disciplined approach is to evaluate the Brickell purchase alongside a separate London rental-income plan-not assume the closing settles both.
1. Does buying a Miami primary residence stop UK tax on London rental income? - The UK obligation continues
No. Rental income from a London property remains subject to UK tax even when its owner lives abroad. Buying a Miami primary residence does not, by itself, remove that obligation. The purchase and the rental-income liability are distinct parts of the owner's financial affairs.
The Non-Resident Landlord Scheme, or NRLS, concerns landlords whose usual place of abode is outside the UK. Living abroad for at least six months a year generally brings an owner within the scheme's definition of a non-resident landlord, even if that person remains UK-resident for tax purposes. The distinction matters: NRLS status does not determine overall tax residence.
2. Will the London letting agent withhold tax from rent? - Gross payment requires approval
Generally, a letting agent must deduct tax under NRLS unless HMRC authorizes payment without deduction. An individual landlord can apply using Form NRL1 to receive rent gross. Approval changes how rent reaches the owner; it does not make the income tax-free. The final liability still needs to be addressed through Self Assessment.
Without a letting agent, a tenant may have withholding obligations, subject to the scheme's conditions. Tax already deducted can be credited against the landlord's UK liability, and excess deductions may be refundable. For household budgeting, distinguish rent collected, cash remitted and the eventual tax bill. No single figure represents the property's final return.
3. Which expenses can reduce the London property's taxable rental profit? - Interest needs separate treatment
Allowable property expenses can reduce taxable rental profit. Mortgage-interest relief for individual residential landlords, however, follows special rules and should not be treated as an ordinary deduction from rental income. A mortgaged property's cash surplus and taxable profit should therefore not be assumed to match.
The 2025-26 UK property-return rules separate gross rental income from tax already deducted under NRLS. Keep those figures distinct in the records supplied to advisers. Letting agents also account for qualifying deductible expenses when calculating withholding, but that calculation does not establish the owner's full annual liability. Confirm the rules for the relevant filing year before relying on an earlier calculation.
4. Must the owner report London rent in both the UK and the United States? - Assess each jurisdiction separately
The UK retains its taxing right over London rental income. Whether the owner also has U.S. reporting obligations requires an individual assessment; purchasing a Miami home alone does not answer that question. The words “primary residence” are not a complete cross-border tax conclusion.
Double-tax relief may be available when the owner's country of residence also taxes UK property income. That possibility does not guarantee that every liability will disappear or that a particular relief applies. Before budgeting on that basis, ask cross-border advisers to establish the relevant obligations and whether relief is available in the owner's circumstances.
5. What changes when Miami becomes the owner's permanent residence? - Homestead relief is separate
A qualifying permanent residence may receive Florida homestead relief, reducing taxable property value by as much as $50,000. This is a reduction in taxable value-not a $50,000 reduction in the tax bill. Eligibility needs to be assessed separately from the London rental position.
The relief concerns Florida property taxation. It is not an exemption for London rental income and does not replace NRLS compliance or UK rental reporting. A buyer should evaluate potential homestead eligibility without treating it as evidence that UK obligations have ended or U.S. tax residence has been settled.
Withholding can affect the cash available to support a second household. Agents generally calculate NRLS tax quarterly, with quarters ending on 30 June, 30 September, 31 December and 31 March. Payment to HMRC is generally due within 30 days of each quarter's end.
Ask the agent to confirm whether withholding applies, whether gross-payment authorization has been received and how qualifying expenses enter the calculation. Keep statements showing gross rent, expenses, tax deducted and net remittances. These records help ensure that a net bank deposit is not the only figure used in annual reporting.
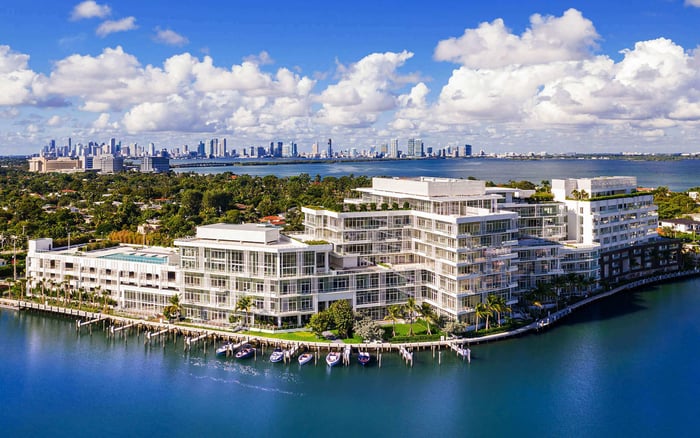
For someone considering Park Grove Coconut Grove, the Coconut Grove ownership budget should sit alongside this rental calendar. Plan around the cash actually expected from London, while keeping the ultimate UK liability as a separate calculation. Gross-payment approval is a cash-flow arrangement, not permission to disregard tax.
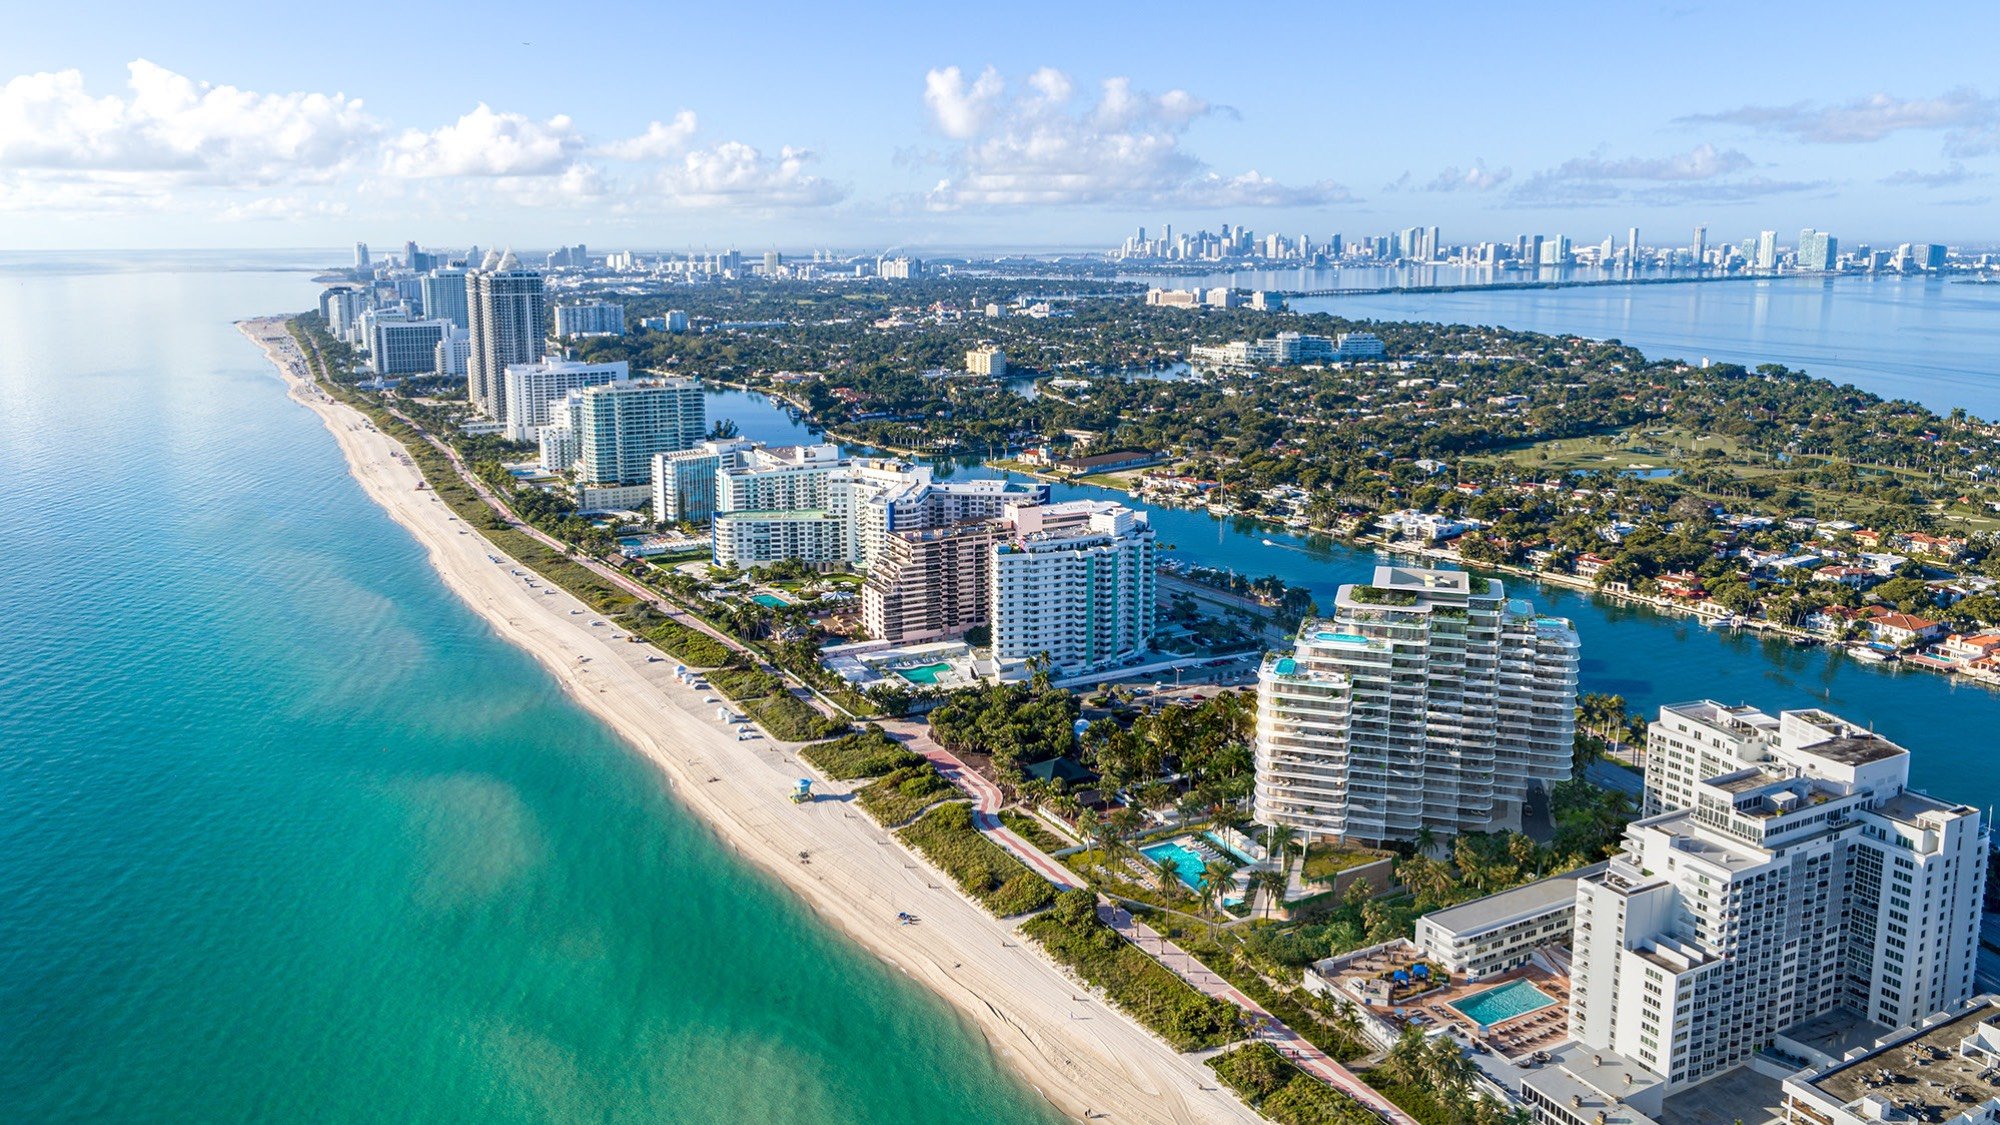
A Miami Beach search that includes The Perigon Miami Beach calls for the same planning discipline: the residence selected does not resolve the owner's cross-border tax position. Property preference and tax status need coordinated advice, but they remain distinct decisions.
Before committing London rental proceeds to Miami household spending, seek clear answers on four points: UK tax residence, NRLS treatment, U.S. tax residence and filing obligations, and Florida homestead eligibility. A conclusion on one should not be applied to the others without review.
The practical objective is a coherent ownership plan: a London rental account with clear records, a Miami household budget based on realistic remittances and no assumed exemption simply because the owner has moved. This is general information, not individualized tax or legal advice.
Explore your next South Florida residence with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. London rental income remains subject to UK tax even when the owner lives abroad.
No. An owner can fall within the Non-Resident Landlord Scheme while remaining UK-resident for tax purposes.
Generally yes, unless HMRC has authorized payment without deduction under NRLS.
It allows an individual landlord to apply to receive UK rent without tax deducted at source. Approval does not eliminate the final tax liability.
Yes. A tenant may have NRLS withholding obligations when no letting agent handles the rent, subject to the scheme's conditions.
Yes. Tax deducted under NRLS can be credited against the landlord's UK liability, with excess deductions potentially refundable.
Not for individual residential landlords. Mortgage-interest relief follows special rules and should be assessed separately from ordinary rental expenses.
They end on 30 June, 30 September, 31 December and 31 March. Agents generally pay the tax within 30 days after each quarter ends.
That requires an individual assessment of U.S. obligations. The UK retains its taxing right, and double-tax relief may be available if the owner's country of residence also taxes the income.
No. It concerns Florida property taxation and may reduce a qualifying home's taxable value by as much as $50,000, not the tax bill by that amount.