A California departure does not necessarily end California tax exposure on equity compensation. For a Miami home purchase, distinguish award income, state sourcing, actual sale proceeds and remaining obligations before committing cash to a residence.
A move from California to Miami can redraw a household’s priorities, but it does not erase the tax history of its equity compensation. Before translating a stock award into a residential budget, separate three figures: the award’s taxable value, the cash generated by selling shares, and the amount available for a purchase.
That distinction matters whether the search begins in Brickell or elsewhere in South Florida. A seven-figure vesting event is not necessarily a seven-figure down payment. The useful number is what remains after reconciling withholding, reserving for unpaid taxes, and protecting liquidity beyond closing.
The objective is not simply to buy with equity proceeds. It is to purchase without making the household’s remaining obligations dependent on another vesting event.
Restricted stock and restricted stock units, or RSUs, are not interchangeable. Their terms and tax timing require separate review before proceeds are committed to a home purchase.
Restricted stock generally creates taxable wage income at vesting equal to the shares’ fair market value minus the amount paid for them. RSUs generally are not taxable at grant; income recognition commonly occurs when vested units are settled and compensation becomes available. Vesting is therefore not a universal tax trigger for every award structure.
For RSUs, the compensation recognized generally constitutes ordinary wage income, not capital gain. A subsequent share sale is a separate event. The value recognized as income when shares are received generally establishes their tax basis, against which later sale proceeds are compared.
Selling promptly may leave little additional appreciation to measure, but it does not eliminate the wage income generated by the award. Keep the compensation calculation distinct from the sale calculation throughout the purchase plan.
California can tax compensation received by a nonresident for services performed in California. Moving before equity vests does not automatically remove the portion attributable to that work.
A California-source allocation can use California workdays divided by total workdays over the applicable service period. That period depends on the award and its governing sourcing rules. Do not assume every restricted-stock award and every RSU uses the same window.
Consider a simplified illustration: a $1 million taxable vesting value with a 60% California workday allocation produces $600,000 of California-source compensation. That is an allocated income amount, not a $600,000 tax bill. Nor does the 60% allocation establish the combined effective tax rate.
Federal income recognition and California sourcing are separate calculations. An award can produce federal wage income while California taxes only the portion attributable to services performed there. Residency is another question: it depends on the facts surrounding the move and continuing connections, not merely a declared departure date. Have the residency position and award allocation reviewed together before treating proceeds as available housing capital.
RSU compensation generally is subject to supplemental-wage withholding, but withholding may differ from final tax liability. The amount in a brokerage account is neither a complete tax calculation nor evidence that all obligations have been satisfied.
Start with actual cash received. Identify taxes already paid through payroll withholding or share sales used to fund withholding, then determine what remains payable. This reconciliation prevents two opposite errors: spending cash needed for taxes and deducting the same tax obligation twice.
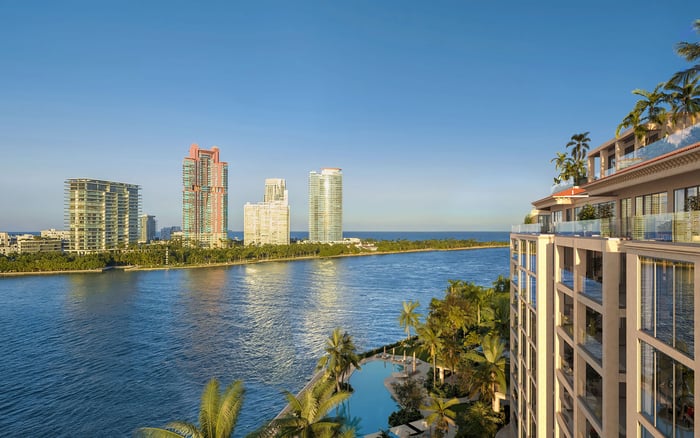
For a buyer considering 2200 Brickell, the planning question is not how large the award looked on its vesting statement. It is how much verified cash can be committed while keeping the remaining tax reserve intact. Apply that discipline before allowing an equity award to set the search budget.
Use a simple cash calculation to distinguish assumptions from obligations. For illustration only, begin with $1 million of gross sale proceeds, subtract a hypothetical $350,000 tax-and-selling-cost reserve, and retain a further $150,000 liquidity reserve. That leaves $500,000 for down payment and closing.
The $350,000 reserve is an assumption, not a calculated liability or a recommended tax rate. Its 35% relationship to gross proceeds says nothing definitive about a particular buyer’s taxes. It does not follow from the separate 60% California allocation example.
This illustration starts with gross proceeds before the assumed deductions. If the starting figure instead reflects cash already reduced by withholding or selling costs, adjust the remaining reserve accordingly. Do not subtract the full hypothetical allowance again without reconciling those payments.
Finally, $500,000 for down payment and closing is not $500,000 for the down payment alone. Nor does it establish an affordable purchase price or mortgage qualification. Those require a separate assessment of financing, income, obligations and carrying costs.
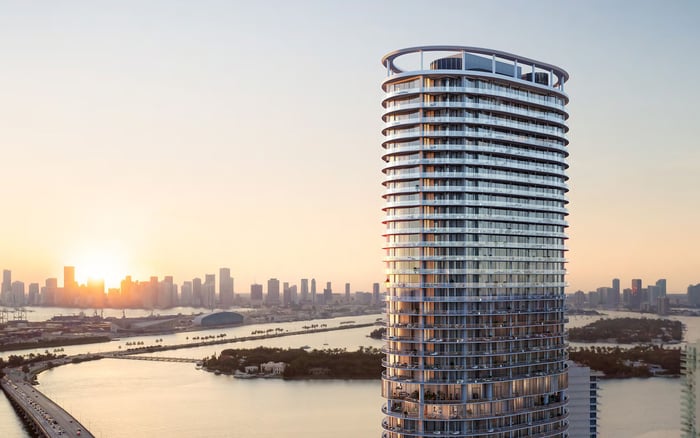
A Miami Beach search that includes The Perigon Miami Beach should keep acquisition cash separate from ownership costs. Obtain property-specific figures for insurance, property taxes, condominium or HOA assessments, repairs and furnishings rather than applying an unsupported allowance.
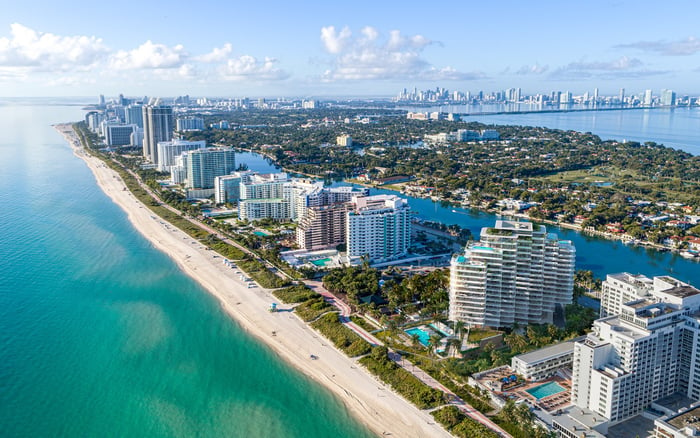
Use the same framework in Coconut Grove when considering Four Seasons Residences Coconut Grove. The residence may change, but the financial sequence should not: establish deployable proceeds, identify closing requirements, then test ongoing carrying costs against the household’s broader resources.
Keep the liquidity reserve visibly separate from purchase funds. If a preferred residence requires consuming that reserve, revisit the contribution, financing or selection rather than quietly redefining protected cash as available cash.
Preserve grant documents, vesting schedules, relocation dates and workday records. Retain W-2s, brokerage basis records and domicile evidence as well. Together, these support the distinctions between compensation, California-source income, tax payments and sale proceeds.
Before committing funds, ask the tax adviser to reconcile award treatment and remaining liabilities, and the financing team to evaluate the proposed cash contribution separately from borrowing capacity. A clear handoff is more useful than a single optimistic estimate of what the stock is worth.
The strongest Miami home budget begins with documented, deployable cash, not the headline value of an equity award. Preserve the distinctions between residency, sourcing, income recognition and liquidation, then carry them into the purchase decision. This is a planning framework, not individualized tax or legal advice.
For a discreet residential search guided by your net-proceeds budget, explore South Florida with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. California can still tax compensation attributable to services performed in the state, even when the recipient is a nonresident.
Not necessarily. Restricted stock generally creates wage income at vesting, while RSU income commonly arises when vested units are settled and compensation becomes available.
An allocation can use California workdays divided by total workdays during the applicable service period. The appropriate period depends on the award and relevant sourcing rules.
No. In the illustration, 60% of a $1 million taxable value produces $600,000 of California-source compensation, not a tax rate or tax bill.
No. Selling promptly does not eliminate the compensation income, even if there is little additional appreciation before the sale.
The value recognized as income when shares are received generally establishes their tax basis. A subsequent sale creates a separate gain or loss calculation by comparing proceeds with that basis.
No. Withholding may differ from final liability, so reconcile amounts already paid before determining an additional reserve.
No. It is a hypothetical tax-and-selling-cost reserve, not a calculated liability or recommended rate, and must be reconciled with any amounts already paid.
No. The illustration leaves $500,000 for down payment and closing, while affordability and mortgage qualification require separate evaluation.
Keep grant documents, vesting schedules, relocation dates, workday records, W-2s, brokerage basis records and domicile evidence. These help support the tax calculations behind the cash budget.