Buying a South Florida residence with a retiring sibling calls for more than a shared preference for the address. Align occupancy, title, exit rights, recurring costs, accessibility, and homestead planning before committing.
Buying a South Florida residence with a retiring sibling can bring family closer while preserving the independence each person values. The essential question is not simply where to buy, but what the purchase should accomplish: a shared primary home, a retirement residence supported by a sibling, or a seasonal retreat with different patterns of use.
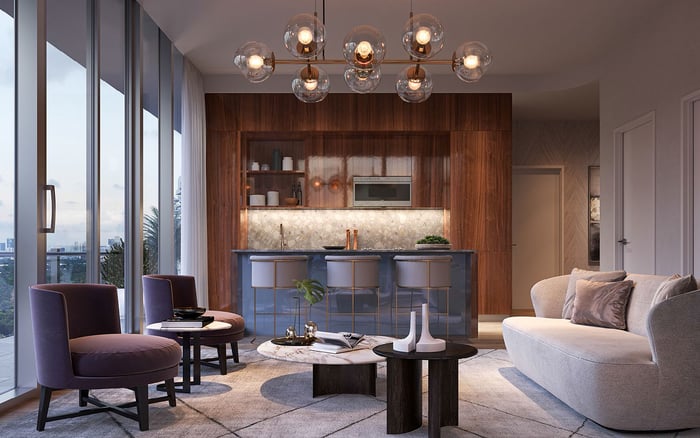
That distinction should guide the search before architecture or views set the agenda. Even when considering 2200 Brickell, the first conversation should center on occupancy, financial responsibility, and privacy-not finishes. A beautiful residence cannot resolve incompatible expectations.
The five decisions below put the family arrangement ahead of the property selection. Their order reflects practical buying priorities: establish the purpose, protect both owners, then test the residence against the realities of retirement.
1. Define the home's purpose: shared living or one sibling's retirement residence
Decide who will live in the property full time and who will visit seasonally. Written use rules are especially useful when those roles differ. Discuss private rooms, visiting family, shared spaces, and notice before extended stays. These guidelines preserve comfort; they do not imply that equal ownership requires identical occupancy.
Then separate use from financial responsibility. Spending fewer nights in the residence does not automatically reduce a sibling's contribution. Document the agreed allocation of expenses and whether either owner has authority to approve work. Before either person commits funds, establish what happens if one sibling's plans change.
2. Choose the ownership structure: inheritance and an orderly exit
Florida recognizes tenancy in common and joint tenancy with right of survivorship. Tenants in common can hold equal or unequal percentages, and a deceased owner's interest generally passes through their estate rather than automatically to the surviving sibling. Properly established survivorship ownership can transfer that interest automatically to the survivor. Tenancy by the entirety is reserved for married couples, not siblings buying together.
Have a Florida attorney coordinate the deed, estate intentions, and co-ownership agreement. Include a documented buyout mechanism in case one sibling wants to sell and the other wants to remain. Ask counsel to establish valuation, notice, and payment procedures. Without an agreement, a dispute over retaining or selling jointly owned property may lead to partition proceedings to divide or sell it.
3. Set the all-in budget: sustainable retirement ownership
Purchase price is only the opening figure. Build a shared budget that accounts for insurance, property taxes, association fees, mortgage payments, maintenance, and improvements. The agreement should identify each sibling's obligations and the consequences of missed payments, rather than defer those decisions to a difficult future conversation.
Distinguish recurring expenses from discretionary upgrades. Consider an agreed reserve and a process for approving larger expenditures. Do not assume both siblings will always have the same liquidity or appetite for renovation. The affordability test is whether the arrangement remains comfortable as ownership costs rise-not simply whether both buyers can fund their initial contributions.
4. Evaluate long-term suitability: condition, insurance, and accessibility
Insurance premiums can depend on coastal proximity, flood risk, roof condition, construction type, hurricane protections, and prior claims. Investigate those characteristics before treating two similarly priced residences as financially comparable. Standard homeowners insurance generally does not cover flooding; separate flood coverage is available to homeowners and condominium unit owners. Obtain property-specific guidance rather than assuming the existing policy addresses every exposure.
For retirement living, assess one-level layouts, accessible entrances, walk-in showers, elevators where needed, and proximity to healthcare. These are buying considerations, not mandatory accessibility standards. Walk through the residence with future daily routines in mind: arriving with groceries, reaching bedrooms, and moving between the entrance and living spaces. A compelling view should not outweigh an impractical route through the home.
5. Coordinate homestead planning: individual eligibility and application timing
Moving to another Florida residence requires a new property-tax homestead-exemption application; the exemption does not automatically transfer. Eligible owners may also apply to transfer accrued Save Our Homes benefits through portability. Do not assume that joint ownership, a retirement announcement, or one sibling's eligibility establishes the same treatment for the other.
Confirm each person's circumstances with the property appraiser in the county where the residence is located. Verify the applicable filing requirements early, including the March 1 homestead application deadline. Keep property-tax homestead questions distinct from other Florida homestead protections, and coordinate the applications with qualified legal and tax advisers.
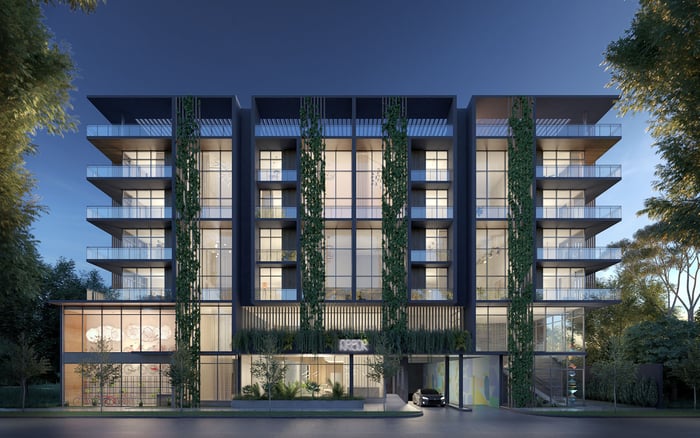
Carry the ownership framework from showing to showing. For a Boca Raton search that includes Alina Residences Boca Raton, assess the particular residence against both siblings' agreed needs. Does the layout provide enough separation? Can each person maintain a comfortable routine without regularly disrupting the other?
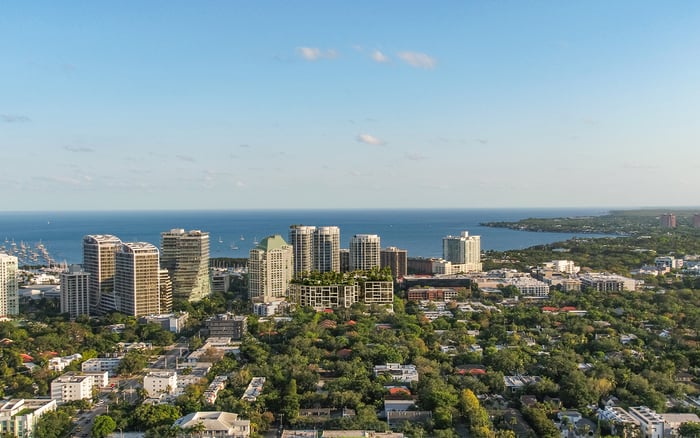
Apply the same discipline when considering Arbor Coconut Grove in Coconut Grove. Request the relevant plans, expense information, and property documentation rather than inferring suitability from the neighborhood or project identity. These are candidates for individual evaluation, not assurances of accessibility, insurance cost, or retirement suitability.
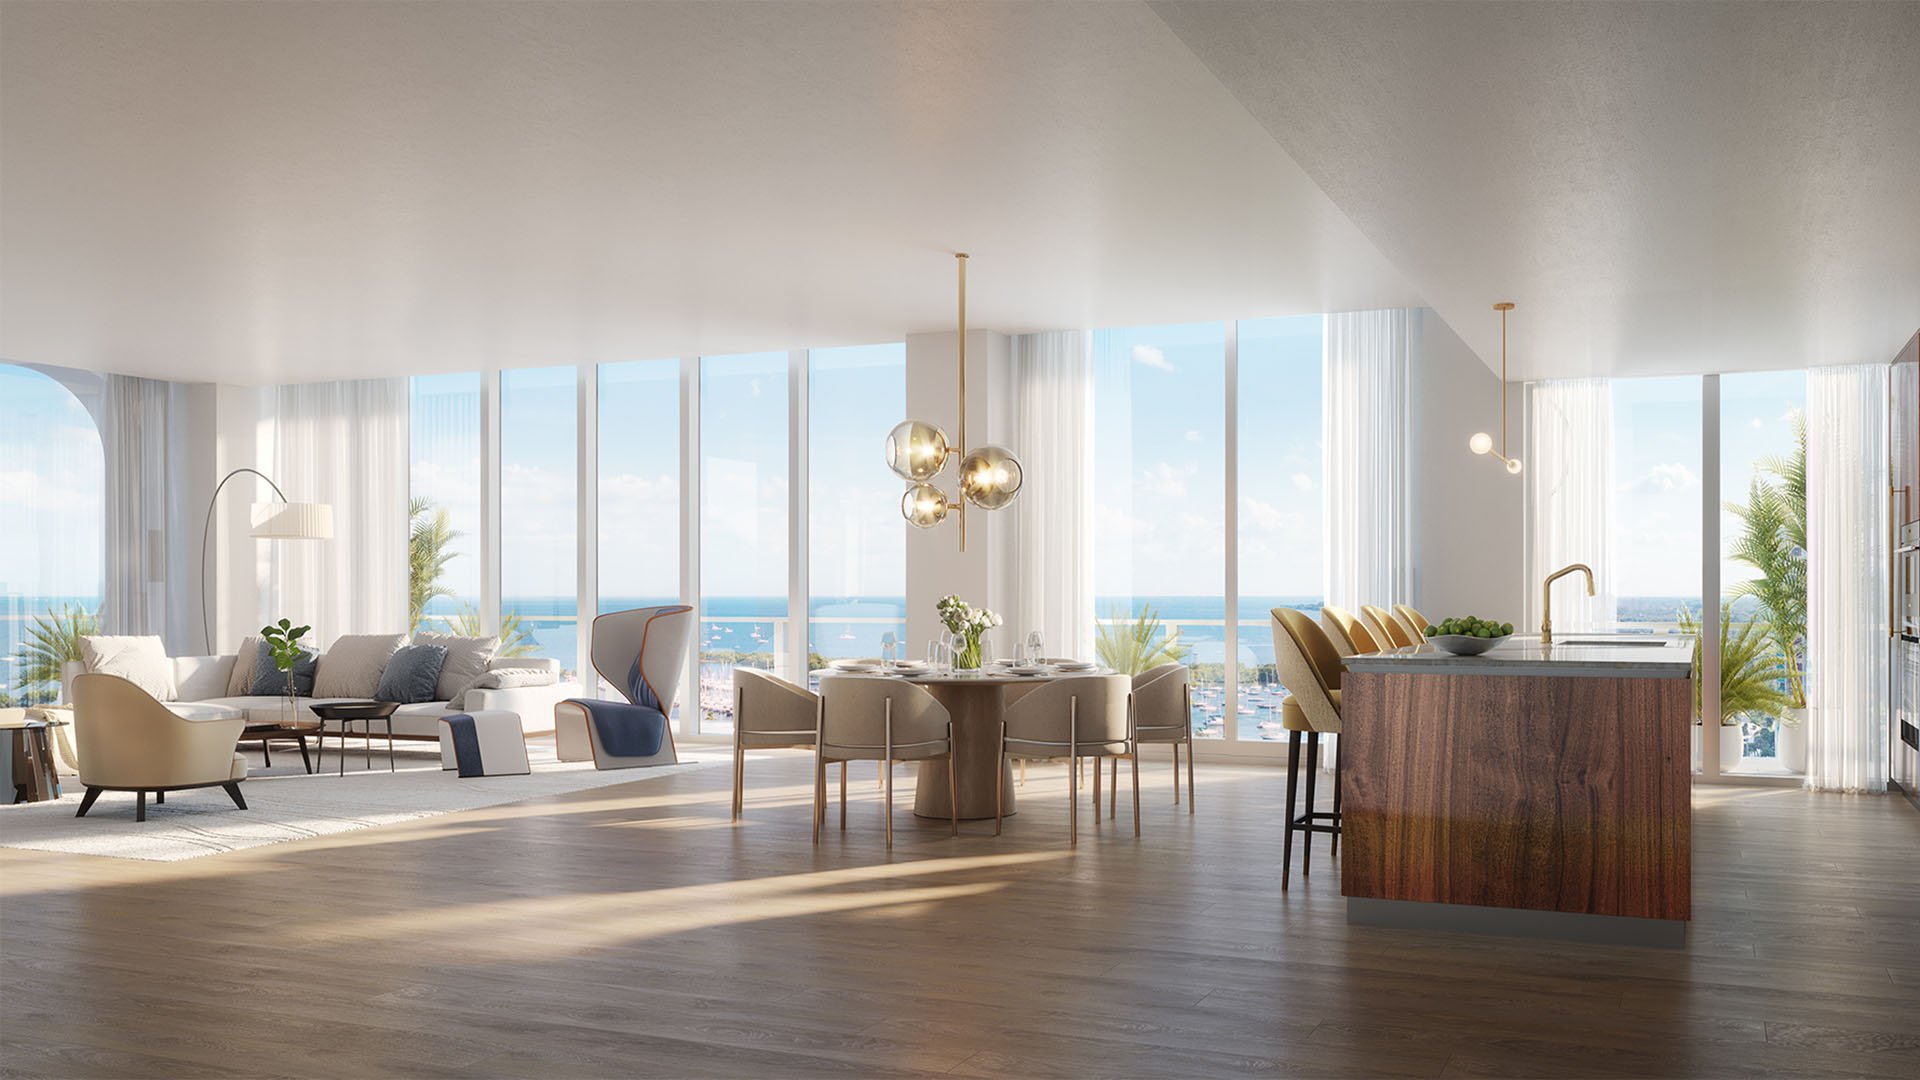
Waterfront appeal calls for a property-specific insurance review, not a general assumption about coverage. Seasonal ownership likewise calls for a precise conversation about access. If one sibling regards the residence as home and the other sees it as a holiday base, an undefined guest calendar can become more consequential than the original purchase negotiations.
Write down how visits, guests, maintenance access, and proposed changes will be handled. Revisit the agreement when occupancy changes. The objective is not to make every detail of family life contractual, but to prevent different expectations from becoming competing claims on the same space.
Before committing, review four items side by side: the intended occupancy arrangement, the proposed deed and exit provisions, the all-in budget, and the property's suitability for retirement. Add a separate homestead filing checklist tailored to each sibling's eligibility.
The strongest purchase is one both siblings understand in the same way, including what happens when circumstances change. Clarity protects not only the residence, but also the relationship that made buying together attractive.
Explore South Florida residences with MILLION to shape a shortlist around your family's priorities.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationDecide whether it will be a shared home or primarily one sibling's retirement residence. Document occupancy, use rights, expense sharing, and what happens if either sibling wants to sell.
Yes. Tenants in common can hold equal or unequal ownership percentages, which should be coordinated with their legal agreement.
Not necessarily. A tenant-in-common interest generally passes through the deceased owner's estate, while properly established joint tenancy with right of survivorship can transfer the interest automatically.
No. Tenancy by the entirety is available only to married couples, not siblings buying together.
It should specify responsibility for mortgage payments, property taxes, insurance, maintenance, and improvements. It should also address missed payments.
A documented buyout mechanism can provide a path for one sibling to retain the residence. Unresolved disagreements may lead to partition proceedings to divide or sell the property.
Standard homeowners insurance generally does not cover flooding. Separate flood coverage is available to homeowners and condominium unit owners.
Consider one-level layouts, accessible entrances, walk-in showers, elevators where needed, and proximity to healthcare. Evaluate the particular residence rather than assuming a project is suitable.
No. Moving to another Florida residence requires a new homestead-exemption application, and eligible owners may also apply for portability of accrued Save Our Homes benefits.
No. Each sibling's eligibility should be confirmed with the property appraiser in the county where the residence is located.