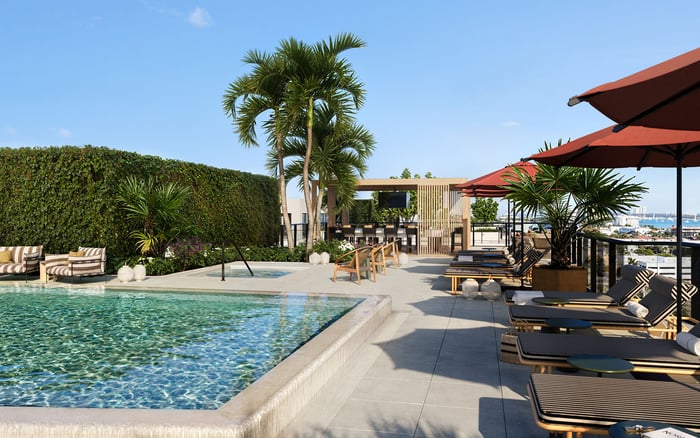
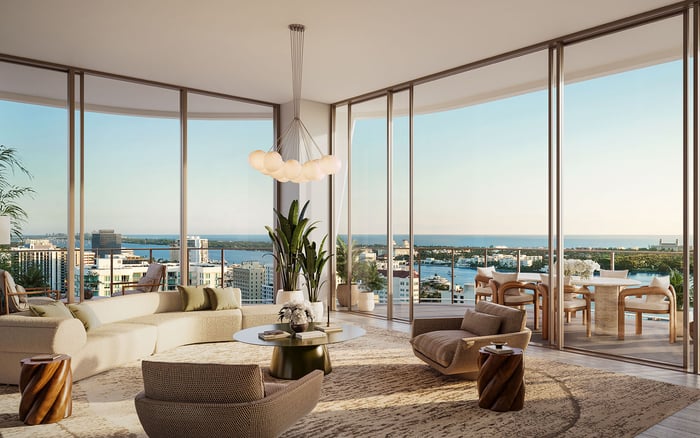
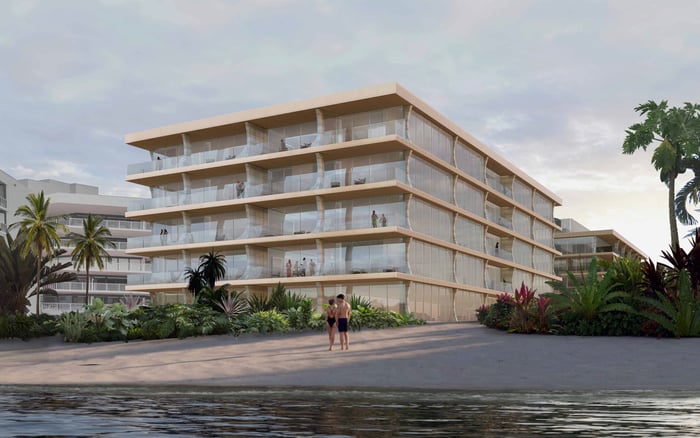
A furnished residence should offer convenience without ambiguity. For buyers at The Ritz-Carlton Residences® Miami Beach, a disciplined review of inventories, transfer documents, replacement permissions, insurance, and resale terms helps distinguish a beautiful presentation from a clearly defined purchase.
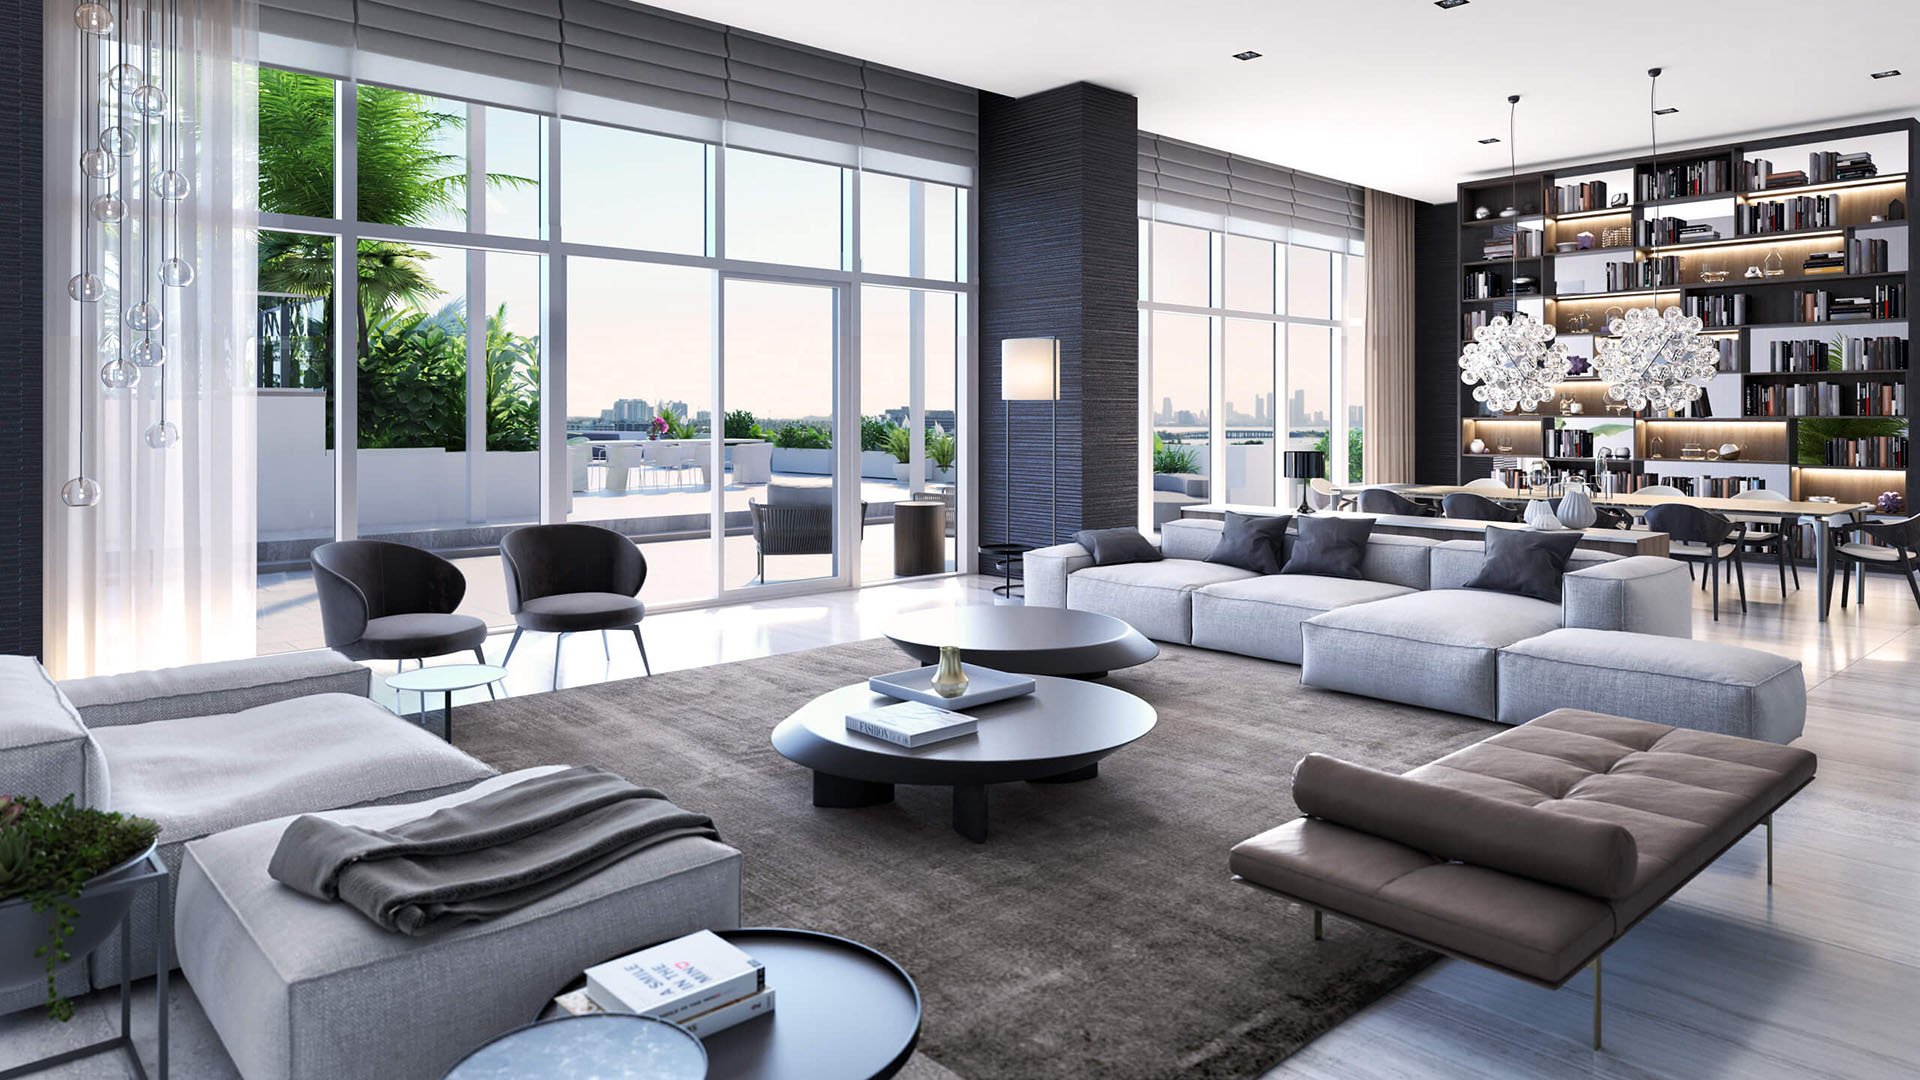
A beautifully furnished residence offers an immediate vision of ownership: rooms resolved, proportions considered, and fewer decisions between closing and arrival. At The Ritz-Carlton Residences® Miami Beach, a serious buyer should distinguish that visual promise from the property and possessions actually being acquired. Design is not proof of inclusion.
Located at 4701 N Meridian Avenue, Miami Beach, FL 33140, the development is a non-hotel branded residential property. That identity should not invite assumptions about hotel furnishing standards, rental-program inventories, or compulsory interior refreshes. The purchase remains a condominium transaction; furniture requires its own precise treatment.
The practical review has three parts: what the buyer owns at closing, what the buyer may replace afterward, and what may be retained or conveyed on resale. Each answer should rest on the transaction documents and applicable condominium provisions, not the atmosphere of a showing.
Begin with written confirmation that the particular residence is furnished, partially furnished, or unfurnished. Designer-driven marketing does not establish that every sale includes a complete package. Nor should a photograph serve as an informal inventory.
Ask the seller to distinguish the residence’s finishes from its movable contents. Then identify anything displayed but excluded, available for an additional price, or expected to be substituted before closing. These are requests for clarity, not assertions that such arrangements exist in a particular offering.
For a buyer also considering Faena House Miami Beach, the same discipline applies: compare documented inclusions rather than treating presentation as the delivery standard. One property’s contract cannot establish another property’s furniture obligations.
Before assigning value to turnkey convenience, have counsel align the listing description, negotiated terms, and final agreement. The word furnished should begin the inquiry, not conclude it.
A furniture package deserves a specification, not merely a description such as complete interiors. Coordinated specifications can organize a residential furnishing package. They offer a useful diligence model, not evidence of a mandatory package at this address.
Request a room-by-room schedule covering:
Brands, models, quantities, and identifying photographs where useful.
Which pieces are included, excluded, or separately priced.
The agreed condition of included items and any proposed substitutions.
Which displayed accessories, lighting, rugs, or artwork, if any, transfer.
The objective is to make the agreement verifiable in the rooms themselves. A reference to a dining set, for example, should not leave the number of chairs or the identity of the table unresolved.
Have counsel attach the agreed inventory to the purchase contract or an appropriate separate bill of sale. Ask how any inconsistency between those documents will be resolved. Before closing, compare the inventory with the residence and document discrepancies while there is still time to address them.
Ownership of an apartment does not, by itself, settle how every interior element is classified or whether it may be removed. Review the declaration and related condominium documents before treating every fixture or built-in as freely removable personal property.
Ask counsel to distinguish movable furniture, fixtures, built-ins, and any elements subject to condominium control. For each ambiguous item, seek a practical answer: does it transfer, who is responsible for it, and what permissions apply to removal or alteration?
The seller should also confirm the ability to convey the listed contents. Where appropriate, ask whether any item is borrowed, leased, or otherwise excluded from outright transfer. These are protective questions, not indications of a known issue at the property.
Keep the resulting ownership record with the closing documents. A clear inventory can support later insurance discussions, replacement decisions, and negotiations with a future purchaser.
The available terms do not establish a mandatory Miami Beach furniture package, approved replacement vendors, a compulsory refresh schedule, or an in-unit furniture reserve. Buyers should neither budget for those obligations as confirmed nor assume that every contemplated change is unrestricted.
Request the applicable rules and ask whether replacing movable furniture is treated differently from altering installed lighting, cabinetry, or other built-ins. If a proposed change requires approval, request the written provision and understand the submission process before committing to purchases.
Ask, too, whether any separate agreement attached to the offered package imposes ongoing obligations. If a replacement requirement is described as a brand standard, request the provision that applies to this residence.
Finally, separate permission from preference. A coordinated interior may be worth preserving for personal enjoyment, but aesthetic continuity is not a contractual duty to retain particular pieces or buy from a particular supplier.
Turnkey convenience should have a clearly negotiated value. In luxury condominium resales, furniture may be conveyed through a separate bill of sale or included as an as-is lump sum. Neither approach makes the package’s original cost equivalent to its present value or the residence’s real-estate value.
Ask for the proposed furniture allocation, inspect condition, and assess the package’s worth for your intended use. Do not rely on an assumed package price, replacement cost, or measurable resale premium for this property.
Budget review should be equally precise. For buyers also considering the separate The Ritz-Carlton Residences® West Palm Beach, association budgets, reserves, insurance allocations, and unit-specific fees warrant review. Those details do not establish furniture charges or replacement obligations in Miami Beach.
Ask the association and your insurer how the included contents would be covered. Do not assume the building policy protects your personal property. Use the inventory to discuss coverage, valuation, exclusions, and any documentation the insurer requests.
The purchase review should look beyond arrival day. Ask counsel whether any applicable agreement requires furniture to remain with the residence, restricts its separate disposal, or imposes conditions on a later transfer. A requirement that furniture convey on resale is not established here and should not be presented as a building rule.
If future leasing matters, review it separately. Do not assume a hotel rental pool exists; its absence from the offering does not establish that all leasing is prohibited.
The final checkpoint is straightforward: written furnished status, an agreed inventory, clear transfer documents, reviewed replacement provisions, and an insurance plan. Preserve those records and update the inventory as contents change. The reward is not merely a finished interior, but a purchase whose practical boundaries are understood.
For a discreet conversation about evaluating your next South Florida residence, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe property is located at 4701 N Meridian Avenue, Miami Beach, FL 33140.
A complete furniture package is not established as a universal inclusion. Obtain written confirmation of the specific residence’s furnished, partially furnished, or unfurnished status.
No. This is a non-hotel branded residential property, and any furnishing obligations should be established through the applicable documents.
Request a room-by-room inventory identifying brands, models, quantities, condition, and inclusions or exclusions. Clarify which items carry a separate charge.
Have counsel attach the agreed inventory to the purchase contract or an appropriate separate bill of sale. Ensure the documents clearly identify what transfers at closing.
Do not assume so. Review the condominium documents to establish the classification of interior elements and any applicable removal or alteration requirements.
Those obligations are not established for this property. Ask for the written provisions governing any replacement requirement described during negotiations.
Do not assume the building policy covers personal property. Ask the association and your insurer how the contents would be insured under the applicable policies.
A mandatory resale-transfer requirement is not established. Have counsel review applicable agreements before deciding what may be retained, sold separately, or conveyed.
No measurable resale premium is established for a package at this property. Evaluate its condition and usefulness separately from the residence’s real-estate value.