A buyer-focused examination of Lincoln’s listed association fees and the budget, reserve, and service-contract questions that should guide a disciplined comparison with Opus Coconut Grove.
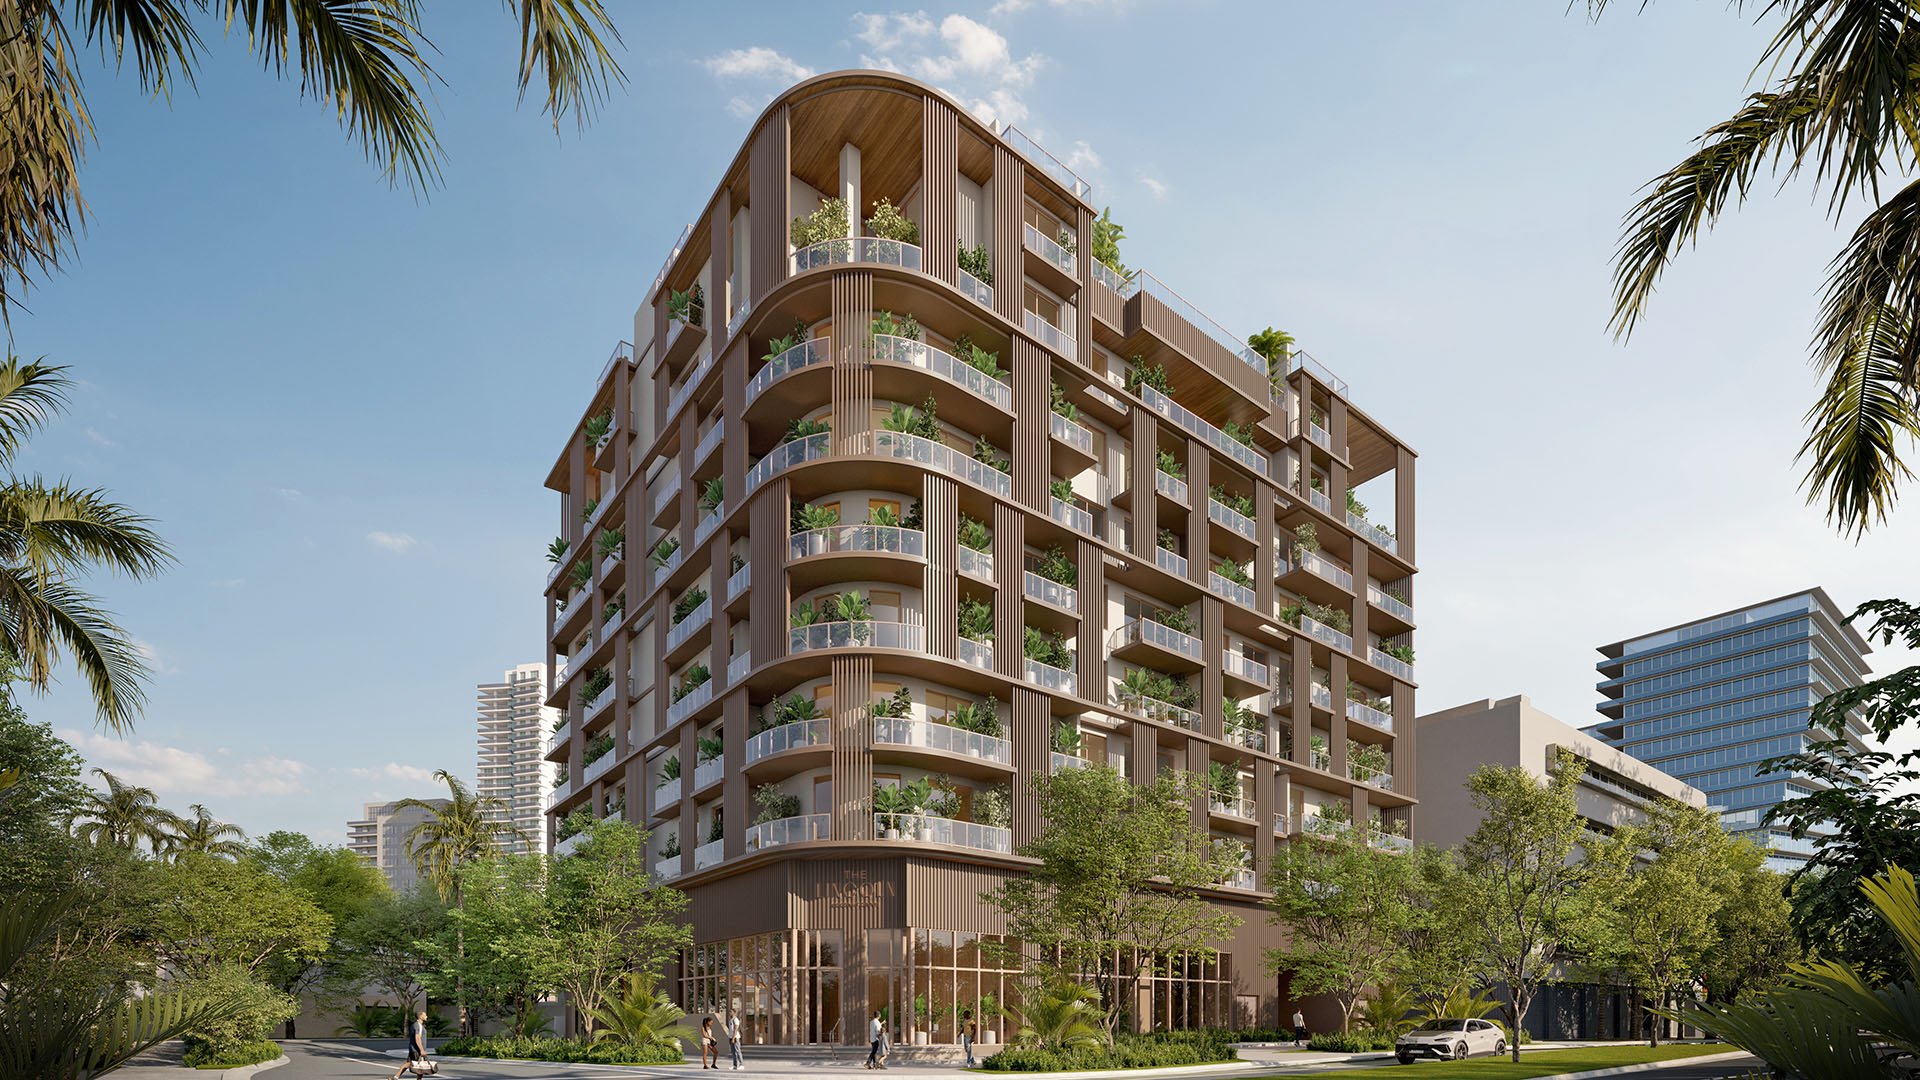
A luxury residence is both a private retreat and a shared operating commitment. The finishes are immediately visible; the financial structure behind daily service deserves equally close attention. For buyers considering The Lincoln Coconut Grove and Opus Coconut Grove, a useful comparison begins with what the association budget funds, how each residence participates, and which obligations may change over time.
The Lincoln Coconut Grove
is listed at 2650 Lincoln Avenue, Miami, FL 33133. Its available listing-level association fees offer concrete starting points. Opus Coconut Grove is marketed as a boutique luxury residential project in Coconut Grove, Miami. Neither positioning nor a quoted monthly payment, however, establishes long-term operating value.
The current figures do not support a like-for-like cost comparison. A lower quoted fee does not necessarily mean a more economical service model; a higher one does not demonstrate stronger reserves. The buyer’s task is to connect each payment to documented services, allocation rules, and future obligations.
Three Lincoln residences illustrate why a building-wide headline fee would be misleading. The quoted monthly association fee is $2,113 for Unit 302, $2,180 for Unit 406, and $3,461 for Unit 205. These are listing-level figures, not verified final ownership obligations.
Multiplying those figures by 12 gives a straightforward annual baseline:
Unit 302: $25,356 in annual association dues.
Unit 406: $26,160 in annual association dues.
Unit 205: $41,532 in annual association dues.
Each calculation assumes no increases or additional assessments. None represents total carrying cost. Property taxes, owner insurance, financing, interior upkeep, and potential assessments belong on separate lines in the ownership model.
The variation also requires a unit-specific explanation. Request the assessment allocation for the exact residence under consideration and reconcile it with the governing documents and budget. Do not infer the reason for a fee difference from unit numbers or price positioning. Until the allocation is understood, these figures describe separate listings, not comparable service packages.
Lincoln’s stated maintenance inclusions encompass security, exterior and common-area upkeep, building insurance, roof repairs, trash removal, amenities, cable TV, elevators, hot water, management, parking, and water. That breadth is useful, but an inclusion label does not establish service frequency, staffing coverage, contractual limits, or whether every related expense is covered.
Ask for a line-by-line connection between the proposed experience and the operating budget. For security, identify the coverage being funded. For management, distinguish base compensation from separately chargeable work. For maintenance, ask which activities are routine and which require capital funding. These are diligence questions, not established terms for either project.
For Opus, a complete association budget, executed management agreement, and detailed long-term service-contract schedule are not established here. That demonstrates neither higher nor lower costs. A responsible comparison must remain conditional until the relevant documents can be reviewed on the same basis as Lincoln’s.
The objective is not the longest inclusion list. It is a clear account of what owners receive and what they may still need to fund.
A reserve-fund contribution is identified for Lincoln. That is not evidence of the reserve balance, funding adequacy, or future capital requirements. A reserve line signals an allocation; alone, it does not show how well future obligations are covered.
Request the reserve schedule, its underlying assumptions, and the proposed contribution attributable to the residence. Ask which components are included, when expenditures are anticipated, and how projected costs align with the funding plan. Where available, reconcile those projections with the association’s financial records.
Apply the same questions to both properties without presuming an outcome. No verified reserve-funding percentage or special-assessment exposure is established for either. Buyers should not treat a reserve contribution as protection against every future assessment-or the absence of a quoted balance as evidence of underfunding.
Evaluate reserve quality through documentation, not the scale or elegance of the property.
A starting budget captures one period. Binding service agreements reveal how certain expenses may evolve. No verified contract escalators or staffing plans are established for Lincoln or Opus. The appropriate next step is contract review, not a forecast presented as fact.
For each material agreement, ask counsel and the financial adviser to examine:
The initial term, renewal mechanism, and notice deadlines.
Any fixed increases or index-linked adjustment formulas.
Pass-through charges and expenses outside the base fee.
Service standards and remedies for underperformance.
Termination rights, buyout provisions, and exit charges.
Read these provisions together. A stated base price is not a ceiling if additional charges are permitted. Likewise, the practical value of termination rights depends on the conditions and costs attached to them. Confirm which provisions actually appear rather than assuming any are present.
For a longer holding period, build scenarios from documented obligations and clearly labeled assumptions. Separate contractual increases from discretionary spending and uncertain future costs. This keeps a planning exercise from becoming an unsupported promise about future dues.
Lincoln’s stated purchase schedule calls for 20% at contract, 10% at groundbreaking, and 10% at the fifth-floor concrete pour. These are purchase deposits, not association dues. They belong in an acquisition cash-flow schedule, not the recurring operating budget.
Confirm the applicable schedule in the binding purchase agreement. A payment milestone is not proof that it has occurred, and quoted dues should not be treated as final without the relevant association documents. These details also do not establish that the listed residences are completed.
Separate acquisition and ownership schedules make liquidity planning more useful: one addresses purchase commitments; the other addresses the continuing cost of holding the residence.
If the search also includes Arbor Coconut Grove, carry the same document checklist into that evaluation without assuming comparable budgets or services. Consistency matters more than a superficially similar monthly number.
For Lincoln and Opus, request approved budgets, unit assessment allocations, reserve schedules, and binding service agreements. Reconcile the exact residence, budget period, service scope, and capital assumptions before ranking either on cost. The better fit is the property whose documented obligations support the experience the buyer wants to own.
For a considered approach to Coconut Grove ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe Lincoln Coconut Grove is listed at 2650 Lincoln Avenue, Miami, FL 33133.
Unit 302 is listed at $2,113 monthly, Unit 406 at $2,180, and Unit 205 at $3,461. These are listing-level figures rather than verified final ownership obligations.
The annualized figures are $25,356 for Unit 302, $26,160 for Unit 406, and $41,532 for Unit 205. They assume no increases or additional assessments.
No. Taxes, owner insurance, financing, interior upkeep, and potential assessments should be modeled separately.
Listed inclusions include security, common-area upkeep, building insurance, roof repairs, trash removal, amenities, cable TV, elevators, hot water, management, parking, and water. Confirm the scope and limits in the applicable documents.
No. A listed contribution does not establish the reserve balance, funding adequacy, or future capital requirements.
Not on the figures presented. A complete Opus association budget and detailed binding service agreements are needed for a like-for-like comparison.
No verified escalators are established for either project. Buyers should review binding agreements for adjustment formulas, pass-through charges, renewal terms, and exit costs.
No. The published schedule of 20% at contract, 10% at groundbreaking, and 10% at the fifth-floor concrete pour concerns purchase deposits, subject to confirmation in the binding agreement.
Request approved association budgets, unit assessment allocations, reserve schedules, and binding service agreements. Reconcile the budget period and service scope before drawing cost conclusions.