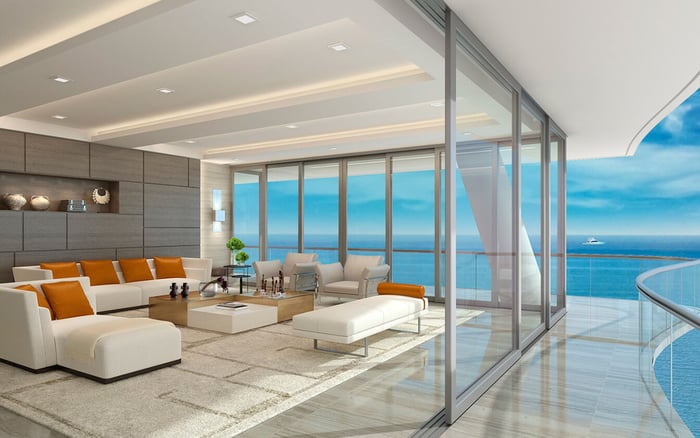
A Montreal-to-Surfside relocation scenario puts family-office governance in focus: separate purchase approvals from signing authority, preserve the transaction record, and keep vendors outside financial decision-making.
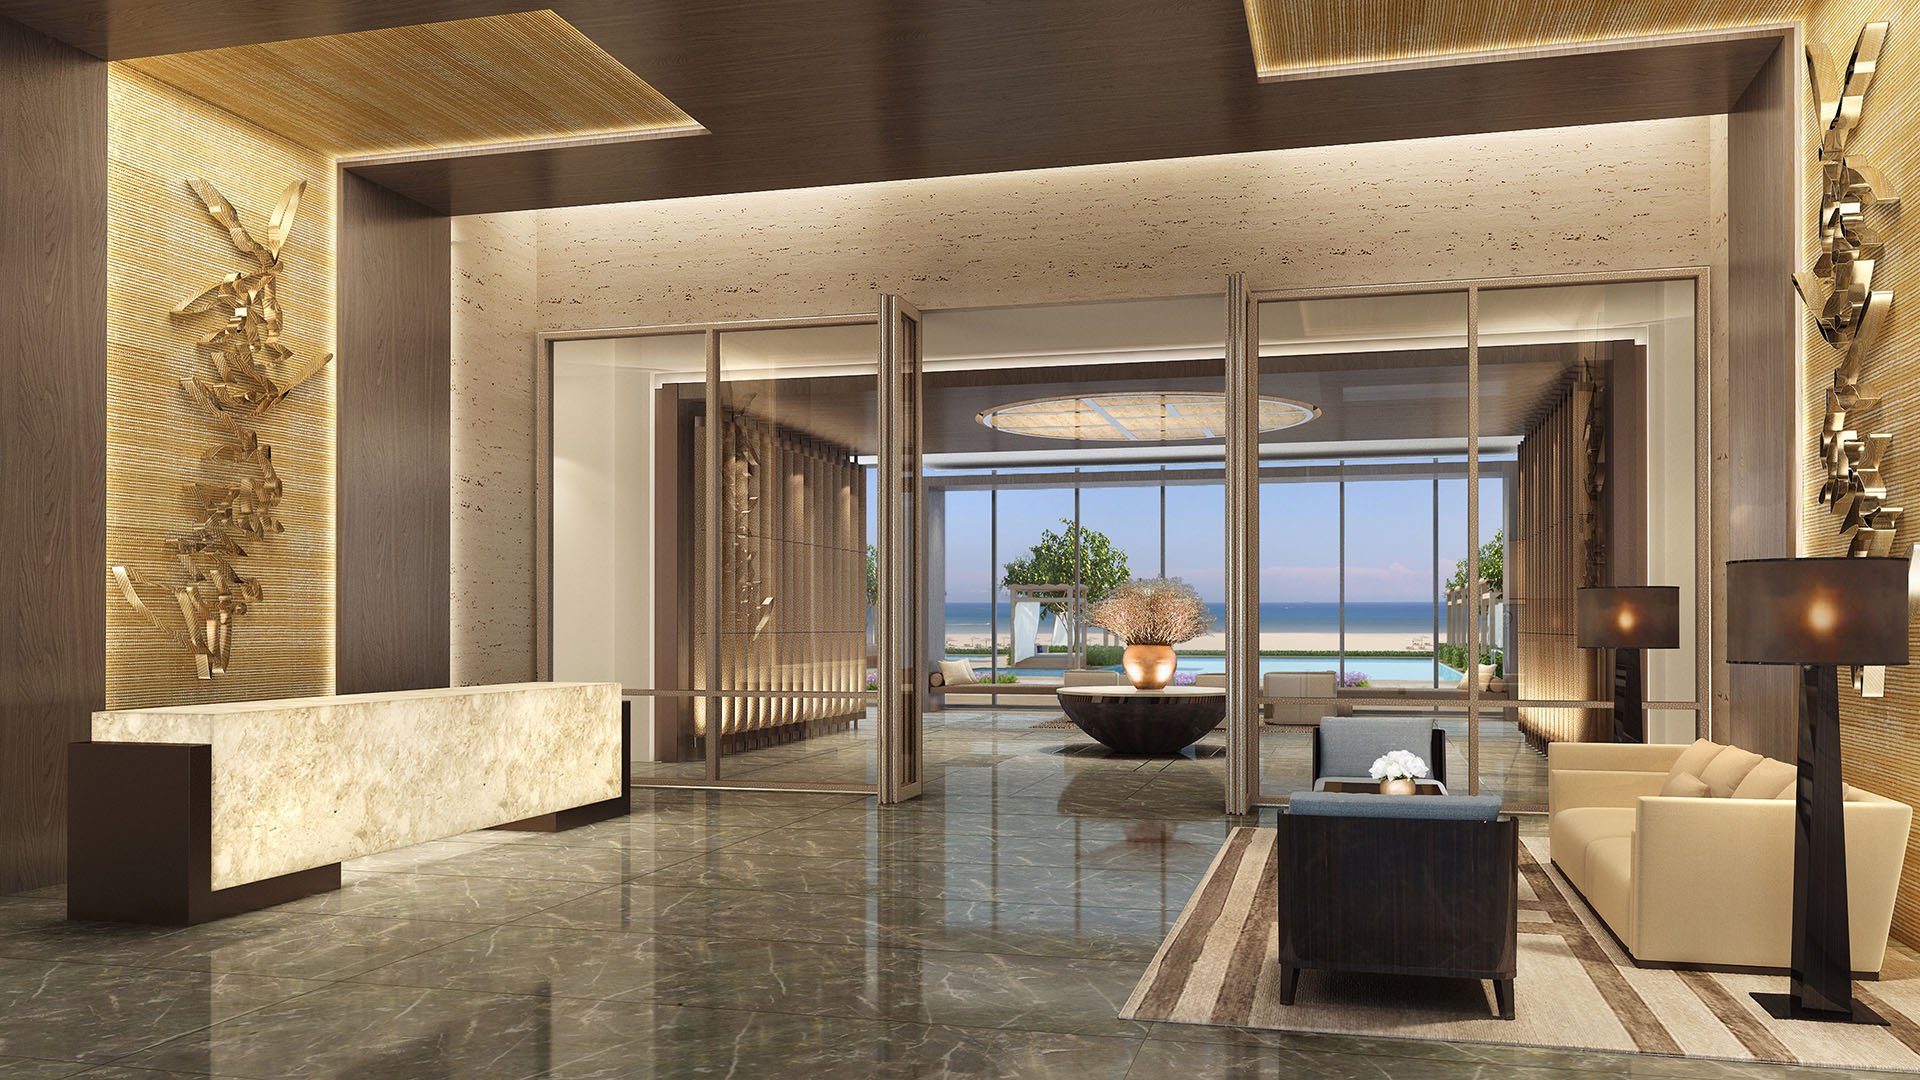
For a Montreal family considering a move to Surfside, selecting a residence is only part of the transition. The quieter work is deciding who may approve the acquisition, who can bind the purchasing entity, where records will be kept, and which outside professionals may access them. A beautiful address should not require an improvised decision-making structure.
This is a planning scenario, not an account of a completed relocation. A family evaluating The Surf Club Four Seasons Surfside could begin with a simple distinction: choosing a home, authorizing its purchase, signing its documents, and releasing its funds are separate decisions. Each deserves separate treatment, even when the same principal participates in all four.
The controls below are operational recommendations, not statements of Montreal-specific relocation law or Surfside-specific closing requirements. Their purpose is to clarify the family's intentions before the transaction becomes time-sensitive.
A qualifying family office is excluded from the definition of investment adviser under the federal Investment Advisers Act. Qualification requires more than adopting the family-office name. The office must advise only qualifying family clients, be wholly owned by family clients, remain exclusively controlled by family members or family entities, and not hold itself out publicly as an investment adviser.
Ownership and control are distinct tests. A family connection likewise does not automatically establish eligibility for every trust, charitable organization, or company. Certain structures can qualify, as can qualifying key employees, but the definitions and conditions matter.
Before reorganizing around a Florida residence, ask counsel to examine the office's advised clients, ownership, and control separately from the proposed property acquisition. Neither purchasing a residence nor relocating its principals resolves the office's eligibility. The exclusion concerns federal investment-adviser status; it is not blanket relief from unrelated obligations.
A useful internal purchase approval should identify the proposed buyer, the property under consideration, the approved financial commitment, and the decisions reserved to the family. For a hypothetical acquisition at Arte Surfside, the office could keep the residential selection brief separate from the authority record. Lifestyle preferences belong in the former; permission to commit capital belongs in the latter.
Create an authority matrix with named roles rather than relying on familiar relationships. Distinguish the person recommending the purchase, the person approving commercial terms, the authorized signer, the payment initiator, and the payment approver. Where staffing permits, consider separating initiation from approval.
Define what triggers renewed approval. A change in purchasing entity, an increase in the approved commitment, or a material contract amendment could require the decision to return to the designated principal or committee. Set those internal triggers before negotiations, rather than inventing them as discussions unfold.
Finally, establish an escalation route if a principal is unavailable. A named backup should act only within authority confirmed for the transaction-not simply because that person has handled family matters before.
Internal approval and legal signing authority are not interchangeable. The office's matrix records its intended process; counsel should confirm who can bind the actual buyer and which supporting documents are appropriate. Do not assume that an executive title, family relationship, or prior transaction establishes authority for this purchase.
A recommended closing-authority file would bring together the buyer's confirmed identity, counsel-reviewed authority documents, the approved transaction terms, and any limits on delegated action. The closing team should know which version is current and whom to contact when a document changes.
If the search includes Ocean House Surfside, apply the same discipline without assuming anything about the project's contracts or closing arrangements. The control belongs to the buyer's process, not to a presumed building-specific procedure.
Before execution, check the proposed signature documents against the approved buyer and terms. If anything differs, pause for confirmation. Convenience should not substitute for documented authority.
The federal family-office rule itself imposes no reporting, recordkeeping, or other compliance requirements. That narrow point creates neither a universal exemption from document-retention duties nor a retention period for a cross-border property transaction.
Ask counsel to define an appropriate retention schedule for the relevant entities, records, and obligations. Address Canadian and Florida questions expressly rather than relying on a generic office-wide deletion policy. Any proposed cross-border records access or transfer should receive its own review.
Build one controlled transaction file with clearly separated categories: approvals, authority documents, agreements and amendments, payment verification, closing records, and vendor instructions. Preserve the approved version of a decision alongside the documents implementing it. A signed agreement alone may not explain why a later change was authorized.
Assign a records owner and limit access by role. Consider version history, access logging, and a documented process for suspending deletion when counsel directs preservation. These are recommended controls, not prescribed features of the family-office exclusion.
A Florida title-agency escrow account protects funds held on behalf of others, generally for a real-property settlement. The escrow agent holds those funds until closing. That function should remain distinct from the family's internal decision about who may authorize a payment.
For the office, consider requiring independent verification of payment instructions through a trusted contact route established separately from the message requesting payment. A change in destination details should trigger fresh verification and approval. Retain a record of who checked the instructions and who authorized release.
Set equally clear boundaries for outside vendors. A designer might receive specifications and an approved purchasing allowance without receiving closing documents or unrestricted banking information. A relocation coordinator might receive scheduling details without authority to alter contractual commitments.
If The Delmore Surfside enters the family's consideration, vendor planning can follow the same structure: define the scope, fee approval, permitted information access, and escalation contact before work begins. This is a proposed buyer-side protocol, not a description of the project's policies.
Before closing, hold a brief readiness review: confirm that approval remains current, signing authority has been checked, payment details have been independently verified, and the records owner knows what to collect. Unresolved exceptions should have a named decision-maker, not a chain of informal messages.
Afterward, reconcile the final transaction record, close unnecessary vendor access, and document responsibility for continuing property administration. A move from Montreal to Surfside should leave the family with more than a new address. It should leave a clear account of who decided, who acted, and where the evidence is preserved.
Explore your next South Florida residence with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. It presents a planning scenario for a family considering a Montreal-to-Surfside move and a residential acquisition.
It excludes a qualifying family office from the federal Investment Advisers Act definition of investment adviser. It does not provide blanket relief from unrelated legal obligations.
No. The office must be wholly owned by family clients and exclusively controlled by family members or family entities, alongside the rule's other conditions.
No. Certain trusts can qualify, but they must satisfy the rule's conditions rather than merely have a family connection.
No. The rule itself imposes no recordkeeping requirements, but that does not eliminate retention duties arising elsewhere; counsel should define the applicable schedule.
As a recommended practice, it should identify the proposed buyer, property, approved financial commitment, and decisions reserved to the family. It should also define when changed terms require renewed approval.
It should not be treated as doing so. Counsel should separately confirm who can bind the actual buyer and which authority documents are appropriate.
Dual approvals are presented here as an operational recommendation, not an established legal mandate. The office can consider separating payment initiation from approval where staffing permits.
It protects funds held on behalf of others, generally for a real-property settlement. The escrow agent holds escrow funds until closing.
A recommended approach is to define each vendor's scope, spending permissions, information access, and escalation contact before work begins. Access should be limited to the assignment and reviewed when it ends.