A disciplined purchase at Opus Coconut Grove separates assessment disclosure, contractual payment responsibility, and proof of payoff. Here is how to review installment schedules, negotiate seller credits, and structure an assessment-related escrow holdback without confusing it with developer-deposit protection.
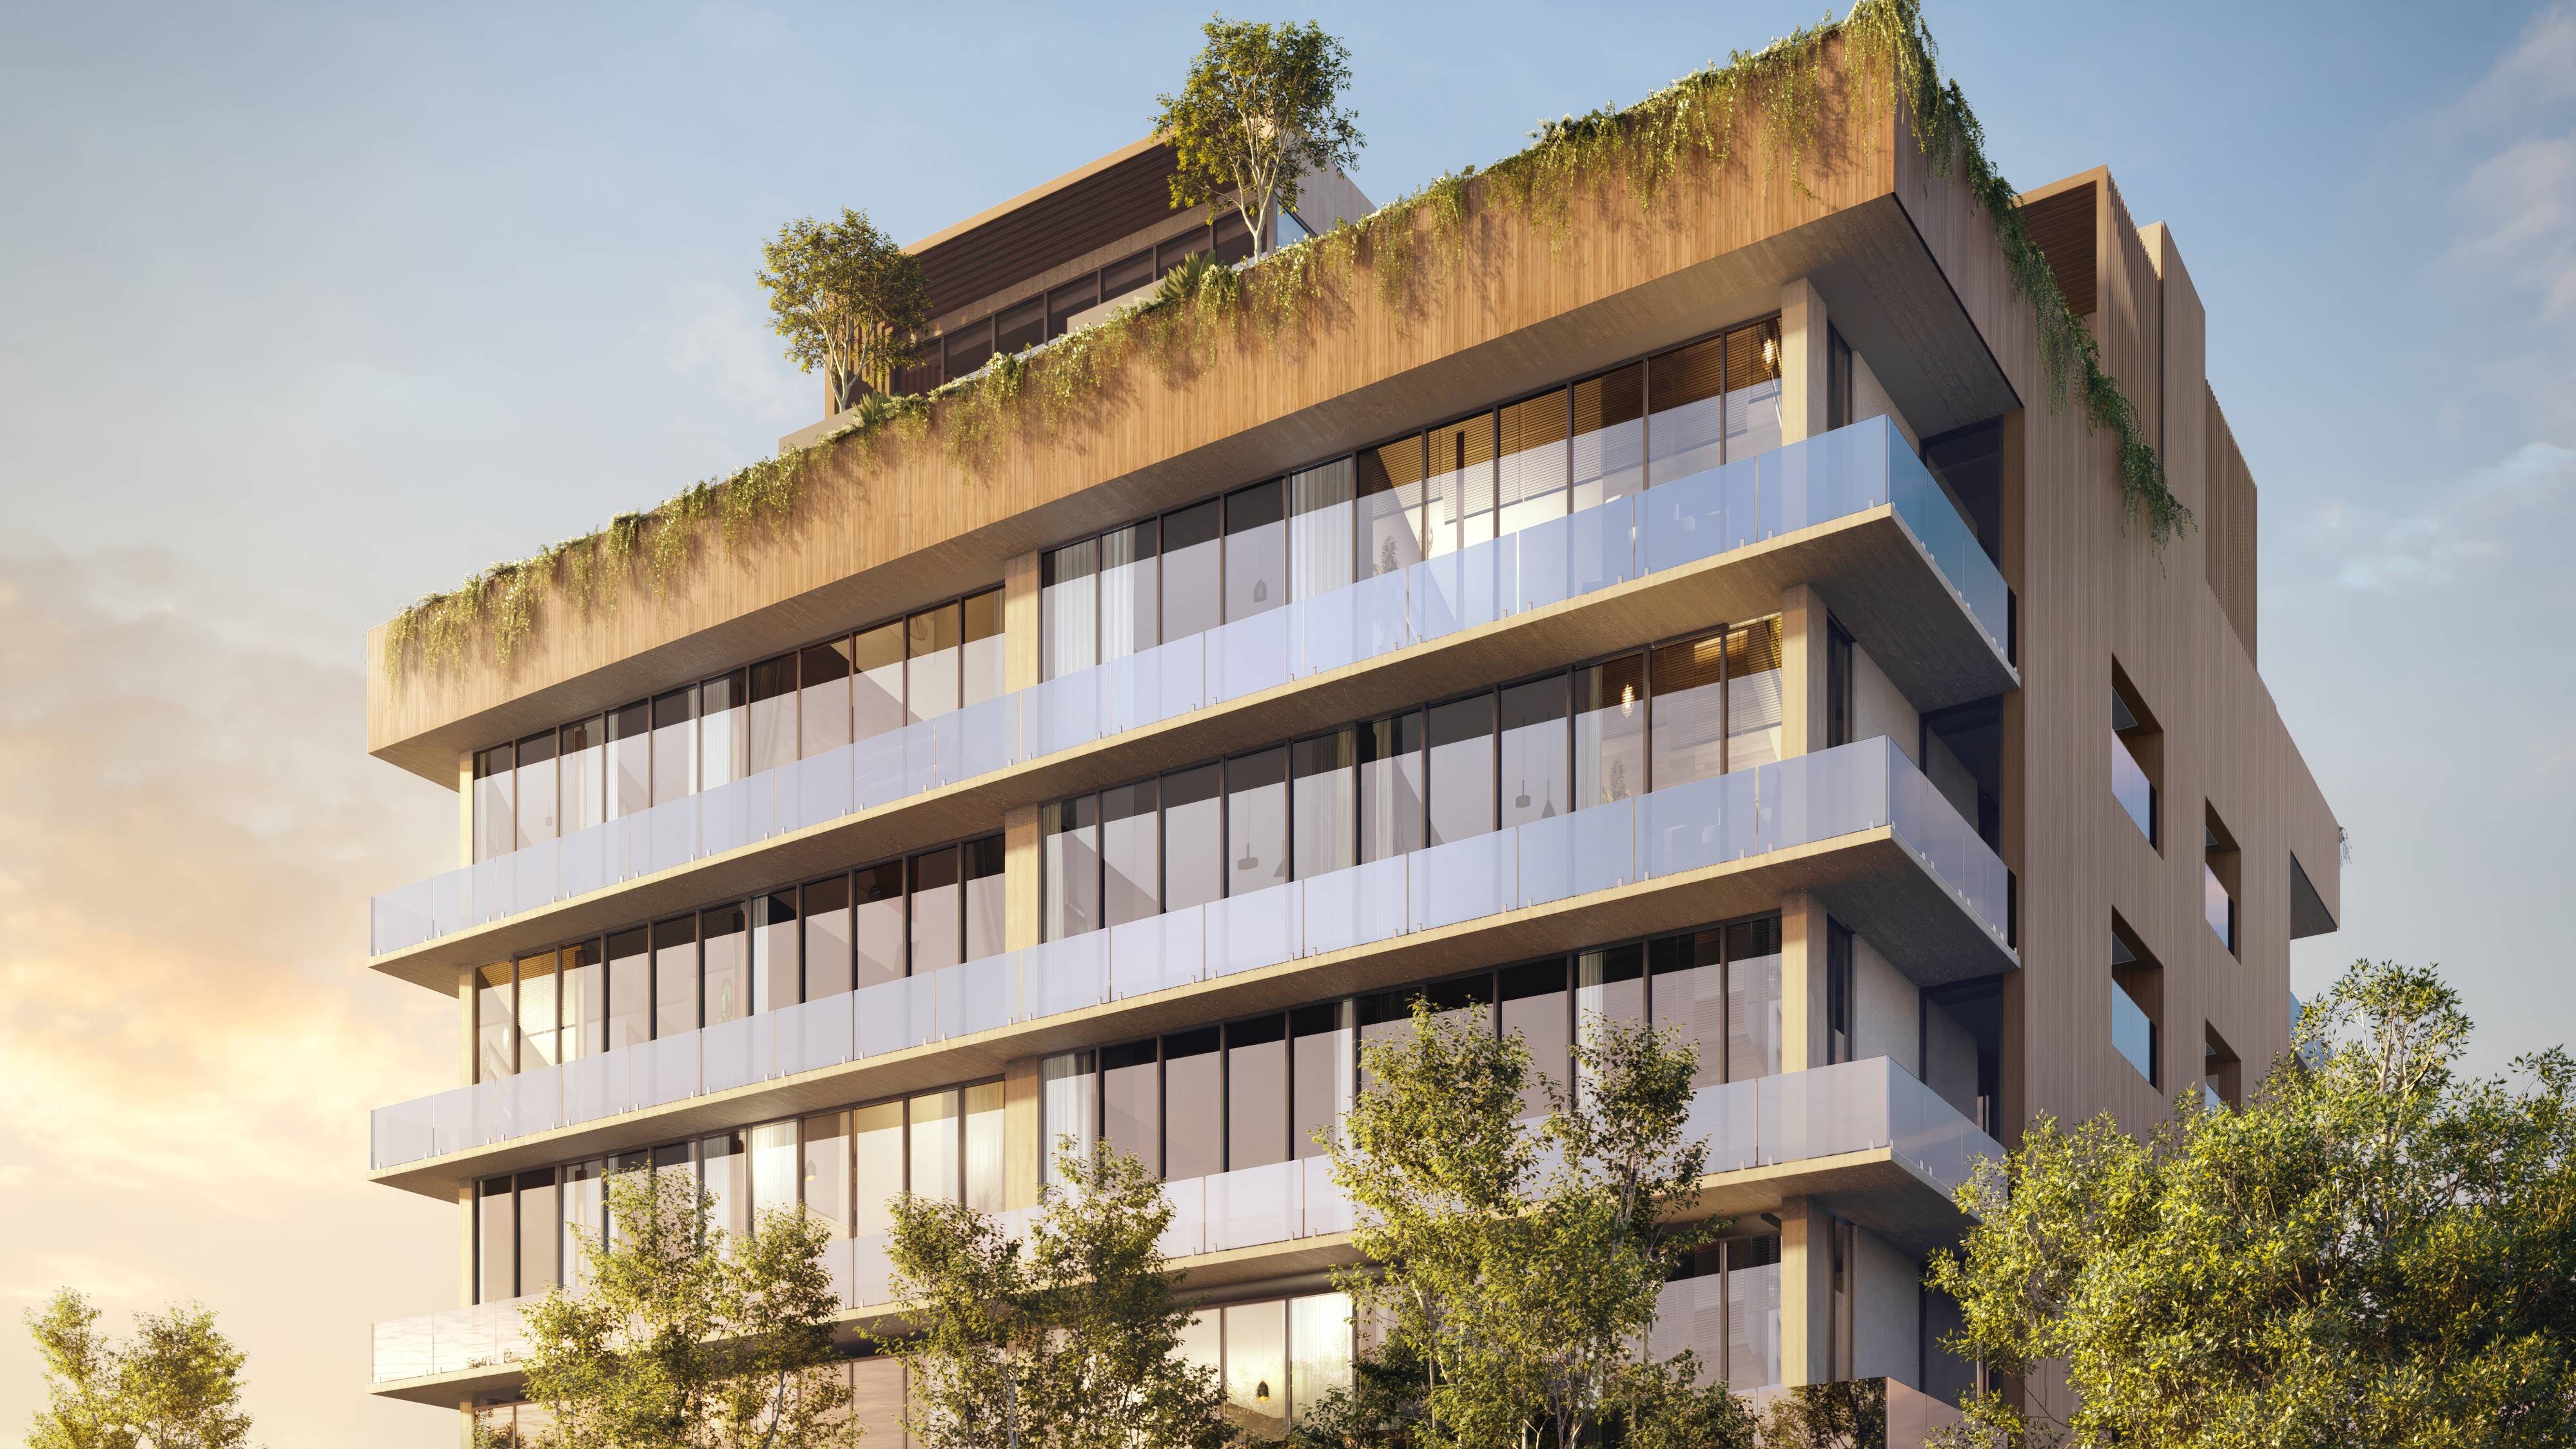
At Opus Coconut Grove, the purchase conversation should be as precise about association obligations as it is about the residence itself. Located at 3137 SW 27th Avenue, Miami, FL 33133, OPUS is a six-story condominium with 14 residences: 12 three-bedroom homes and two four-bedroom penthouses. Boutique scale is a defining characteristic, not a reason to set assessment risk aside.
For a buyer, three questions require separate answers: what the association has approved, who has agreed to pay, and whether payment has reached the association. A negotiated concession addresses only part of that sequence. Neither a seller credit nor an attractive purchase price establishes that the unit's account is clear.
Establish any assessment amount, installment calendar, or reserve position through current transaction documents. Do not infer either an existing assessment or an assessment-free position from the project's size or presentation.
Start with the written assessment notice and an itemized unit account. Florida condominium law requires notice stating a special assessment's specific purpose. Collected funds must be used for that purpose, subject to statutory provisions addressing excess funds. The notice is therefore an essential reference for identifying the obligation being negotiated.
Request regular dues, approved special assessments, installment dates, unpaid balances, interest, and other relevant charges. Separate the total obligation from the amount immediately due. An installment payable after closing still belongs in the purchase review, even if the seller's current account shows no overdue payment.
A practical schedule should distinguish payments already made, amounts due before closing, and installments due afterward. Reconcile each entry against the association ledger rather than relying on a seller's summary. This turns an ambiguous discussion about who will cover an assessment into a defined allocation of identifiable charges.
An estoppel certificate identifies unit-level association obligations, including regular assessments, special assessments, outstanding amounts, and additional amounts scheduled during its effective period. The association generally must issue it within 10 business days of a written or electronic request from an authorized requester.
Order it early enough for review, then confirm that its effective period covers the actual closing. If the closing date changes, revisit that coverage rather than assuming an earlier certificate remains sufficient. Compare the certificate with the ledger and assessment schedule, and resolve differences before funds are disbursed.
The estoppel is not a comprehensive review of the condominium's finances or future capital needs. An assessment under discussion but not formally approved may not appear. Review board notices, minutes, budgets, reserve information, and pending capital-project records separately.
For buyers also considering Arbor Coconut Grove, that distinction provides a consistent diligence standard: compare documented obligations and financial records, not assumptions about what a project's positioning implies.
The purchase contract should explicitly allocate responsibility for a levied assessment, including installments due after closing. Avoid language that settles only the next payment while leaving the remaining obligation uncertain. Identify the assessment and specify which party bears each covered amount.
If the negotiated arrangement requires the seller to pay in full, specify payment before closing or from closing proceeds. An informal promise to handle the balance later is not equivalent to a documented payment mechanism. Have Florida condominium counsel review the allocation and any seller obligation intended to survive closing.
Keep two layers distinct: the buyer-seller agreement and the association's collection rights. Florida purchasers can be jointly and severally liable with the previous owner for unpaid assessments. A contractual promise by the seller therefore does not remove the need to verify payment to the association.
A seller credit can allocate the economic cost of an assessment, but it is not a receipt. The essential question is whether the negotiated arrangement results in actual payment of the covered association obligation or leaves the buyer responsible for paying after receiving the credit.
Before accepting the structure, reconcile the credit with the itemized amount and installment schedule. Identify who will transmit payment, when payment will occur, and what evidence will establish that it has been applied to the unit's account. If the credit and obligation differ, resolve the difference explicitly.
For investment analysis, distinguish price relief from payment execution. Whether the comparison includes The Lincoln Coconut Grove or another residence, a concession is not proof that an association balance has been cleared.
An assessment-related escrow holdback is negotiated contractual protection, not an automatic statutory remedy. It may be considered when the parties need a defined mechanism to retain funds while a covered payment or reconciliation is completed. Its usefulness depends on the agreement's terms.
A proposed holdback should identify:
The specific assessment and obligations covered.
The escrow amount and designated escrow agent.
Objective conditions for releasing funds.
An outside deadline for resolving the holdback.
Responsibility for any shortfall and treatment of any surplus.
Release conditions should require evidence of payment or reconciliation, not merely the occurrence of closing. Counsel should help define which documents satisfy those conditions and how any surviving seller obligation relates to the retained funds.
A holdback should not substitute for understanding the underlying charge. First establish what is owed and how it is allocated; then determine whether escrow provides an appropriate way to execute that agreement.
Florida's developer-deposit escrow provisions address certain payments exceeding 10% of the sale price before construction completion. Those provisions are distinct from a negotiated resale assessment holdback. The shared word escrow does not make the protections interchangeable.
For a purchaser weighing OPUS alongside Four Seasons Residences Coconut Grove, the useful question is which transaction structure applies to the particular purchase. Have counsel distinguish developer-deposit handling from any assessment-related arrangement rather than assuming one answers the other.
The final review should bring together the current estoppel, association ledger, seller disclosures, contract allocation, and settlement statement. Each should reflect the same covered assessment, payment responsibility, and movement of funds. Resolve discrepancies before closing rather than leaving them to a post-closing understanding.
For an ultra-premium purchase, precision is part of the value proposition. The aim is not to eliminate every possible future association expense. It is to understand current obligations, review pending financial decisions, and work with Florida condominium counsel to make the negotiated payment structure enforceable and verifiable.
For a discreet perspective on your Coconut Grove purchase, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationOPUS Coconut Grove is located at 3137 SW 27th Avenue, Miami, FL 33133.
OPUS is described as a six-story condominium with 14 residences, comprising 12 three-bedroom homes and two four-bedroom penthouses.
No. Establish any approved assessment, unit balance, and installment schedule through current transaction documents rather than assuming an assessment-free position.
It identifies unit-level association obligations, including regular and special assessments, outstanding amounts, and additional amounts scheduled during its effective period.
The association generally must issue it within 10 business days of a written or electronic request from an authorized requester.
No. An assessment being discussed but not formally approved may not appear, so buyers should also review board records, budgets, reserve information, and pending capital projects.
The purchase contract should explicitly allocate those installments between buyer and seller. Do not leave responsibility to an informal understanding.
No. Verify actual payment to the association because a credit alone does not clear the unit's obligation, and purchasers can face liability for unpaid assessments.
It should identify the covered assessment, escrow amount, escrow agent, objective release conditions, outside deadline, and treatment of shortfalls or surplus funds.
No. Developer-deposit provisions address certain payments exceeding 10% of the sale price before construction completion; an assessment holdback is separately negotiated contractual protection.