For an art collector financing a South Florida residence with a securities-backed line, reconstruction value, bespoke interiors, code-compliance coverage and liquidity deserve a coordinated review. The purchase price alone cannot answer the insurance question.
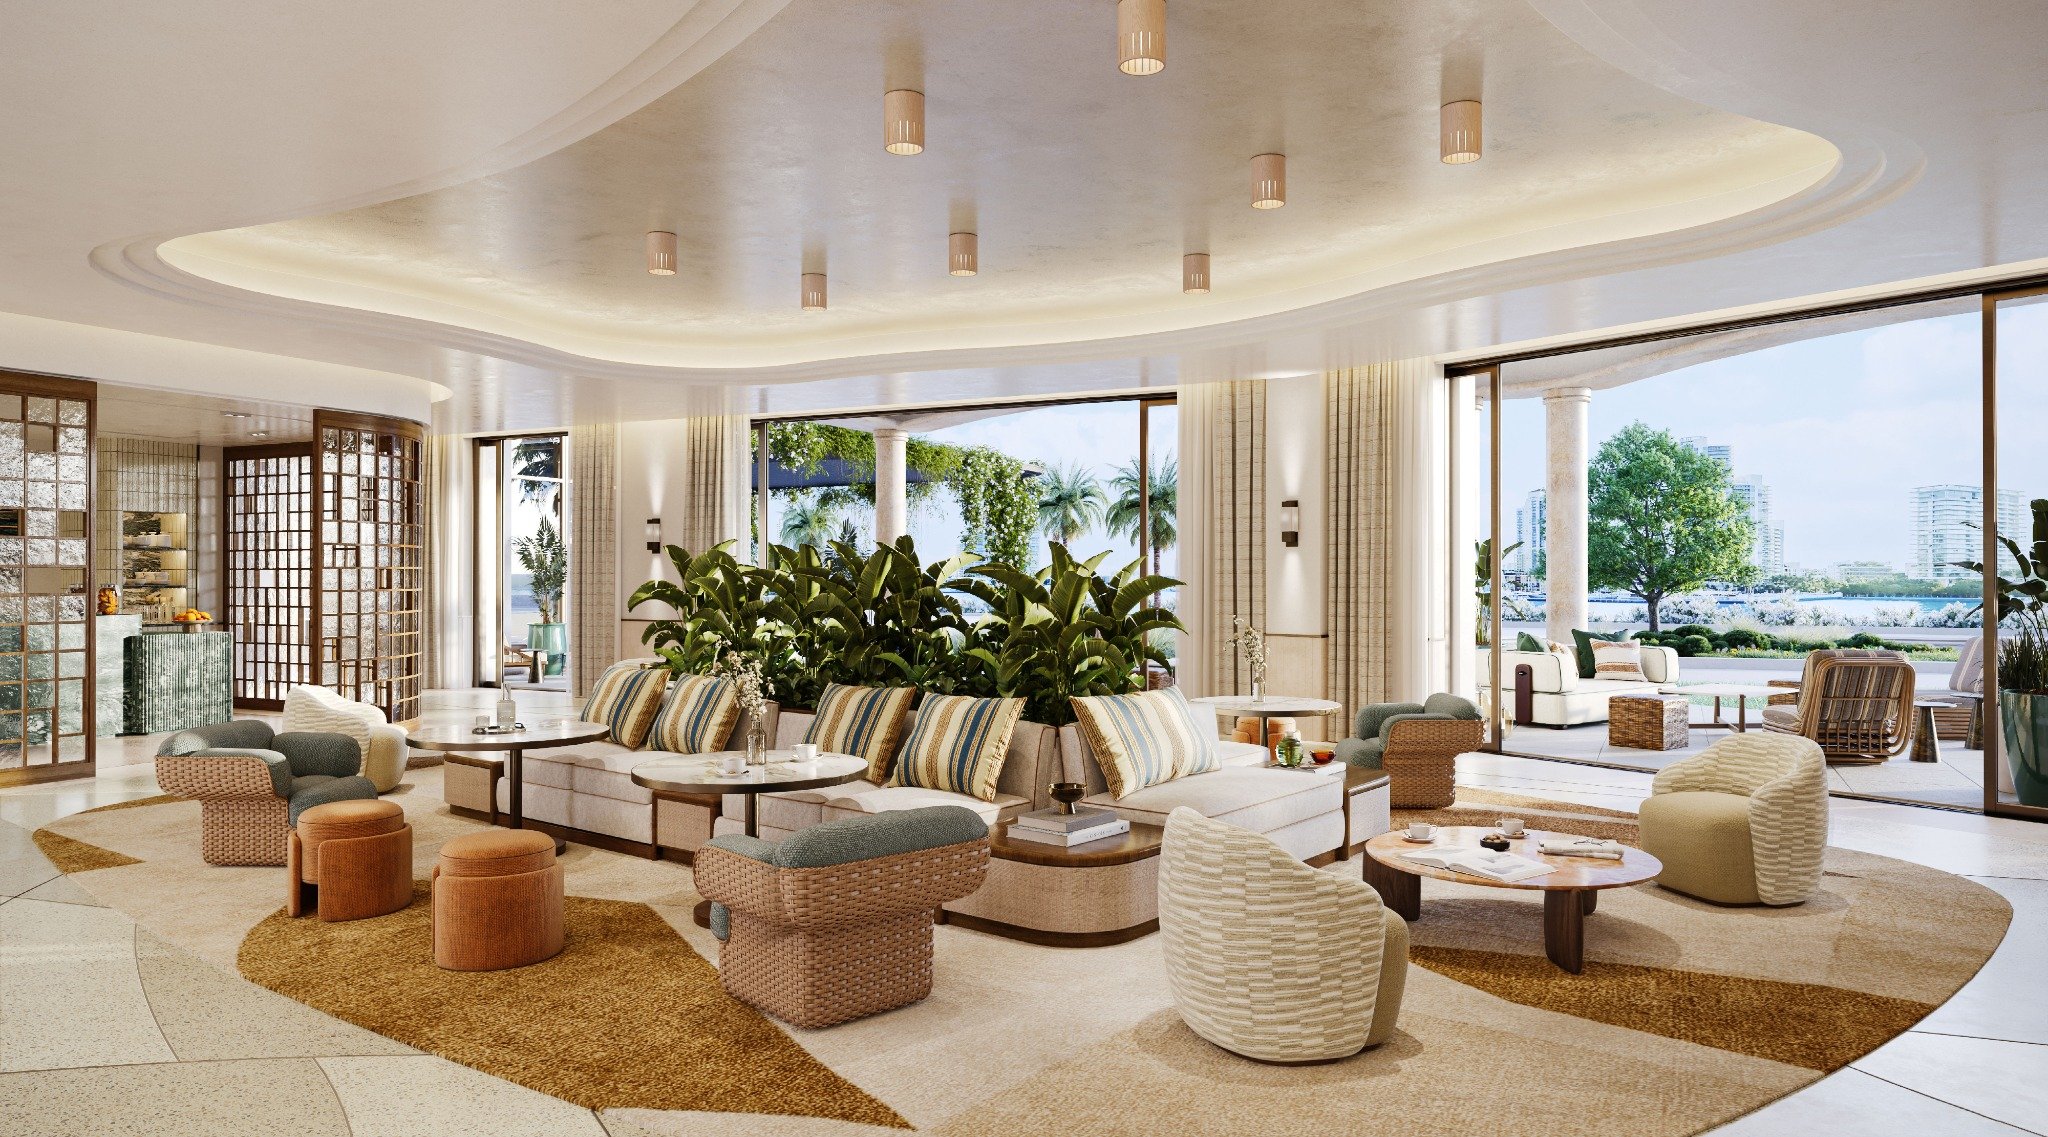
An art collector buying a South Florida residence is evaluating more than square footage. The home must accommodate a collection, reflect a particular design sensibility and fit within a broader financial plan. When a securities-backed line funds the acquisition or improvements, the insurance review warrants the same precision as the purchase.
The central distinction is simple: replacement cost concerns repairing or rebuilding the insured dwelling, not reproducing its resale price. A purchase valuation and a reconstruction valuation answer different questions. Neither substitutes for the other.
For a buyer considering The Residences at 1428 Brickell, the insurance question is not whether the limit resembles the acquisition price. It is whether the policy's insured scope and valuation reflect what would actually need to be restored. That distinction applies equally to a finished residence and one awaiting extensive personalization.
Start by identifying precisely what the proposed policy insures. For a condominium purchase, ask the insurance adviser to reconcile the unit policy, relevant building documents and proposed interior work. Do not assume a dwelling-level statutory rule resolves every question about a particular condominium policy.
Then separate the figures under discussion: acquisition price, reconstruction estimate, interior-improvement budget and collection valuation. Keep land value distinct from reconstruction cost rather than treating the full property price as an automatic dwelling limit.
Ask how the insurer established its figure: a software-generated estimate, an inspection-based assessment or a bespoke reconstruction appraisal. The label “replacement cost” does not, by itself, establish the depth of the valuation.
For a highly individualized residence, consider commissioning a detailed reconstruction appraisal and asking the insurer to reconcile it with its estimate. This is a review recommendation, not a universal statutory requirement. Resolve material differences before relying on the proposed limit.
A collector's renovation file should help an adviser understand the intended restoration standard. Consider assembling architectural drawings, finish schedules, contractor agreements, invoices and photographs. Identify custom millwork, stonework, integrated lighting and other interior improvements for explicit review rather than assuming a general estimate captures them.
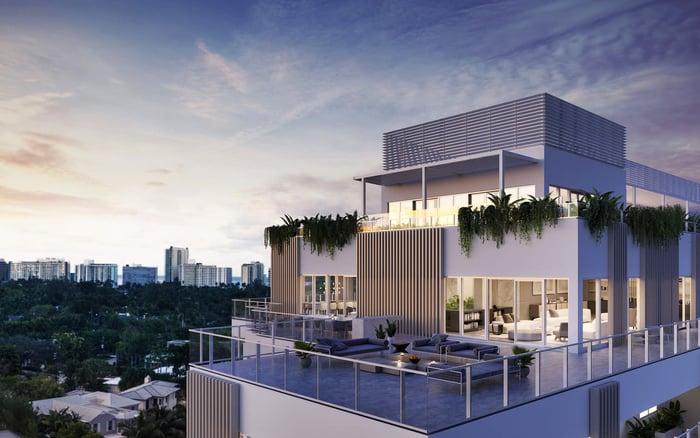
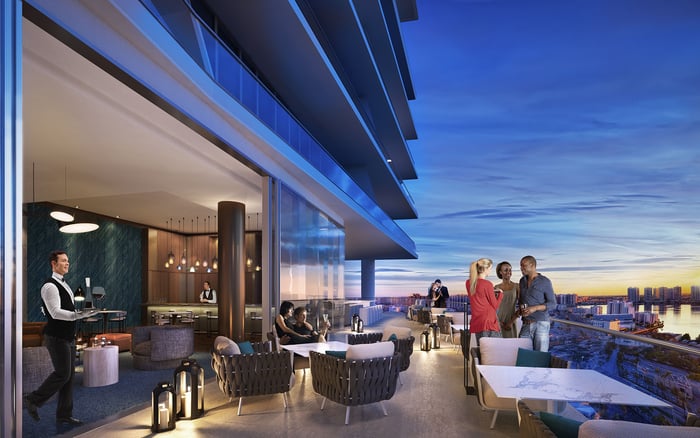
For a Miami Beach buyer evaluating The Perigon Miami Beach, this review is useful before approving a personalized interior scheme. The project provides a setting for the purchase decision, not evidence of any particular insurance arrangement or finish specification.
Ask the appraiser and insurance adviser to distinguish improvements attached to the residence from movable furnishings and artworks. Have them identify uncertain classifications in writing. The goal is not simply a longer inventory, but a clear allocation of items to the coverage under review.
Repeat that reconciliation when the design changes materially. Before accepting a valuation prepared ahead of a substantial renovation, check whether it still describes the completed home.
Ordinary replacement-cost protection and the cost of complying with applicable building laws require separate review. Ask the insurance adviser which code-compliance expenses the proposed policy covers and which require law-and-ordinance coverage.
Confirm the selected ordinance limit, how it is calculated and whether it is additional to or included within another policy limit. Have the adviser explain any applicable legal requirements and available coverage options for the particular residence rather than assuming a standard percentage applies.
Ask how the policy treats work involving damaged and undamaged portions of the property. Include a partial-loss scenario in the review rather than considering only a total rebuild, and request an explanation of any relevant triggers, restrictions or exclusions.
In Surfside, a purchaser considering The Delmore Surfside should ask an adviser to explain how these concepts apply to the proposed policy and insured interests. Confirm whether additional ordinance protection is available rather than presuming the initial proposal is the final option.
A replacement-cost policy is not an unlimited restoration commitment. Read the dwelling limit alongside the declarations, endorsements, exclusions and deductibles. Ask what the contract would require after a covered loss and which expenses fall outside the insured scope.
Do not use “replacement cost” and “extended” or “increased replacement cost” interchangeably. Ask whether an extension exists, what activates it and what limits apply. A reassuring phrase in a discussion is no substitute for an operative endorsement.
Ask whether the policy contains an insurance-to-value requirement or coinsurance provision and how any penalty would be calculated. These provisions require policy-specific review; they should not be presumed identical across insurers.
Finally, establish when the valuation was completed and whether it remains appropriate at renewal. Recency and completeness are separate tests: even a recent estimate must capture the residence's actual insured improvements.
For the collector using a securities-backed line, organize three parallel reviews: the residence, the artworks and the financing. Do not infer the treatment of a collection from the dwelling's replacement-cost wording. Ask the art-insurance adviser to confirm the relevant property, valuations and applicable terms independently.
Likewise, have the lending team explain the actual credit agreement rather than assuming how a property loss would interact with the facility. Confirm any insurance obligations, provisions concerning proceeds and conditions governing further borrowing. The executed documents-not the financing label-must answer these questions.
Build a liquidity discussion around a hypothetical repair event. Ask the advisers to identify potential out-of-pocket costs, applicable deductibles and any timing mismatch between expenses and recoveries. Do not count an undrawn facility as an assured rebuilding reserve without reviewing its contractual availability.
Before binding or renewing, request a concise written reconciliation of the insured property, reconstruction estimate, documented improvements, ordinance selection and relevant policy limitations. Keep the collection and financing reviews alongside it, while preserving their distinct contractual questions.
The objective is not to make every number match. It is to ensure each serves its proper purpose, without an unspoken assumption that purchase price, insurance limits and available credit are interchangeable.
For a discreet perspective on South Florida residences and ownership decisions, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Replacement cost addresses repairing or rebuilding the insured dwelling, while market value concerns its resale price.
No. Review the policy's limits, endorsements, exclusions and deductibles to understand the scope of protection.
Consider a detailed reconstruction appraisal and documentation of custom improvements. This is a review recommendation, not a universal statutory requirement.
Drawings, finish schedules, contractor agreements, invoices and photographs can help advisers reconcile the residence with its proposed insured valuation.
It addresses costs associated with applicable building laws and ordinances, a distinct issue from ordinary replacement-cost protection. The actual policy determines the operative coverage.
Ask the adviser to confirm the selected limit, how it is calculated and whether it is additional to or included within another policy limit.
No. Ask the adviser to confirm applicable legal requirements and coverage options for the particular policy and insured interests.
Yes. Ask how the policy treats damaged and undamaged portions and what triggers, restrictions or exclusions apply.
No. Confirm whether the policy includes an extension and review its triggers, conditions and limits separately.
Review the dwelling policy, collection coverage and executed credit agreement separately. Ask advisers to confirm insurance obligations, treatment of proceeds and contractual availability of further borrowing.