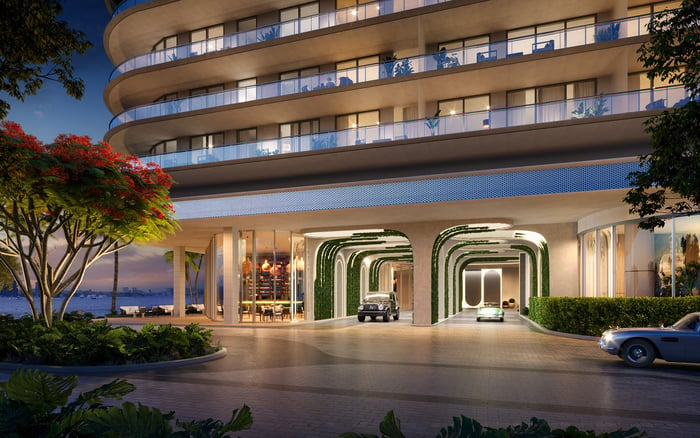
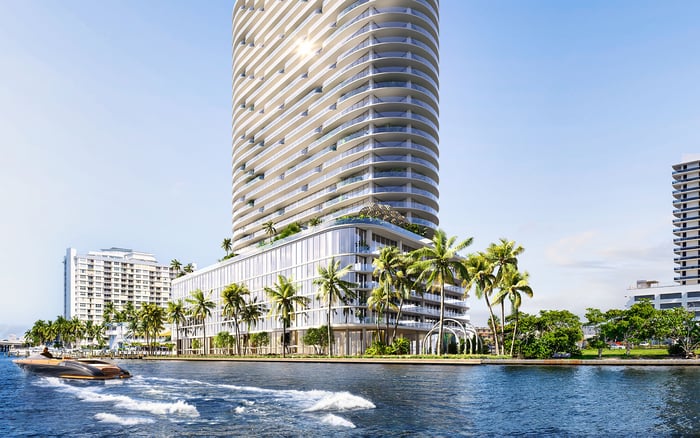
An Austin-to-North Bay Village move calls for more than a new address. Buyers should coordinate estate documents, community-property preservation, trust ownership and Miami-Dade homestead timing before finalizing title.
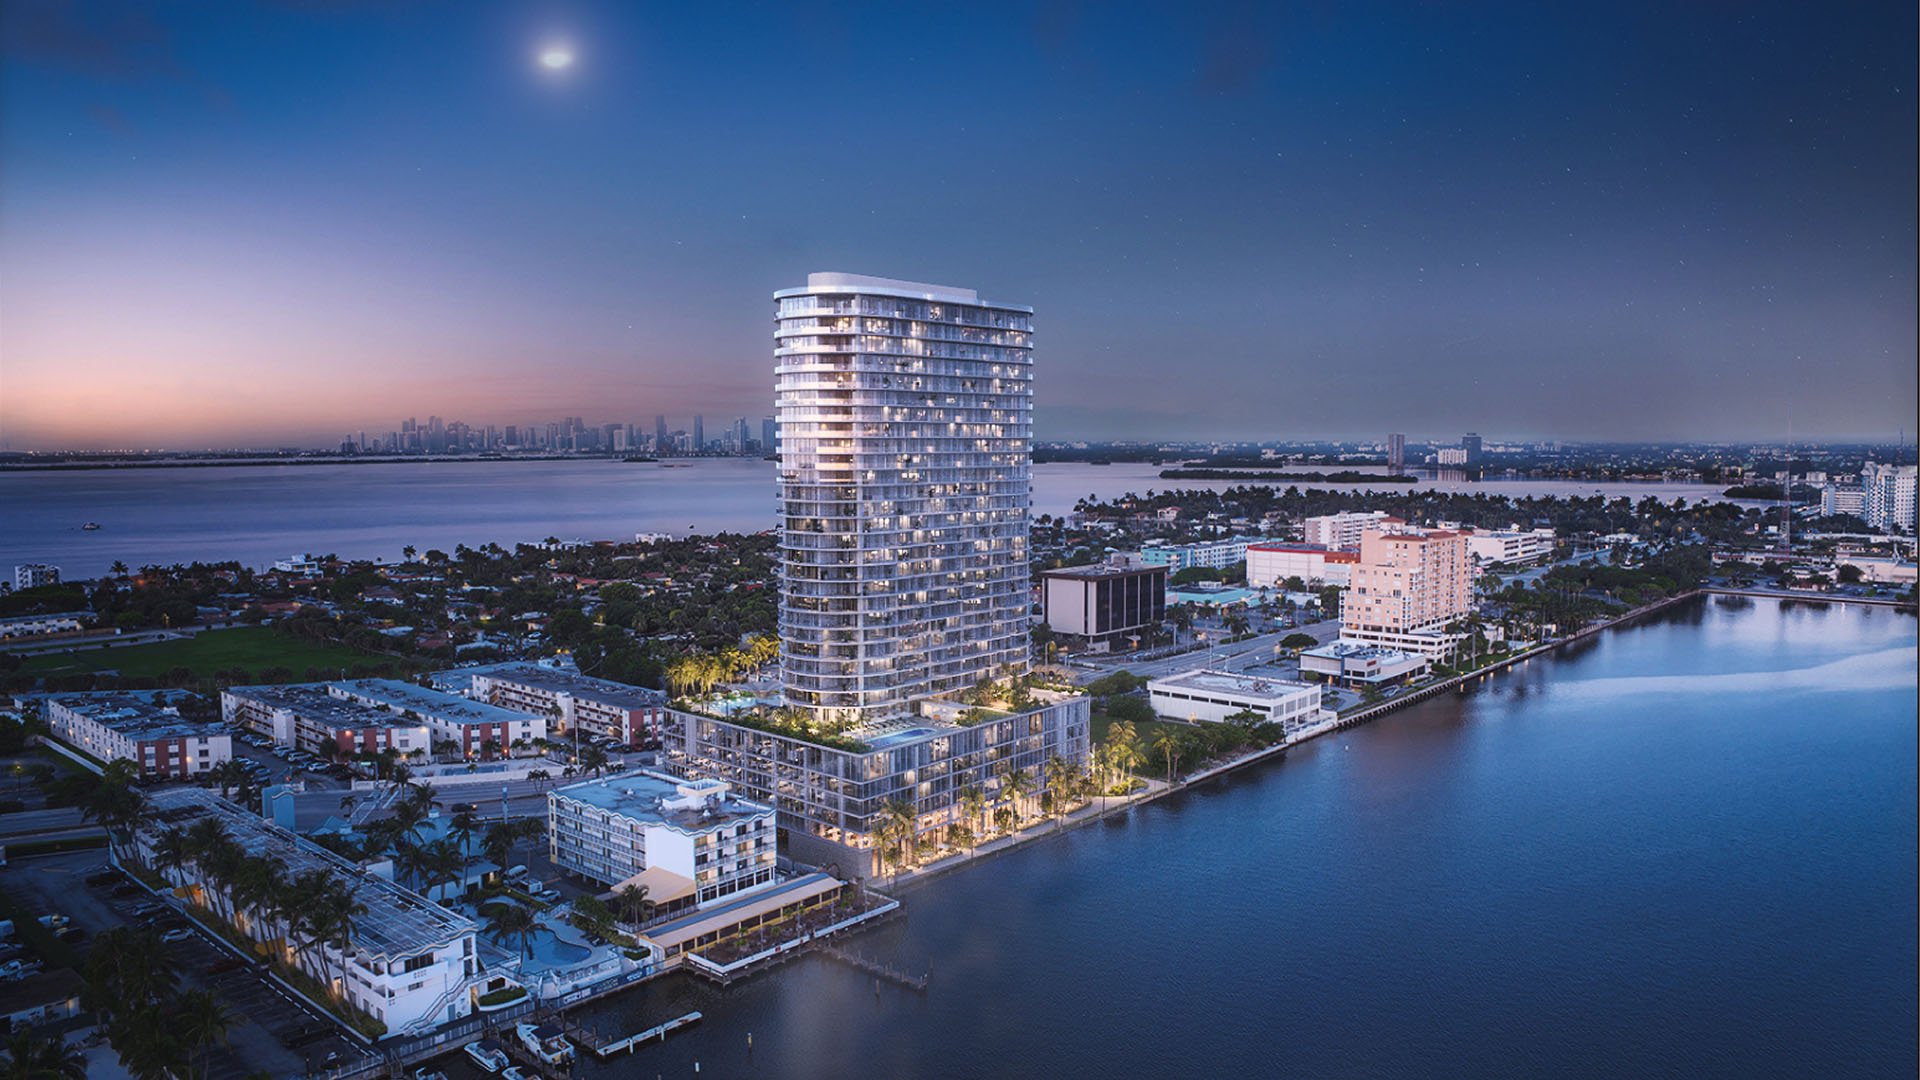
For an Austin household relocating to North Bay Village, selecting a residence is only part of establishing a Florida home. Equally consequential are the decisions about who owns it, how the estate plan treats it and whether its intended use supports a homestead tax exemption. Those questions deserve attention before closing-not when the first property-tax notice arrives.
A buyer considering Continuum Club & Residences North Bay Village should coordinate the proposed deed with estate counsel and a tax adviser while evaluating the purchase. The objective is not simply to place the property within an existing ownership structure. It is to ensure that ownership, occupancy and inheritance intentions work together under Florida law.
These are Florida and Miami-Dade considerations, not a separate village-specific estate regime. Whether the search stays within North Bay Village or extends to Miami Beach, planning begins with the household rather than the building.
A change of domicile warrants a Florida review of wills, revocable trusts, powers of attorney and health care directives. It does not mean every Texas document automatically becomes invalid or every asset changes marital-property character when its owners move.
Ask Florida estate counsel to distinguish documents that remain suitable from provisions that need revision. The review should cover both the existing estate plan and the proposed residence: how title will be held, who has the right to occupy the home and who is intended to inherit it.
For couples, this is also the time to make ownership assumptions explicit. A familiar Texas arrangement should not give way to standard Florida joint ownership merely because it appears convenient on closing paperwork. Document review and title selection are related tasks, but neither substitutes for the other.
Texas is a community-property state; Florida generally follows separate-property rules. That distinction makes the character of assets brought from Austin an important planning issue, particularly before transfers or retitling.
Qualifying community property can receive an inherited tax-basis adjustment on both spouses’ shares at the first death. Ordinary jointly owned spousal property generally receives an adjustment only on the deceased spouse’s share. These are potential differences for counsel and tax advisers to evaluate, not conclusions about any particular couple’s holdings.
Before converting assets to conventional Florida joint ownership, ask whether community-property preservation strategies are appropriate. Keep the questions distinct: what character does an asset currently have, what would a proposed transfer change and how might that affect a future basis adjustment?
The practical lesson is sequencing. Complete the preservation analysis before authorizing transfers, rather than assuming an estate-plan amendment after closing will address every consequence.
A revocable trust and Florida’s homestead tax exemption are not inherently incompatible. Florida recognizes qualifying legal or beneficial title, so a properly structured trust can qualify when the resident beneficiary retains the necessary ownership interest and right to occupy the home.
The words “revocable trust” alone do not establish eligibility. Counsel should examine the actual ownership and occupancy provisions alongside the proposed deed. Buyers considering an LLC or another entity need a separate analysis: control of an entity that owns a residence is not interchangeable with qualifying ownership of the residence itself.
For a purchase at Shoma Bay North Bay Village, the central question is whether the buyer’s intended ownership structure supports use as a permanent residence. Neither a project name nor a purchase price can answer that question, and no trust arrangement should be treated as automatically approved for homestead purposes.
“Homestead” is not a single, all-purpose approval. The property-tax exemption, creditor protection and restrictions on inheritance are distinct issues. Eligibility for the tax exemption does not establish that every other homestead protection applies.
Florida’s restrictions on devise-meaning the transfer of property at death through an estate plan-and spousal rights require review before deciding who will inherit the North Bay Village home. An intended distribution in a will or trust should be tested against the applicable homestead rules, not simply carried forward from the Texas plan.
Ask counsel to evaluate tax-exemption compatibility and inheritance compatibility separately. A favorable answer about trust ownership is not a complete answer about the surviving spouse or eventual beneficiaries.
Miami-Dade generally requires qualifying ownership and permanent residence as of January 1 of the tax year for which the homestead exemption is sought. March 1 is the standard application deadline. One date establishes eligibility; the other governs the ordinary filing timetable.
A buyer who purchases and establishes permanent residence after January 1 generally cannot qualify on that basis until the following tax year. For someone evaluating Tula Residences North Bay Village, the relevant dates are when qualifying ownership and permanent residence will actually exist-not simply when the property is selected.
Applications go through the county property appraiser using Form DR-501. Evidence relevant to permanent residency includes a Florida driver’s license or identification card, vehicle registration, voter registration and a prior-year federal tax return. Prepare a consistent residency record rather than treating any single document as sufficient on its own.
Do not equate a later purchase with an entirely non-homestead tax bill, or assume that missing the standard deadline necessarily resolves every filing question. Confirm the particular circumstances with the property appraiser.
Second-home ownership alone does not satisfy the permanent-residence requirement. A North Bay Village property used only for vacations or investment does not qualify for the homestead tax exemption on that basis. Permanent residence by a legal or natural dependent is also recognized on Form DR-501 and warrants review where relevant.
Coordinate any existing Austin homestead benefit with the move. A Florida applicant cannot simultaneously claim a residency-based property-tax benefit in another state.
Florida’s Save Our Homes mechanism limits annual increases in a homesteaded property’s assessed value, separately from the exemption itself. Its portability concerns qualifying Florida homesteads; it does not transfer an Austin exemption into Miami-Dade.
The strongest preparation is coordinated: review the Texas documents, evaluate marital-property preservation, confirm the proposed title and occupancy rights, test inheritance intentions and calendar the residency and filing dates. Rely on Florida estate counsel and tax advisers for household-specific conclusions.
A carefully selected residence deserves an equally deliberate ownership plan-one that supports daily life without leaving succession and tax compatibility to assumption.
Explore North Bay Village residential possibilities with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Relocation calls for a Florida review of wills, trusts, powers of attorney and health care directives, rather than an assumption that every document is invalid or needs replacement.
Texas is a community-property state, while Florida generally follows separate-property rules. Couples should evaluate asset character and preservation strategies before converting assets to standard Florida joint ownership.
Qualifying community property can receive a basis adjustment on both spouses’ shares at the first death, while ordinary spousal joint ownership generally receives one only on the deceased spouse’s share. Tax advisers should evaluate the treatment of specific assets before transfers.
Yes, a properly structured revocable trust can qualify when the resident beneficiary retains the necessary ownership interest and right to occupy the home. Eligibility depends on the actual arrangement.
No. Control of an entity that owns the home is not equivalent to qualifying ownership of the residence, so buyers should confirm eligibility before taking title.
No. Florida homestead inheritance restrictions and spousal rights require a separate review, and tax eligibility does not establish every creditor protection.
January 1 is the qualifying ownership and permanent-residence date for the applicable tax year. March 1 is the standard homestead application deadline.
You generally cannot qualify on that basis until the following tax year. That does not, by itself, establish the treatment of every component of the current property-tax bill.
The application uses Form DR-501 through the county property appraiser. Relevant residency evidence includes Florida identification, vehicle registration, voter registration and a prior-year federal tax return.
A Florida applicant cannot simultaneously claim a residency-based property-tax benefit in another state. Save Our Homes portability applies to qualifying Florida homesteads, not an Austin exemption.