A South Beach acquisition and a New York residency exit are separate milestones. This private-client checklist aligns domicile evidence, travel records, former-home documentation, and the first Miami-Dade homestead application without confusing closing with relocation.
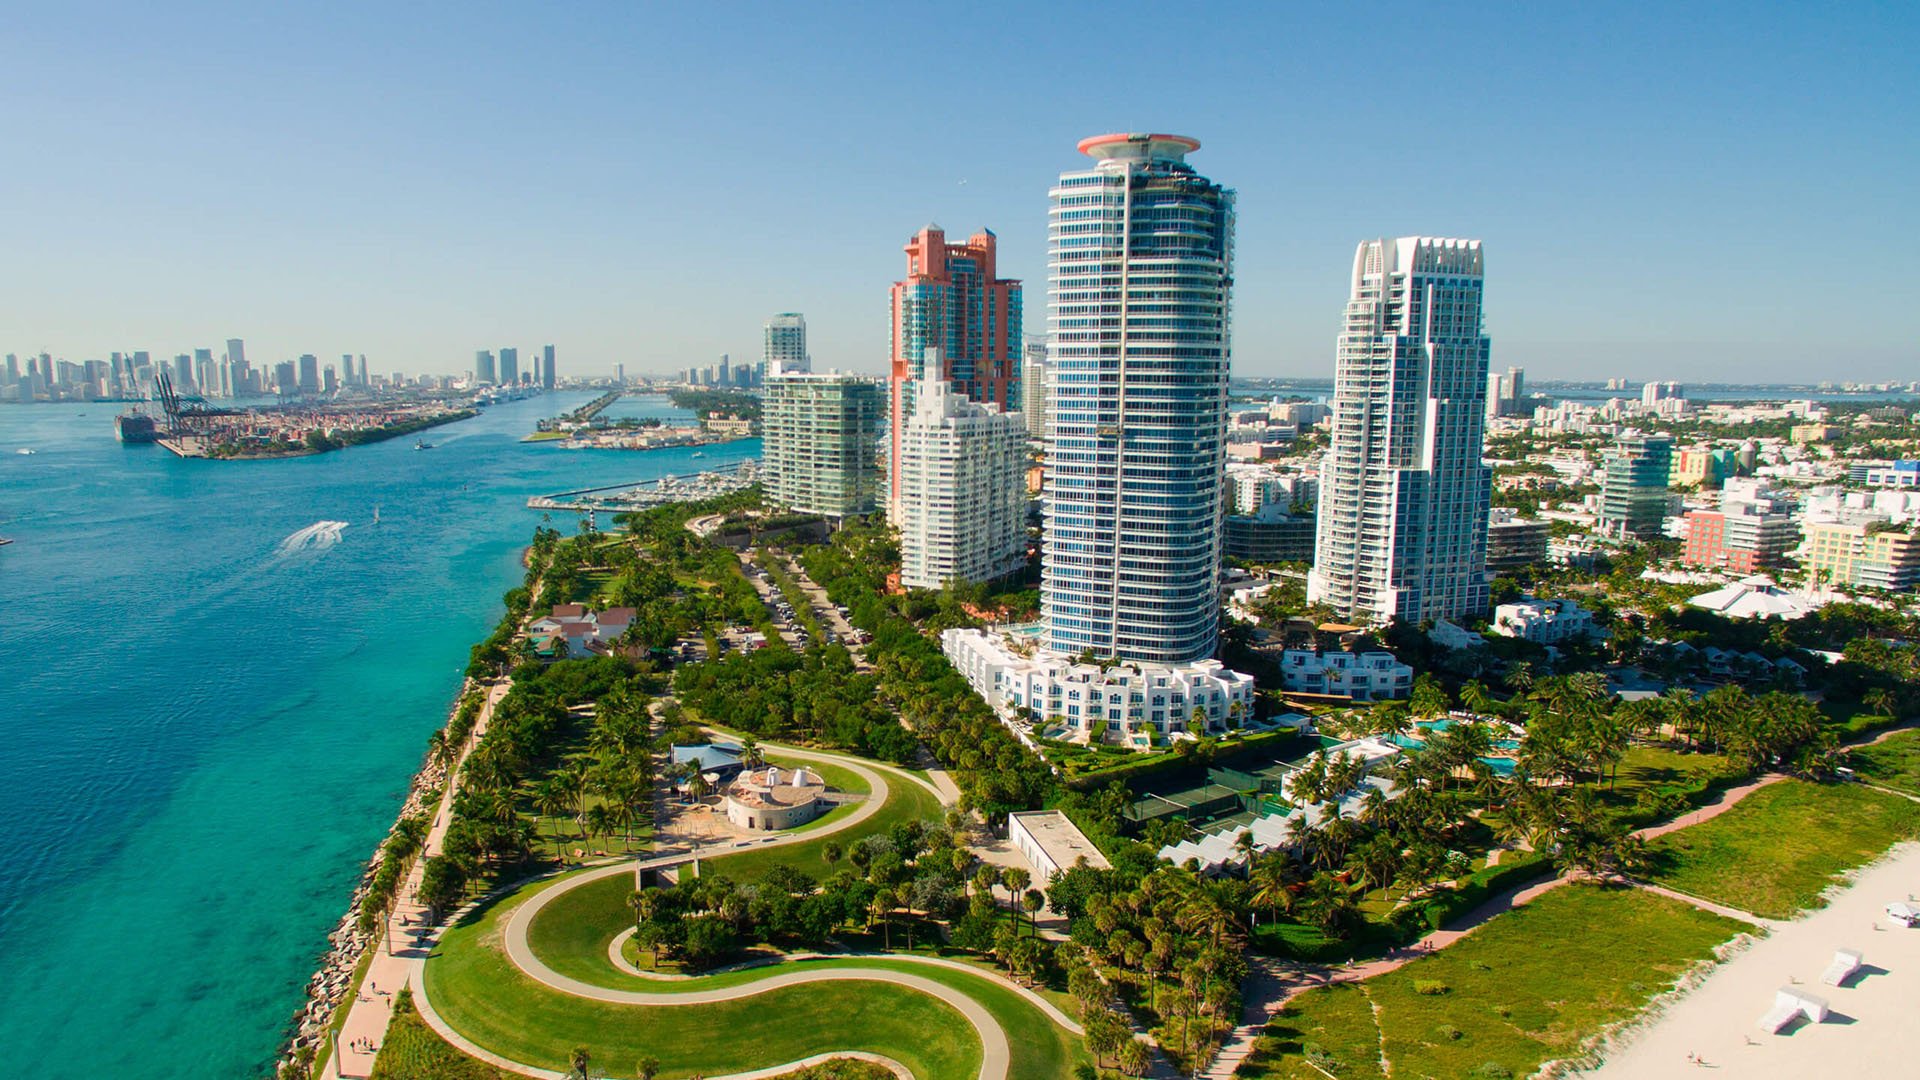
A South Beach purchase can provide the setting for a new life. It does not, by itself, establish that New York residency has ended. For a household evaluating Apogee South Beach, acquisition and relocation deserve parallel attention: one concerns the residence; the other, where the household's permanent life is centered.
Three distinct analyses matter: New York domicile, New York statutory residency, and Florida homestead eligibility. Evidence relevant to one may help explain another, but the tests are not interchangeable. Second-home ownership is not the same as establishing a permanent home.
A useful private-client approach is to maintain one master chronology with separate supporting files. Counsel and tax advisers can then evaluate the same facts without assuming that the deed, the move, and the tax transition share a single date.
Begin with five dates: closing, deed recording, move-in, the claimed domicile change, and the January 1 status relevant to homestead. They need not coincide. The objective is a coherent, documented account of what happened-not a convenient date selected after the year ends.
For a buyer considering Five Park Miami Beach, the same discipline applies: distinguish the purchase milestone from the point at which the property becomes the household's permanent home. Neither a purchase contract nor a closing should substitute for the underlying residency analysis.
As an organizational practice, record each milestone, its supporting documents, and any unresolved questions. Keep explanations of gaps-such as a closing that precedes household relocation-alongside the evidence. Transition-year filings should reflect the actual residency facts and domicile-change date, rather than automatically treating the Florida closing date as the New York exit date.
Domicile is the permanent home a person intends to return to after an absence. New York evaluates the overall facts; no single document settles the question. Moving into a South Beach property does not automatically end New York residency if New York remains the domicile, subject to limited exceptions.
The recommended domicile file should capture the substance of the move:
Florida housing records and evidence of actual household relocation.
Family arrangements that explain where permanent household life is centered.
Business activity relevant to the claimed change of home.
Records showing the movement or location of personal possessions.
Florida driver-license and voter-registration records, where applicable.
These are evidence-management recommendations, not a universal list of legally mandatory documents. Driver-license and voter-registration records can support a move, but they do not independently resolve New York domicile or statutory residency.
The central practical question is not whether the folder looks complete, but whether its contents consistently describe the permanent home being claimed.
A genuine domicile change does not eliminate the need to examine statutory residency. A person can still be a New York statutory resident by maintaining a permanent place of abode there for substantially all of the tax year and spending 184 or more days in the state.
Any part of a day in New York generally counts; an overnight stay at the former home is not required. A diary limited to nights slept in Manhattan therefore does not adequately address the test.
Maintain a contemporaneous calendar supported by travel records, credit-card transactions, toll records, and other independent evidence of location. When statutory residency is examined, taxpayers must substantiate their claim that they spent fewer than 184 days in New York.
Have advisers verify the applicable year's interpretation of “substantially all” rather than relying on an older numerical shortcut. Nor should fewer than 184 days be treated as a complete residency safe harbor: domicile remains a separate question.
Retaining a New York residence deserves its own review. A permanent place of abode can be owned, leased, or otherwise maintained and generally must be suitable for year-round use. Ownership is not the only relevant arrangement.
If the Florida choice is Continuum on South Beach, the New York housing file still needs to explain whether the former residence remains maintained and available. Preserve sale documents, lease-termination records, or other evidence establishing its actual status. “We moved” is not a substitute for that analysis.
An available New York home can remain relevant to statutory residency even after a genuine domicile change. Separately, becoming a nonresident does not necessarily end New York filing obligations: New York-source income may still require a return. Review continuing income exposure alongside the residence and travel records.
For a South Beach property, the homestead application belongs with the Miami-Dade County Property Appraiser, not the City of Miami Beach. Eligibility generally requires a qualifying ownership interest and permanent Florida residence at the property as of January 1 of the tax year claimed.
A purchase late in the prior year can qualify for the following tax year if those January 1 requirements are met. Closing alone does not establish eligibility. For a prospective purchase at Setai Residences Miami Beach, the relevant inquiry is the applicant's ownership and permanent-residency status-not the building's name or the transaction's timing alone.
Trust ownership and other nonstandard arrangements warrant an eligibility review before filing because the applicant's ownership interest matters. Resolve that question before assuming homestead eligibility comes with the purchase.
March 1 is the principal deadline for submitting the homestead application and required documentation. The standard application is Form DR-501, submitted to the property appraiser in the county where the property is located. Verify requirements for the applicable tax year.
The recommended first-cycle file should contain ownership and residency evidence, the completed application, its supporting documents, and submission confirmation. Keep that confirmation readily accessible, not buried in closing correspondence.
Do not assume the seller's homestead exemption becomes the buyer's own. The new owner's eligibility and application require separate evaluation. Save Our Homes uses the first year an owner receives homestead exemption as the base year for future assessed-value limitations. That makes the first cycle important, but it does not justify using the seller's tax position as a forecast for the buyer.
Before transition-year returns and the homestead application are finalized, reconcile the chronology, domicile evidence, New York day count, former-home status, and January 1 eligibility. Explain differences between dates rather than forcing them to match.
This is a planning checklist, not individualized legal or tax advice. The aim is a documented move whose housing decisions, daily life, and filings tell the same story.
For a considered South Beach property search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. A purchase alone does not establish a domicile change, and New York statutory residency must be evaluated separately.
Domicile is the permanent home you intend to return to after an absence. New York evaluates the overall facts rather than treating one document as decisive.
Yes. It can apply if you maintain a permanent place of abode in New York for substantially all of the tax year and spend 184 or more days in the state.
Yes, any part of a day generally counts toward statutory residency. An overnight stay at a New York home is not required.
Recommended supporting evidence includes travel records, credit-card transactions, toll records, and other independent location evidence. Maintain the calendar contemporaneously rather than reconstructing it later.
No. Florida driver-license and voter-registration records can support the move, but they do not independently settle domicile or statutory residency.
Preserve sale, lease-termination, or other records showing whether the residence remains maintained and available. Retaining an available home warrants separate statutory-residency analysis.
Yes. A former resident may still have filing obligations for New York-source income, even after becoming a nonresident.
Apply to the Miami-Dade County Property Appraiser using Form DR-501, with March 1 as the principal submission deadline. Eligibility generally requires qualifying ownership and permanent residence at the property as of January 1 of the claimed tax year.
No; the buyer's eligibility and application must be evaluated separately. Save Our Homes uses the first year the owner receives homestead exemption as the base year for future assessed-value limitations.