A discreet planning checklist for Chicago households making Surfside their permanent home, aligning residence selection with domicile evidence, multistate income, ownership and estate planning.
A move from Chicago to Surfside should begin with a residential question: where does the family genuinely want to live? The answer should reflect daily routines, family relationships, work commitments and long-term plans. Florida's lack of an individual income tax matters, but it cannot make an unsuitable residence feel like home or settle obligations elsewhere.
For a buyer considering Arte Surfside, the initial brief should be personal rather than fiscal. Consider how the residence would function during an ordinary working week, not just a winter visit. Decide what remains in Chicago and what moves with the household.
The governing principle is simple: choose the life, then coordinate the legal and financial structure around it. A sound relocation plan aligns the residence decision with the documentary record, without asking either to disguise the other.
Bring the CPA, estate-planning attorney, real-estate counsel and wealth adviser into the same conversation before ownership decisions become difficult to change. Ask each to define their responsibilities rather than assume another professional has addressed a question.
A practical division of work is:
CPA: assess residency, income sourcing and transition-year filing obligations.
Estate-planning attorney: review Florida-law implications, trusts and family succession objectives.
Real-estate counsel: coordinate title decisions and identify ownership-related homestead questions.
Wealth adviser: help align the financial plan and account records with the relocation.
Designate one coordinator to maintain a shared decision log identifying each open issue, the professional responsible and the evidence needed to resolve it. The aim is not merely to obtain four separate opinions. It is to ensure that the purchase, tax filings and estate plan reflect the same household circumstances.
A person can maintain residences in multiple states but has only one domicile: the permanent legal home to which they intend to return. Purchasing in Florida does not, by itself, establish the physical presence and intention required to make it that home.
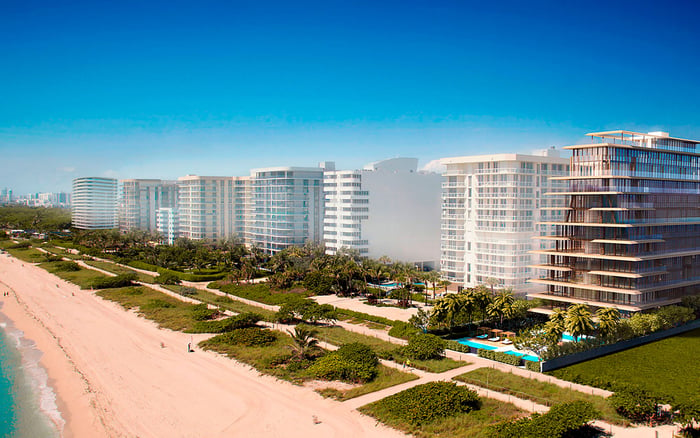
Whether the shortlist includes The Surf Club Four Seasons Surfside or another residence, the purchase decision and the domicile analysis remain distinct. A contract or closing date should not automatically become the relocation date on every document.
The Illinois side also matters. Changing domicile requires establishing a new one elsewhere and abandoning the intention to return to Illinois as the permanent home. Ask counsel to assess continuing homes, family location, business activity and social connections together. The record should explain the household's actual pattern of life, including ties that legitimately remain in Chicago.
Florida's absence of an individual income tax does not eliminate another jurisdiction's taxing rights. Illinois real-estate rents, business income and compensation connected to Illinois work can remain taxable after the household moves.
Before departure, give the CPA an inventory of retained properties, business interests and continuing work arrangements. For services, identify where the work is actually performed. For business interests, ask how the continuing relationship affects sourcing and filing obligations. Do not assume a Florida address settles the analysis.
A useful planning schedule separates three questions: where the household is domiciled, where income arises and which returns may be required. These questions interact, but they are not interchangeable. If the family leaves midyear, ask whether Illinois part-year resident filings are needed and what contemporaneous evidence supports the proposed move date. Reconcile that date before returns are prepared.
Documentation should follow real decisions, not manufacture a relocation after the fact. Maintain travel calendars and day-count records, and share them with the CPA throughout the transition. Do not treat a single day-count threshold as an automatic answer to domicile.
Ask the team to coordinate these records:
A factual timeline of departure, Florida occupancy and continuing Chicago visits.
A Declaration of Domicile, where appropriate, filed with the county clerk in Miami-Dade County, which includes Surfside.
Florida driver's licensing, vehicle registration, voter registration where eligible and tax-address updates.
Consistent addresses and relocation facts across banking records, legal documents and property filings.
The declaration formally records intent; it does not replace physical presence or resolve contradictory facts. Have advisers confirm the applicable requirements and timing for each administrative step. Document genuine differences between dates, such as a purchase that precedes actual occupancy, rather than forcing every event onto one date.
The intended ownership structure deserves joint review before the deed is finalized. Tax, estate and real-estate counsel should assess it against the family's objectives, including property-tax homestead eligibility, creditor-protection considerations and inheritance consequences.
These are separate analyses. Florida's property-tax homestead exemption concerns a permanent residence and can offer a tax benefit while also supporting the domicile record. It does not make property-tax treatment, creditor protection and inheritance rules interchangeable.
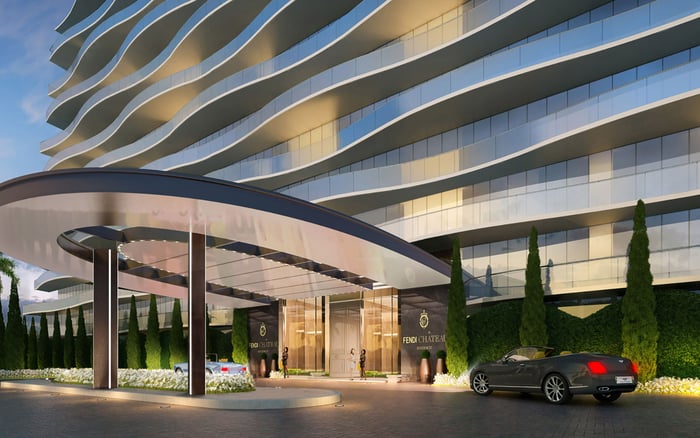
For a purchase at Fendi Château Residences Surfside, the relevant question is not which structure sounds most sophisticated. It is which structure the advisers conclude fits the intended occupancy and estate plan. Before approving closing instructions, ask them to explain the reasoning, any unresolved eligibility questions and the consequences of the proposed title.
Do not assume the Illinois estate plan needs no changes simply because the family has acquired a Florida home. Relocation warrants a Florida-law review of wills, trusts, marital-property rights and homestead interests.
Ask counsel to examine trust situs, governing-law provisions and successor fiduciaries alongside assets that remain in Illinois. The household's new domicile should be considered together with its multistate holdings, not in isolation.
The review should clearly distinguish documents that remain suitable, provisions requiring attention and questions requiring further advice. Coordinate any resulting changes with the ownership decision so that the deed and estate documents do not reflect conflicting intentions.
Closing is a transaction milestone, not the end of domicile planning. Illinois can still question whether a former resident genuinely changed domicile after Florida filings are complete. Continue preserving records and revisit the analysis when work patterns or family arrangements change materially.
As you evaluate Ocean House Surfside, keep one final test in view: would this still be the preferred home if the tax discussion were set aside? That question protects the quality of the residence decision while advisers address its consequences.
Use this checklist as an agenda for individualized legal and tax advice, with current requirements confirmed before action. The objective is a home that suits the family and a record that accurately reflects the move.
Explore residences that fit your next chapter with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Establishing Florida domicile requires physical presence and an intention to make Florida the permanent home; a property purchase alone does not establish both.
A person can have residences in multiple states but only one domicile. Advisers should evaluate the broader pattern of life and the intended permanent home.
The CPA, estate-planning attorney, real-estate counsel and wealth adviser should align tax, ownership and estate-planning decisions around the same factual timeline.
Yes. Illinois real-estate rents, business income and compensation connected to Illinois work can remain taxable after a move.
The CPA should examine where services are performed and how retained business interests affect Illinois income sourcing and filing obligations.
Yes. Have the CPA assess the filing requirement and support the relocation date with contemporaneous records.
No. It creates a formal record of Florida intent but does not replace physical presence or resolve inconsistent facts about the household's actual home.
Maintain travel calendars, day-count records and a factual relocation timeline. Coordinate relevant address updates across tax, banking, legal and property records.
No. Property-tax exemption, creditor protection and inheritance consequences require separate analysis, including how the proposed ownership structure affects each.
A move warrants Florida-law review of wills, trusts, marital-property rights and homestead interests. Trust situs, governing law and successor fiduciaries should also be considered alongside multistate assets.