Before reserving a Palm Beach Gardens residence, read reserves, insurance renewals and capital plans as one financial picture. The essential questions concern building-specific obligations, funding timing, assessment responsibility and the practical effects of planned work.
A Palm Beach Gardens residence can satisfy every aesthetic preference and still warrant a more deliberate financial review. Before committing a deposit, the question is not simply what the association charges today. It is whether reserve contributions, insurance renewals and pending capital projects have been considered together-and whether their timing is clear.
Read those documents as one ownership calendar. A reserve schedule describes anticipated needs; insurance documents identify coverage and renewal questions; a capital plan shows when work may become an actual expense. The objective is to understand both the expected cost of ownership and the unresolved decisions that could change it.
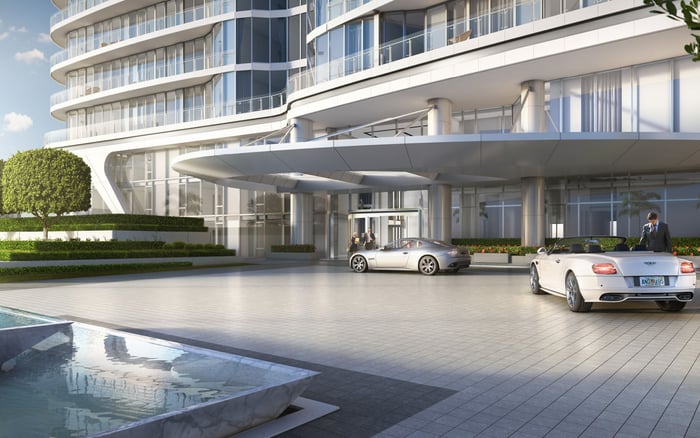
For buyers considering The Ritz-Carlton Residences® Palm Beach Gardens, the same discipline belongs alongside residence selection and contract review. A project name does not establish reserve adequacy or insurance terms. Those answers must come from the documents applicable to the purchase.
Begin with the property's legal structure and the building itself. Florida's milestone-inspection requirement generally applies to residential condominium and cooperative buildings with three habitable stories or more. Do not automatically extend it to every HOA, low-rise residence or community in Palm Beach Gardens.
Qualifying buildings generally require their first milestone inspection by December 31 of the year they reach 30 years old, followed by inspections every 10 years. Local building officials may require an earlier inspection based on local conditions, including proximity to salt water. Confirm the building-specific deadline rather than relying on a general anniversary.
Ask for the certificate-of-occupancy date. It governs the statutory inspection timetable and is more useful than a marketing launch or a broadly stated construction year. Request the milestone-inspection report and establish whether it covers Phase One or includes a required Phase Two inspection. Ask what follow-up remains outstanding.
A milestone inspection evaluates structural condition, including load-bearing elements. A Structural Integrity Reserve Study, or SIRS, addresses future reserve funding for major repairs and replacement of common areas based on a visual inspection. One does not substitute for the other. Associations subject to SIRS generally must complete it at least every 10 years after the condominium's creation, rather than waiting for milestone-inspection age. Confirm current requirements with counsel.
Request the latest SIRS, its completion date, the preparer's identity and the components covered. Ask how its recommendations are reflected in the current budget and contribution schedule. Having a study is not the same as explaining how it is being implemented.
SIRS components include roofs, structural systems, fireproofing and fire-protection systems, plumbing, electrical systems, waterproofing and exterior painting, windows, and exterior doors. Review the relevant components individually rather than treating a single reserve total as the entire answer.
For each component, ask for the available reserve balance, estimated remaining useful life, projected work date and current cost estimate. Compare those figures with final bids, where available. Identify the intended funding sources: existing reserves, future contributions, a special assessment or proposed borrowing. Separate money already held from contributions anticipated later.
Buyers expanding their Palm Beach search to Alba West Palm Beach should carry the same questions into their review. Compare what the applicable documents establish, not what shared luxury positioning might suggest about future costs.
Ask for the association's master policy, renewal date and available renewal quote. Establish whether the budget reflects the current premium, a quoted renewal or an assumption awaiting confirmation. These represent different levels of certainty and should remain distinct in your analysis.
Review deductibles and exclusions with your insurance adviser. Ask about open claims, any nonrenewal notices and insurer-required improvements. These are questions to investigate, not conclusions about a particular association's coverage or condition.
Then connect insurance to the capital schedule. Does the association identify any planned work as necessary for renewal? If so, what is the required completion date, what documentation is needed, and has funding been approved? Ask whether the timing of an insurance decision could alter the planned construction sequence or budget.
For a second-home purchase, this review should also inform discussions with your own insurance adviser about unit-level protection. Do not assume the association's master policy answers every coverage question relevant to the residence.
Request the last 12 months of board minutes and the current special-assessment schedule. Read them alongside the budget and reserve study. Minutes can help distinguish an idea under discussion from work that has moved toward approval, contracting or funding.
Ask what work is planned over the next 12-36 months. For each project, establish whether the scope is settled, whether contracts and permits are finalized, and whether the stated cost is an estimate or a final bid. Ask about proposed borrowing and any funding decision still awaiting action.
Keep approved assessments separate from proposed charges or those still under discussion. Record each expense's status, expected timing and supporting documents. An unresolved project should remain visible even when no assessment amount has been finalized.
Financial clarity is only half the inquiry. Ask whether construction could affect unit access, parking, balconies, amenities or occupancy. Request the anticipated sequence and duration of interruptions, recognizing that an unfinished plan cannot provide the same certainty as finalized arrangements.
For a resale purchase, focus on the association's existing records: inspection findings, reserve implementation, insurance terms, assessments and project decisions. Ask your closing attorney to reconcile the contract with those records rather than relying on verbal assurances about who will pay.
For pre-construction, first establish which documents exist and which decisions remain prospective. Ask counsel to explain the reservation agreement, deposit terms, applicable disclosures and financial assumptions presented for future ownership. Do not treat an estimated budget as an established renewal history or operating record.
When comparing Gardens options with Mr. C Residences West Palm Beach, keep each purchase's document status explicit. The point is not to presume that one has stronger finances, but to avoid treating confirmed obligations and projections as equivalent.
Have the closing attorney clarify responsibility for assessments already approved, assessments approved during the transaction and disclosed projects whose assessments are not yet finalized. Ask how the contract addresses each situation and whether any unresolved item warrants further review before committing a deposit.
The final decision should rest on a coherent picture: applicable inspections, component-level reserves, insurance renewal assumptions, project status and contractual responsibility. Luxury ownership is more comfortable when these obligations are understood before the residence becomes yours.
For a discreet perspective on Palm Beach Gardens residences and the wider luxury market, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe requirement generally applies to residential condominium and cooperative buildings with three habitable stories or more. Confirm applicability to the specific building rather than assuming every condominium or HOA qualifies.
It is generally due by December 31 of the year the building reaches 30 years old, with inspections every 10 years thereafter. Local officials may require an earlier inspection based on local conditions.
Use the building's certificate-of-occupancy date, not its marketing launch or a general construction date. Confirm the building-specific deadline.
No. A milestone inspection evaluates structural condition, while a SIRS addresses reserve funding for future major repairs and replacement of common areas.
Generally, at least every 10 years after the condominium's creation. The requirement does not simply begin when a building reaches milestone-inspection age.
Compare balances with remaining useful lives, project dates, current estimates and final bids where available. Ask whether funding depends on future contributions, assessments or proposed borrowing.
Request the master policy, renewal date and available renewal quote. Ask about deductibles, exclusions, open claims, nonrenewal notices and insurer-required improvements.
Request the last 12 months of board minutes, along with the current special-assessment schedule. Distinguish approved charges from proposed or still-discussed expenses.
Ask about work planned over the next 12–36 months, funding, finalized contracts and permits. Establish whether construction could affect access, parking, balconies, amenities or occupancy.
Have the closing attorney clarify the contract's treatment of existing assessments and those approved during the transaction. Also address disclosed projects whose assessments have not yet been finalized.