A precise purchase-planning framework for Kempinski Residences Miami Design District, separating developer deposits from special assessments and explaining how negotiated resale credits and escrow holdbacks can allocate obligations at closing.
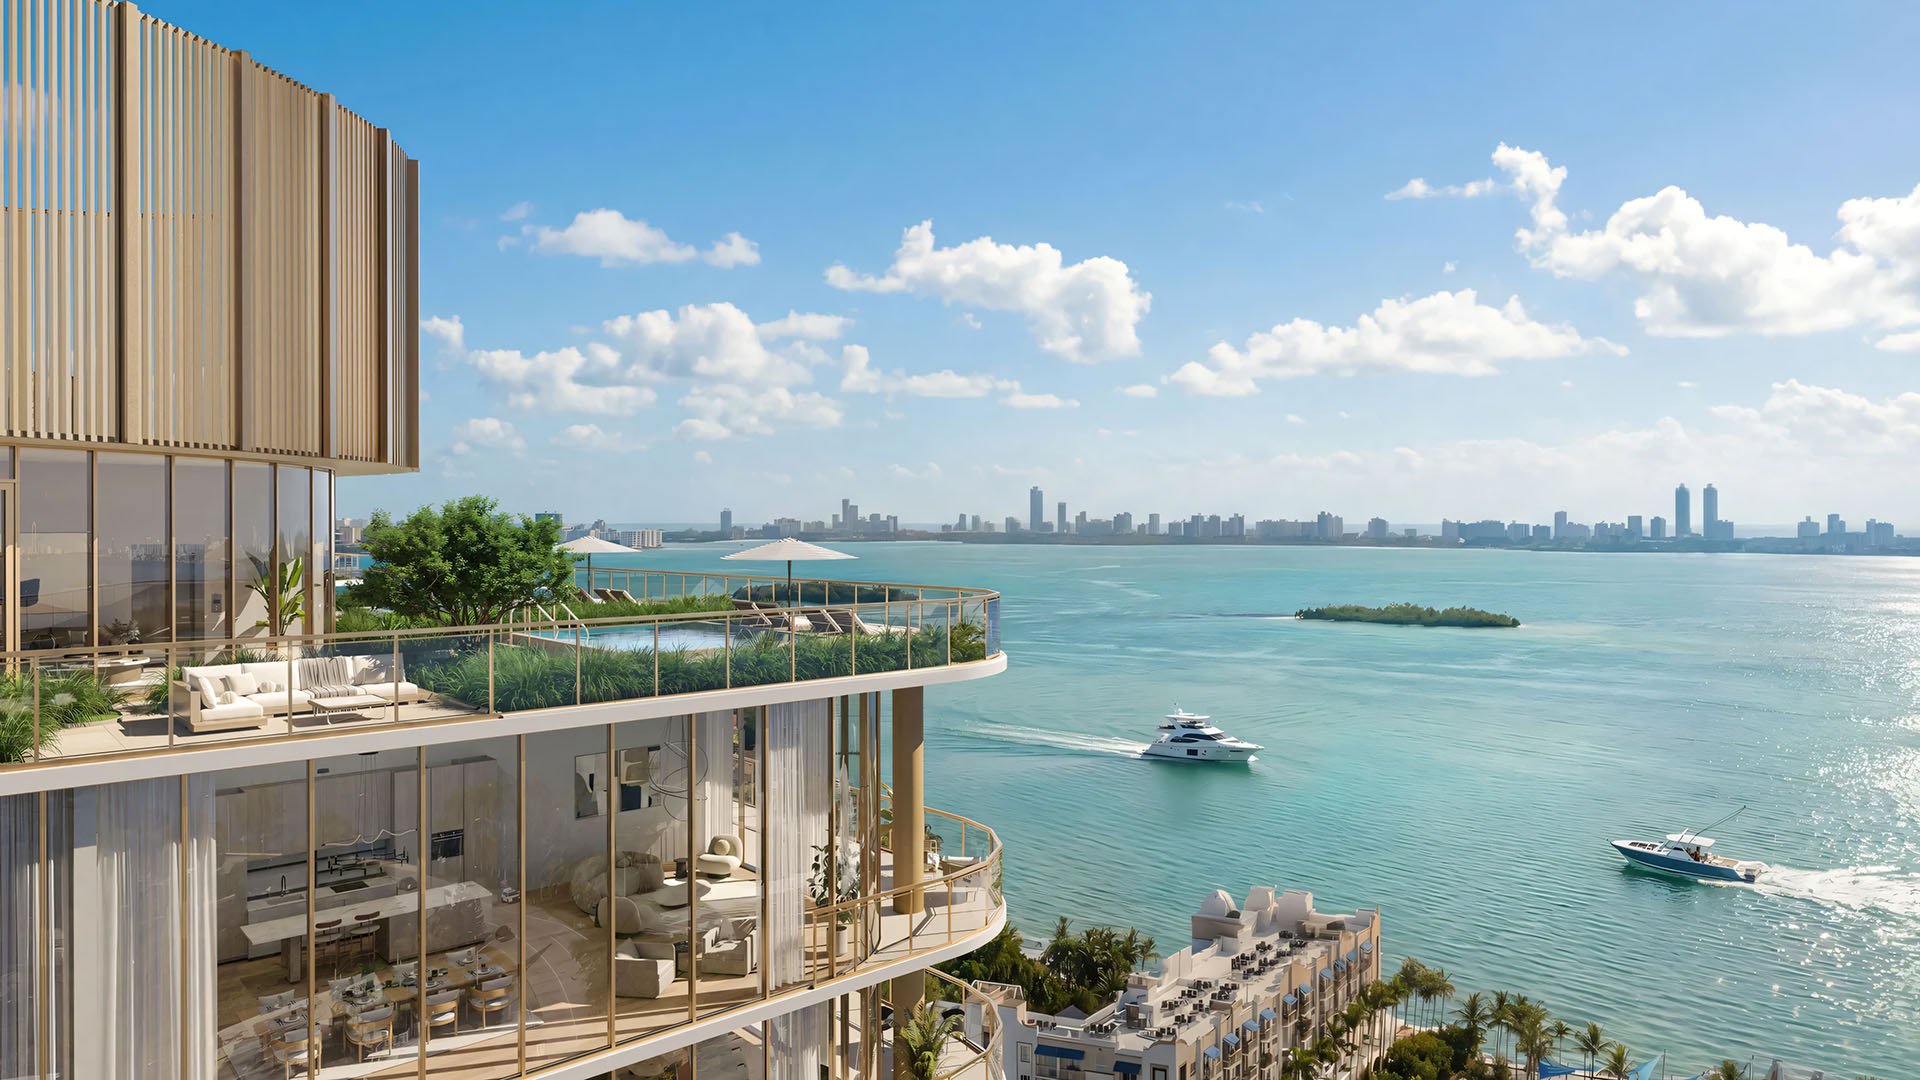
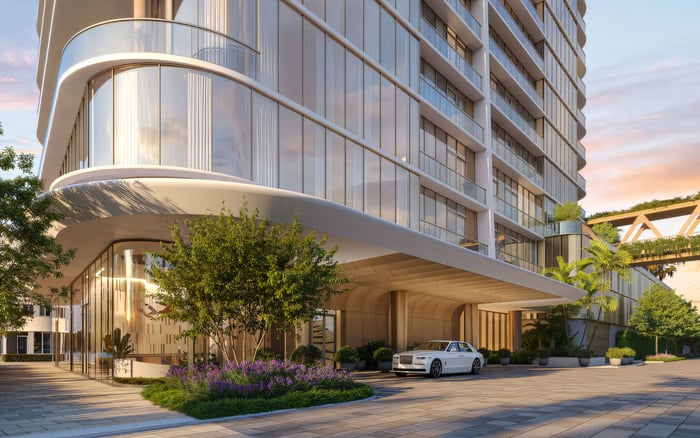
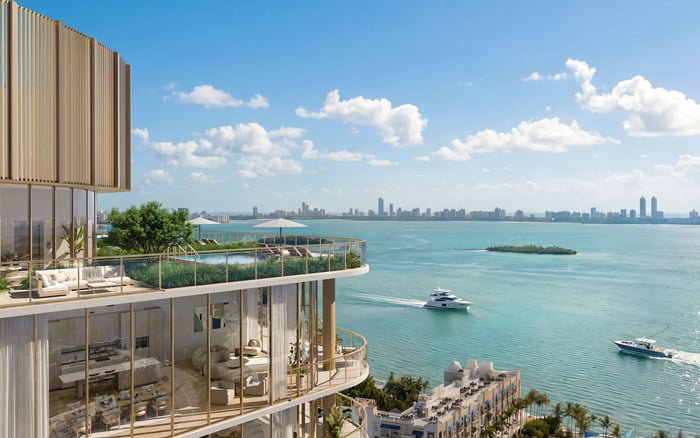
At Kempinski Residences Miami Design District, purchase planning begins with an essential distinction: a developer deposit schedule is not a condominium special-assessment schedule. The planned two-tower development at 3801 and 3883 Biscayne Boulevard, near the Design District and Biscayne Bay, has published purchase milestones. Those milestones govern payments toward an acquisition, not future association charges.
For buyers considering Branded Residences, precision belongs alongside design and location. The central questions are when capital must be available, how purchaser deposits are treated, and which obligations remain after title transfers. Seller credits and seller-proceeds holdbacks belong to a separate, negotiated transaction framework, particularly in resales. Buyers should not assume they are features of this developer offering.
The published purchase schedule begins with a $50,000 reservation deposit. The contract-stage payment is 20%, with an indicated 60-90-day contract milestone. A further 10% is due at groundbreaking, targeted for Q2 2027, followed by another 10% at top-off, targeted for Q2 2028. The remaining 60% is due at closing, targeted for Q4 2029.
Treat construction dates as targets, not guarantees. For liquidity planning, distinguish each payment trigger from its anticipated date. Counsel should also confirm how the reservation deposit is applied under the signed purchase agreement, rather than assuming it is an additional charge or automatically credited in a particular manner.
Buyers also considering Miami Tropic Residences should compare each purchase agreement on its own terms. A useful comparison goes beyond the percentage payable before closing to examine the trigger, timing and treatment of each payment. No project's deposit structure should be carried over to another by assumption.
No fixed future special-assessment schedule is established for Kempinski. The published purchase milestones cannot serve as a forecast of association assessments. Nor should buyers treat them as evidence of a final operating budget or a known unit-level assessment amount.
If an assessment becomes relevant to a transaction, build a separate schedule around the actual obligation. Identify the assessment, when it was levied, the applicable amount, and each installment's payment date. Distinguish amounts levied before contract, amounts levied between contract and closing, and installments payable after closing. Reconcile those categories with the contract's allocation language rather than collapsing them into a single closing adjustment.
This distinction matters because Florida's assessment-liability rules can make a new owner jointly and severally liable with the previous owner for assessments due before title transfers. An agreement between buyer and seller is not confirmation that the association's claim has been satisfied.
In a resale involving an outstanding assessment balance, the parties may negotiate seller payment at closing, a closing credit, or buyer responsibility for specified future installments with a price adjustment. The appropriate structure depends on the obligation being allocated and the terms the parties accept-not on a presumed project-wide practice.
Seller payment at closing addresses the identified obligation through the closing process. A negotiated credit adjusts the buyer's closing economics while leaving the buyer responsible for the covered payment obligation. Buyer responsibility for future installments requires equally clear language identifying which installments transfer and how the agreed price reflects that responsibility.
These are transaction-planning alternatives, not verified Kempinski incentives or standard contract provisions. For a developer purchase, buyers should first determine whether a proposed concession or allocation appears in their agreement. A resale negotiation should not be imported into a developer contract on the assumption that the same mechanisms apply.
A seller credit is most useful when its scope is explicit. The agreement should identify the assessment, the covered amount or calculation method, the installments included, and any obligations that remain with the buyer. If financing is involved, confirm lender restrictions before relying on the credit in the closing figures.
A reference to an assessment balance is insufficient if the parties disagree about what it includes. Does the credit cover installments payable after closing, amounts already due, or a defined combination? The negotiated language should answer that question and match the closing calculations.
A credit changes the economics immediately; it does not retain a reserve of seller proceeds for later resolution. Buyers should distinguish compensation for assuming an obligation from evidence that the obligation has been paid. The closing documents should reflect the result the parties negotiated.
Florida Statute 718.202 addresses escrow requirements for certain developer condominium sales before construction, furnishing and landscaping are substantially completed. In the circumstances it specifies, it addresses the escrow treatment of purchaser payments up to 10% of the sale price. It is not a general resale seller-proceeds holdback rule, nor a blanket statement about every payment in a developer schedule.
A negotiated holdback serves a different purpose: it retains seller proceeds until a defined obligation is resolved. The recommended drafting should specify the escrow agent, funded amount, release evidence, deadline and dispute procedure. Avoid vague language such as “money held for assessments.”
A release condition should identify what demonstrates resolution and what happens if the parties disagree. Counsel should clarify those mechanics before closing, rather than leaving the escrow agent to interpret an open-ended arrangement afterward. These drafting recommendations are not mandatory Kempinski terms or an established project holdback policy.
Before committing capital, obtain independent professional advice and review the developer's prospectus and condominium documents. For an applicable resale, request current condominium documents and unit-specific estoppel information, then reconcile assessment obligations with the contract and closing figures. Keep deposit obligations, assessment allocations and escrow instructions distinct throughout the review.
The same discipline applies when evaluating Villa Miami alongside a Kempinski purchase: compare documented obligations, not assumed similarities between residences. A clear acquisition file should show what is payable now, what is payable at a future milestone, and what requires separate agreement.
The objective is straightforward: preserve clarity about capital commitments and responsibility after closing. A thoughtfully negotiated price is only part of that result; the payment calendar and allocation language deserve equal attention.
For a discreet perspective on South Florida residential opportunities, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe planned two-tower condominium development is at 3801 and 3883 Biscayne Boulevard, near the Miami Design District and Biscayne Bay.
The published schedule begins with a $50,000 reservation deposit. Buyers should confirm its application in the signed purchase agreement.
The published schedule specifies 20% at contract, 10% at groundbreaking, 10% at top-off and the remaining 60% at closing.
Groundbreaking is targeted for Q2 2027, top-off for Q2 2028 and closing for Q4 2029. These dates are targets rather than guaranteed appointments.
No. They describe purchase deposits, and no fixed future Kempinski special-assessment schedule is established.
A Kempinski-specific seller-credit program is not established. Credits discussed here are negotiated transaction-planning alternatives, particularly for resales.
A seller credit adjusts closing economics immediately. A holdback retains seller proceeds until a defined obligation is resolved.
It should identify the assessment, covered amount or calculation method, covered installments and remaining buyer obligations. Any applicable lender restrictions should also be checked.
It should specify the escrow agent, funded amount, release evidence, deadline and dispute procedure. These are drafting recommendations, not established Kempinski policies.
It should not be treated as a general resale holdback rule. It addresses purchaser-payment escrow for certain developer condominium sales in the circumstances it specifies.