A buyer-focused framework for reviewing La Baia North assessment records, distinguishing levy dates from installment deadlines, and discussing transaction-specific seller credits and escrow protections with counsel.
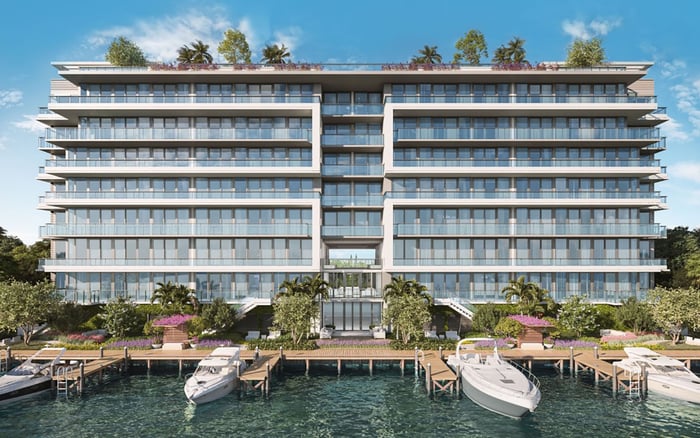
A considered purchase at La Baia North Bay Harbor Islands begins with a precise distinction: the residence on offer and the financial obligations being acquired are separate subjects. Floor plans and brochures can inform the first conversation, but they do not establish a particular unit's assessment exposure.
Assume neither that a special assessment exists nor that none exists. Establish any current assessment amount, installment calendar, unit allocation or reserve-funding obligation through transaction-specific documents. Likewise, seller credits and escrow holdbacks should not be treated as standing La Baia North benefits or published concession programs.
For buyers also considering Bal Harbour, this discipline deserves a place alongside architecture and location in the acquisition decision. The objective is clarity: what is owed, when it became an obligation and who will bear it after closing.
Request a written assessment schedule tied to the specific residence, rather than accepting a balance without context. Counsel and the closing team should distinguish an approved obligation from a proposal and reconcile each amount with its supporting record.
A useful request would identify:
The assessment's purpose and the association action approving it.
The levy date, total amount and allocation to the residence.
Installment amounts, due dates, payments made and remaining balance.
Any pending assessment discussions reflected in agendas or minutes.
The proposed contractual allocation between buyer and seller.
These are diligence requests, not assertions that La Baia North has an assessment. If none is disclosed, ask the transaction team which records support that position and whether anything under discussion warrants further review.
Review recent board agendas and minutes alongside formal notices for assessment proposals or discussions. Ask counsel to confirm the applicable disclosure requirements and review period under the actual executed agreement.
The central question is not simply whether an installment falls due before or after closing. It is when the assessment was levied and how the executed agreement assigns responsibility.
Ask counsel to determine what constitutes a levy under the applicable law, condominium documents and executed agreement. Then confirm how the agreement allocates assessments levied before, on or after closing, including any installments payable later and any written amendments between the parties.
Do not assume a particular rider governs every La Baia North transaction. Ask counsel to identify the operative language before translating an installment schedule into a buyer's cash-flow forecast. A later payment deadline is not, by itself, proof of buyer responsibility.
Do not carry a resale rider's allocation into a developer purchase without checking the agreement. The distinction between developer-sale and resale terms matters more than a familiar label on a closing worksheet.
Ask counsel which documents govern assessment responsibility, what disclosures have been made and whether any negotiated amendment changes the allocation. Keep the answer specific to the residence and contract under consideration.
If Bay Harbor Towers is also on the shortlist, apply the same document-by-document comparison there. This does not suggest that the projects share financial obligations or contract provisions. The point is to compare documented commitments rather than assume a common neighborhood practice.
A seller credit is a proposed transaction term, not evidence that an assessment has been paid or eliminated. No La Baia North credit policy should be presumed.
Before negotiating an amount, ask counsel to connect the proposed credit to a clearly identified obligation. Does it address a disclosed, levied assessment, future installments of that assessment or an unresolved proposal? Those situations should not be folded into one unexplained concession.
Ask the transaction team whether the proposed credit matches the obligation the buyer is agreeing to bear, how it would appear in the closing documents and whether the contract needs a corresponding written amendment. If financing is involved, ask the lender and closing agent whether the proposed treatment is acceptable.
The objective is alignment: the economic concession, contractual responsibility and settlement treatment should be consistent. Do not rely on an informal assurance that a credit will cover everything while the underlying amount or allocation remains uncertain.
An escrow holdback warrants a different discussion from an immediate credit. Rather than assuming a standard formula, ask counsel whether retaining agreed funds under written release conditions is appropriate for the particular unresolved obligation.
The drafting discussion should address the obligation being secured, the proposed amount, who would hold the funds, what evidence would permit payment and how any remainder would be released. Ask what happens if the obligation exceeds the retained amount, remains unresolved or becomes disputed. These are negotiation questions, not a verified La Baia North holdback program.
Do not assume the seller, developer or proposed escrow holder will accept the arrangement. Ask the closing team to confirm feasibility before relying on it. A holdback proposal should clarify uncertainty, not substitute for understanding the assessment or the contract.
The broader review should include the declaration, bylaws, articles, rules, current annual budget, reserve information and recent association meeting records. Request the latest reserve study, if available, and examine its date, covered components, estimated costs and recommended funding rather than relying exclusively on the monthly association charge.
Review the association estoppel certificate for amounts currently due, unpaid assessments and other unit-related financial obligations. Read it alongside the disclosure record and negotiated contract terms, not as a replacement for them.
If an assessment concerns repairs, request applicable engineering or milestone-inspection materials, bids, permits, schedules, insurance information and associated borrowing. This conditional review does not imply repair deficiencies at La Baia North.
For a buyer comparing Onda Bay Harbor, the same standard offers a useful basis for comparison: documented obligations, clearly allocated responsibility and understood funding needs. Before closing, ask counsel to reconcile any differences among the assessment schedule, estoppel and settlement documents. The strongest purchase decision pairs the residence's appeal with financial clarity.
For a discreet perspective on your next South Florida residence, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationRequest the assessment's purpose, approval record, levy date, unit allocation, installment deadlines and remaining balance. Reconcile those details with the proposed contractual allocation between buyer and seller.
No. A current assessment amount, payment schedule and unit allocation should be established through transaction-specific association and closing documents.
No. Marketing materials do not establish a residence's assessment obligations; review the association records and governing transaction documents.
The levy date can be relevant to how the executed agreement allocates responsibility between seller and buyer. An installment's payment deadline alone does not determine who bears the obligation.
Ask counsel to confirm responsibility under the executed agreement and applicable law. Do not assume a later installment deadline transfers the obligation to the buyer.
Review them for assessment proposals or discussions alongside formal notices. Ask counsel to confirm the applicable review period and disclosure requirements.
A standing credit policy should not be presumed. Treat a proposed credit as a transaction-specific negotiation tied to an identified obligation and written terms.
Ask counsel about the secured obligation, amount, escrow holder, release evidence and treatment of shortfalls or disputes. Confirm that the relevant parties would accept the structure.
Review it for amounts currently due, unpaid assessments and other unit-related financial obligations. Reconcile it with disclosures and the executed contract.
Request the latest reserve study, if available, and review its date, covered components, estimated costs and recommended funding. The monthly association charge alone is not a substitute for that review.