A buyer-focused framework for reviewing flood-claim records, verifying lower-level equipment protection, and planning household and business continuity at Aria Reserve Miami.
Preparing a high-value residence at Aria Reserve Miami requires more than protecting interiors. For an owner balancing family life, valuable possessions, and professional commitments, the central question is operational: what must remain available for the residence to function, and what is the alternative if it cannot?
Three inquiries deserve separate attention: flood-claim history, the exposure of equipment serving the building, and continuity arrangements for the household or business. Aria Reserve’s prior flood claims, if any, have not been verified in this review; a claim-free history has not been established either. The location, elevation, flood protection, and redundancy of its electrical and mechanical equipment are also unverified here. These are matters for documentary diligence, not grounds for assuming a deficiency.
The objective is to replace uncertainty with a clear ownership plan. A refined interior and a well-prepared household are complementary priorities.
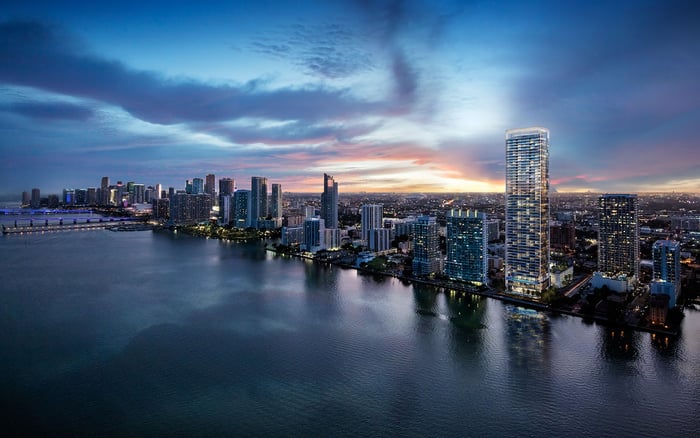
For an Edgewater purchase, ask an adviser to review the property’s current flood designation, evacuation planning zone, ground elevation, and access routes together. Include both storm surge and heavy rainfall in the review rather than treating waterfront exposure as a single question.
Review storm-surge planning zones and federal flood zones separately. Ask the adviser to explain what each designation means for the address, which map versions apply, and what the maps cannot establish about the building’s garage or equipment.
For a longer ownership horizon, request a property-specific discussion of changing flood exposure and resilience planning. Do not treat a regional planning scenario as a prediction of water depth at a particular residence.
Begin with a written request for available association loss runs, relevant insurance documents, and records of flood-related incidents or repairs. Ask for each record’s coverage period, the insured entity, and whether it concerns common property, the individual residence, or both. Have the seller address the residence separately.
If an incident appears, ask for its cause, affected areas, repair scope, claim status, and evidence of completed corrective work. Distinguish a submitted claim from a paid claim, and both from a maintenance issue that never became an insurance matter. These are proposed checks, not statements about Aria Reserve’s history.
Board minutes and maintenance records may help frame follow-up questions. Ask whether any water-related work remains open, whether further investigation was recommended, and how any associated costs would be handled. An incomplete response should remain an unresolved diligence item-not become either reassurance or an allegation.
Buyers also considering EDITION Edgewater should apply the same documentary standard. Compare the scope and period of the evidence supplied, rather than relying on an unsupported impression that one address has a cleaner history.
The useful question is not simply whether a garage could take on water. Ask which essential systems, if any, occupy lower levels, what protects them, and which services would be interrupted if those systems became unavailable. A residence’s floor height alone does not answer those questions.
Request an equipment schedule and drawings identifying electrical distribution, elevator controls, domestic-water equipment, communications infrastructure, and any drainage pumps or backup-power components. Have a qualified inspector or engineer interpret elevations against the relevant flood benchmarks and explain the limits of any protection described.
For pumps or flood barriers, where present, request testing records, maintenance responsibilities, deployment procedures, and the power arrangements required for operation. For any generator, seek specifications, the loads it serves, testing documentation, fuel arrangements, and operating limitations. Do not treat the word “backup” as a promise of uninterrupted service throughout the residence.
Ask management to explain dependencies as well as individual components. Which services could operate independently, which require several systems to function, and what inspections would precede restoration? The review should clarify practical service availability without implying that any particular equipment configuration exists at Aria Reserve.
Ask an insurance adviser to review association and owner policies together. Request written clarification of applicable coverage, exclusions, limits, deductibles, and responsibility for interiors, possessions, temporary accommodation, and business-related losses. Do not presume that one policy addresses every consequence of a flood or access restriction.
For valuable collections, propose a separate inventory and preservation plan, with photographs and supporting documents stored securely off-site. Confirm any specialist handling arrangements before they are needed. Coordinate insurance questions and physical-protection decisions, but do not mistake one for the other.
The same discipline applies when evaluating Villa Miami alongside another residence. Assess policy terms and documented building arrangements individually; a shared neighborhood does not establish equivalent coverage, exposure, or recovery capability.
Start with life safety and evacuation instructions. Review routes and establish who can authorize departure, coordinate transport, and account for household members, staff, and pets. Once evacuation is required, do not make departure contingent on completing property-protection tasks.
Identify an alternate residence and, where appropriate, a temporary operating site for professional work. Check that the proposed destination suits the household’s needs, and evaluate its own flood and evacuation exposure. These are owner planning recommendations, not verified services offered by Aria Reserve.
Prepare backup communications, secure remote access to essential business files, and an off-site copy of insurance and ownership documents. Assign responsibility for contacting management, insurers, advisers, and service providers. For an owner frequently away from Miami, define the local representative’s authority and the conditions under which that person may safely act.
Finally, establish a return protocol. Ask how management would communicate access restrictions, service restoration, and any inspections needed before occupancy. A continuity plan should address the period after the storm as carefully as the departure itself.
Before committing, organize the findings into a short decision file: verified facts, unanswered questions, required professional reviews, and owner actions. Ask legal and technical advisers which unresolved matters should be addressed before closing. Distinguish any expected restoration timetable from a contractual commitment.
The desired result is not a promise of zero disruption. It is a residence whose documented arrangements you understand, paired with a household plan that does not depend on assumptions.
For a considered approach to South Florida ownership, explore residential opportunities with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo prior flood claims have been verified in this review, and a claim-free history has not been established either. Request association and residence-specific documentation before drawing conclusions.
Request available association loss runs, relevant insurance documents, and records of flood-related incidents or repairs. Clarify the dates, insured entity, and property covered by each document.
Review them separately with an adviser. Ask what each designation means for the address and what it cannot establish about building-level exposure.
Keep the missing information on an unresolved diligence list and request clarification. Do not treat an incomplete response as proof of either a clean history or a problem.
Its equipment locations, elevations, flood protection, and redundancy have not been verified in this review. Ask a qualified professional to review equipment schedules, drawings, and relevant flood benchmarks.
Request generator specifications, supported loads, testing documentation, fuel arrangements, and operating limitations, where applicable. Do not assume backup power supports every service in the residence.
Ask how management would communicate access restrictions, service restoration, and any inspections needed before occupancy. Include those procedures in the household’s return plan.
Ask an insurance adviser to assess the policies together and clarify coverage, exclusions, limits, deductibles, and responsibilities. Do not assume temporary accommodation or business-related losses are covered.
Include evacuation arrangements, alternate accommodation, a temporary work location where appropriate, backup communications, and secure access to essential documents. Assign clear responsibilities for departure and recovery.
They have not been verified as building services in this review. They are owner planning recommendations; confirm any management-provided arrangements directly.