For a Luxembourg household considering Pompano Beach, the property choice, funding plan and appraisal protections deserve separate decisions. A disciplined purchase pairs residence-specific valuation with carefully negotiated contract rights and individualized cross-border advice.
A move from Luxembourg to Pompano Beach offers an appealing change of perspective: a residence chosen around the Atlantic rather than an established European routine. Yet the property decision demands more than a preference for a view or address. It should separate three questions: which home to acquire, how to fund the purchase and what contractual protection to retain if the valuation disappoints.
These questions are related, but not interchangeable. An all-cash purchase generally has no mortgage-lender appraisal requirement. That does not make an independent appraisal unnecessary or prevent a buyer from negotiating appraisal protection. Equally, financing approval does not necessarily establish a separate right to cancel over value.
The starting principle is simple: funding capacity and valuation confidence are different things. A considered purchase should address both before an offer becomes a commitment.
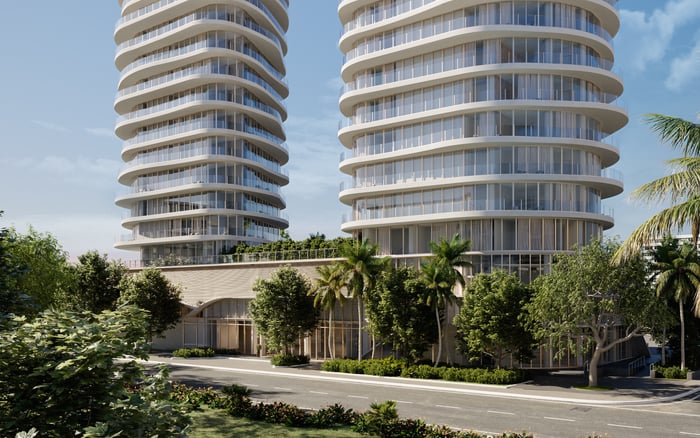
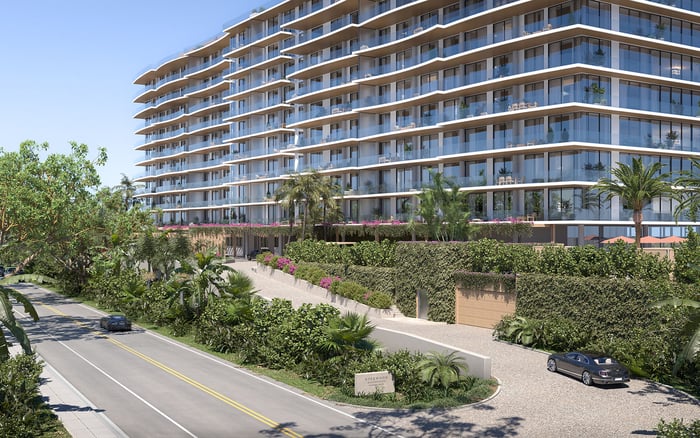
Begin with the property you want to own, then test the acquisition structure against it. For a household comparing Armani Casa Residences Pompano Beach with other residences, the assessment should focus on the specific home rather than a broad impression of the local luxury market.
Ask the property adviser to distinguish personal preference from the evidence supporting price. A residence can be the right lifestyle choice without every dollar of its asking price being justified by comparable transactions. Conversely, an appraisal need not capture a home's full personal significance.
Before negotiating, establish two boundaries: the amount you are comfortable committing and the valuation difference you would knowingly accept. These are buyer decisions, not judgments to delegate entirely to a lender or seller. Making them explicit helps prevent enthusiasm for the residence from quietly dictating the financing strategy.
A cash purchase removes the usual mortgage-lender appraisal requirement, but leaves an important choice with the buyer. You can commission an independent appraisal for information, negotiate a contractual appraisal contingency or consider proceeding without that protection. Each choice carries different consequences.
An appraisal commissioned solely for your own understanding does not, by itself, create a cancellation right. The purchase contract must provide that right. Cash buyers can negotiate appraisal protection rather than automatically accept the valuation risk of an unconditional offer, but that protection must become part of the agreed contract.
When evaluating Ocean 580 Pompano Beach, for example, keep funding and valuation as separate agenda items. First decide how you intend to meet the purchase obligation. Then decide what evidence of value you want and what contractual consequence should follow if that evidence falls below the negotiated threshold.
Waiving an appraisal contingency means relinquishing that particular protection against proceeding above appraised value. It should be a conscious decision, not shorthand for being a serious buyer.
If you are considering securities-backed credit, review it separately before relying on it in an offer. Ask the proposed lender and your financial advisers to confirm whether a facility is available for your circumstances, whether its permitted use fits the purchase and what its written terms would require of you.
The review should address cost, collateral obligations, access to funds, timing and a fallback funding plan. Resolve these questions for the actual arrangement; do not assume the answers from the phrase “cash purchase.” A proposed credit facility is no substitute for deciding whether the property price is acceptable.
For a Luxembourg household, obtain individualized advice on the relocation's tax, banking and residency questions separately from the Florida contract review. The purchase structure should follow those answers. Securities-backed funding combined with an appraisal rider should not be treated as universally preferable to another arrangement.
Financing protection and appraisal protection serve different purposes. Have Florida counsel explain how the proposed financing contingency addresses any lender-required valuation and whether a separate appraisal contingency is appropriate for your purchase.
If considering FR/BAR Addendum F, ask counsel to confirm its applicability, the valuation threshold, the appraisal deadline and the requirements for exercising any cancellation right. Do not assume every agreement contains the same protection or that a rider applies unless incorporated into the executed contract.
A standalone appraisal rider can provide a contractual cancellation right even when financing has already been approved, subject to the executed agreement's terms. Review the purchase agreement and any proposed rider together rather than treating financing approval as the end of the valuation discussion.
If the appraisal is low, possible responses include committing additional buyer cash, seeking a price renegotiation or cancelling where the contract permits. Renegotiation is a request, not an automatic entitlement to a lower price. Nor should a low valuation alone be treated as an automatic release from the purchase.
Pompano Beach pricing requires careful distinctions. Separate oceanfront condominium asking prices from completed condominium sales, and avoid using high-end single-family transactions as substitutes for condominium comparables. These measures describe different properties or stages of a transaction, not a ready-made discount formula.
For buyers considering branded residences such as The Ritz-Carlton Residences® Pompano Beach, ask for the reasoning behind the proposed comparables and distinguish asking prices from completed sales. A broad market median cannot settle the value of the individual home you intend to buy.
Before signing, bring the property adviser, Florida counsel and financial advisers together to review the proposed transaction. The goal is a coherent decision: a residence you want, a funding plan you have reviewed and appraisal rights you understand.
Document your response to a disappointing valuation in advance. Would you proceed at the agreed price, seek a reduction or exercise a negotiated cancellation right? For an international move, that clarity is more valuable than treating cash as an instruction to dispense with safeguards.
For a discreet conversation about your Pompano Beach property search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationAn all-cash purchase generally has no mortgage-lender appraisal requirement. The buyer can still choose an independent appraisal and negotiate contractual appraisal protection.
Yes, cash buyers can seek appraisal protection. It must be agreed and incorporated into the executed purchase contract.
No, an appraisal alone does not create that right. Cancellation depends on the executed contract and compliance with its terms.
Financing protection addresses financing conditions, while a separate appraisal rider can provide rights tied to a negotiated valuation threshold. Have Florida counsel explain how each provision operates in the proposed agreement.
Ask Florida counsel to confirm its applicability, valuation threshold, appraisal deadline and cancellation requirements. Review the rider together with the purchase agreement.
Yes, a standalone appraisal rider can provide a contractual cancellation right even when financing has been approved. Its threshold, deadlines and other terms still govern.
Potential responses include additional buyer cash, price renegotiation or cancellation where the contract permits. Neither a price reduction nor cancellation follows automatically.
Ask the proposed lender and financial advisers to confirm suitability, permitted use, costs, collateral obligations and funding timing for the actual arrangement. Review a fallback funding plan before committing.
No, a broad market median cannot settle an individual residence's value. Oceanfront condominium asking prices, completed condominium sales and high-end single-family transactions are not interchangeable comparables.
Seek individualized tax, banking and residency advice alongside a Florida review of the purchase contract. Coordinate those conclusions with the property decision and proposed funding plan.