A move from Austin to South Flagler Drive calls for more than a purchase budget. Align the residence, payment timetable, and ongoing ownership costs with the investment portfolio and liquid capital you want to preserve.
The appeal of moving from Austin to South Flagler Drive is easy to picture: an Intracoastal address, considered architecture, and a residence shaped around a different daily rhythm. The more consequential question is what the purchase leaves intact. A home should support the next chapter without making every subsequent investment or household decision dependent on its value.
For an ultra-luxury condominium purchase in West Palm Beach, separate three decisions: how much capital to allocate to the property, how to meet each contractual payment, and what liquid reserves to retain after possession. These decisions are connected, but not interchangeable. A substantial balance sheet does not necessarily mean funds are available when a deposit falls due.
The objective is not simply to afford the residence. It is to preserve financial flexibility after acquiring it.
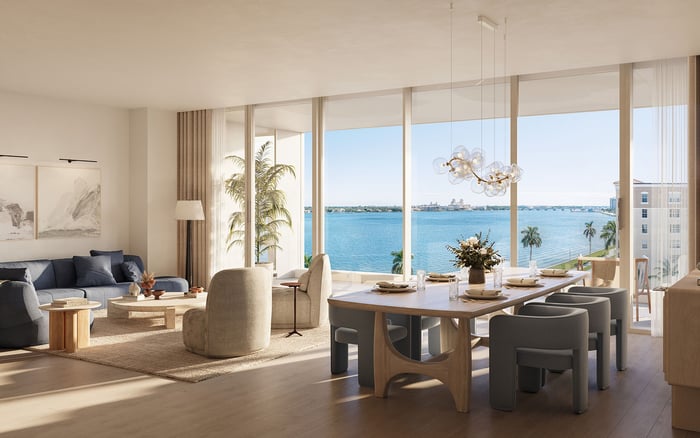
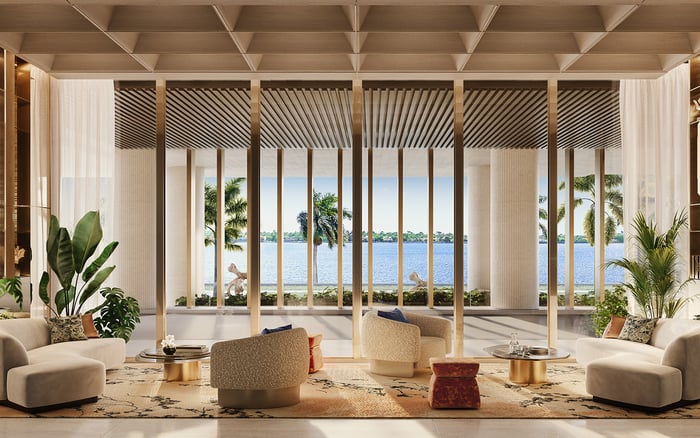
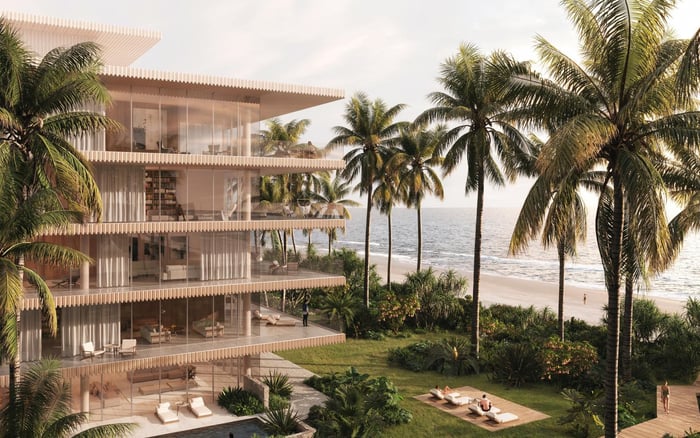
At 1355 South Flagler Drive, South Flagler House West Palm Beach pairs development by Related Ross with architecture by Robert A.M. Stern Architects. Its two 28-story towers encompass 105 residences and more than 50,000 square feet of amenities. Construction topped out in November 2025; 2027 remains a targeted completion year, not a guaranteed occupancy date.
That distinction matters if an Austin sale, temporary lease, or household move must follow a specific timetable. Plan the transition around the purchase agreement rather than treating a completion target as a confirmed moving date.
Nearby, Forté on Flagler West Palm Beach occupies 1309 South Flagler Drive, with direct Intracoastal frontage. Developed by Two Roads Development and Alpha Blue Ventures, the 25-story condominium contains 41 residences, typically two flow-through homes per floor. Its stated 2025 delivery presents a different timing proposition. Even so, confirm the availability, condition, and closing timetable of the specific residence before coordinating the move.
Begin with a before-and-after balance sheet. Include the proposed purchase, transaction expenses, furnishing commitments, existing housing obligations, and any intended borrowing. Then identify the investable assets remaining after all acquisition spending-not merely after the initial deposit.
There is no need to impose an arbitrary concentration ceiling. Instead, ask whether the remaining portfolio can support household spending, existing commitments, and future investment opportunities under less favorable conditions. Test a delayed Austin sale and a decline in assets earmarked for the purchase. Neither scenario is a prediction; each reveals where the plan depends on an outcome you cannot control.
Assign a funding source to every payment. Distinguish available cash from anticipated sale proceeds, assets requiring liquidation, and financing awaiting approval. Review liquidation choices and their tax consequences with your advisers before signing.
If an Austin property sale is intended to replenish reserves, show those reserves separately until the sale closes. Expected proceeds are not accessible capital.
A South Flagler House deposit schedule allocates 20% at signing, 10% at groundbreaking or deep soil mixing, 10% when construction reaches the buyer’s floor, and 60% at closing.
Applied solely as an illustration to a hypothetical $12 million purchase, that produces:
$2.4 Million at signing.
$1.2 Million at the initial construction milestone.
$1.2 Million at the buyer’s-floor milestone.
$7.2 Million at closing, before transaction costs and other charges.
This is not a current payment offer or a substitute for a contract. The schedule includes construction milestones already achieved. A buyer signing now should obtain the actual deposit requirements, due dates, and closing provisions in writing, rather than assume those original stages remain available.
Extend the calendar beyond the purchase price. Add estimated transaction costs, furnishing payments, moving expenses, and any period of overlapping Austin and Florida housing. For each item, record the due date, funding source, and whether the amount is confirmed or provisional.
Distinguish project funding from personal financing. South Flagler House secured $600 million in developer construction financing, but that does not establish buyer mortgage availability or guarantee delivery. If borrowing is part of the plan, obtain residence-specific terms and clarify approval conditions and timing with the lender.
Post-purchase reserves deserve their own budget, separate from closing funds. The question is not how impressive the remaining asset total looks, but which obligations it can meet without an unplanned liquidation.
South Flagler House association fees range from $5,728 to $30,728 monthly. Annualized, that is $68,736 to $368,736 in association charges alone, excluding separately payable taxes, insurance, and other ownership expenses. These figures are not a quote for a particular residence; obtain its current budget and fee schedule.
Build the household reserve assessment from that unit-specific information. Review what association charges include, then add separately payable property taxes, insurance, interior maintenance, household spending, and debt service, if applicable. Keep furnishing and move-in costs visible so they do not consume the operating reserve unnoticed.
Distinguish your personal reserve from the condominium association’s reserves. Ask counsel to review the association budget, reserve information, and any disclosed assessments. A personal cash buffer and a building’s financial position answer different questions.
Size the reserve with your advisers based on spending, income reliability, and access to funds-not a universal number of months.
Conclude the comparison with a common worksheet for each finalist: total acquisition spending, payment timing, expected occupancy, recurring costs, and liquid capital remaining. A larger residence or a different amenity offering may justify a greater allocation, but the trade-off should be explicit.
If your search broadens to Mr. C Residences West Palm Beach, apply the same questions rather than carrying over another building’s deposit schedule, operating budget, or delivery assumptions. This is a focused condominium decision, not an exhaustive comparison of every housing option along South Flagler Drive.
Before committing, have the purchase agreement, lender requirements, relocation calendar, and household balance sheet reviewed together. Ask what changes if occupancy shifts, Austin proceeds arrive later, or furnishing spending rises. Decide how to fund those changes before they become urgent.
The most satisfying move is one in which the residence feels right and the capital plan remains comfortable after the keys arrive.
For a discreet conversation about aligning your South Flagler Drive search with your relocation and capital priorities, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationCompare total acquisition spending, contractual payment timing, ongoing ownership costs, and investable assets remaining afterward. Include any overlapping Austin housing expenses.
Its targeted completion year is 2027. Treat that as a planning assumption rather than a guaranteed occupancy date.
Forté’s stated delivery was in 2025, unlike South Flagler House’s 2027 completion target. Confirm the specific residence’s availability and closing timetable before scheduling a move.
The representative schedule is 20% at signing, 10% at groundbreaking or deep soil mixing, 10% at the buyer’s-floor milestone, and 60% at closing. Actual obligations must come from the buyer’s contract.
The illustrative payments would be $2.4 million, $1.2 million, $1.2 million, and $7.2 million. These figures exclude closing costs and other charges.
No. Construction milestones in the published schedule have already been achieved, so a new buyer should obtain current deposit requirements in writing.
Published monthly fees range from $5,728 to $30,728, equivalent to $68,736 to $368,736 annually. Confirm the residence-specific amount and separately payable expenses.
Build a tailored reserve around unit-specific charges, taxes, insurance, maintenance, household spending, and any debt service. Its size should reflect income reliability and access to funds rather than a universal target.
No. South Flagler House’s $600 million construction financing does not establish individual mortgage availability or guarantee project delivery.
Identify them as anticipated rather than available funds until the sale closes. Test how a delay would affect deposits, closing liquidity, and post-purchase reserves.