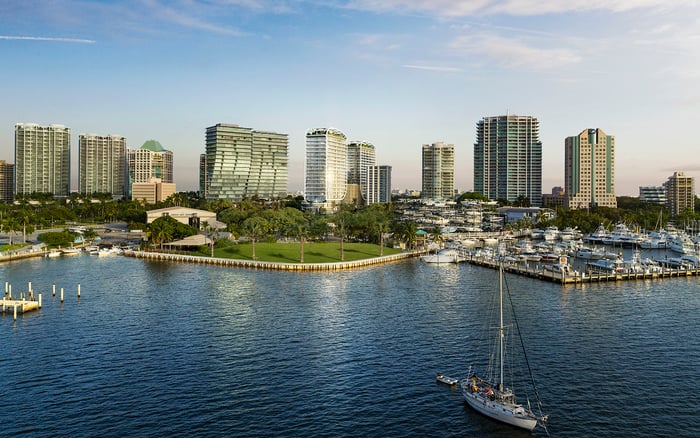
Keeping a London address while establishing life in Miami calls for two distinct residence analyses. Understand how accommodation availability, overnight stays and US day counts shape the plan before treating either home as a tax solution.
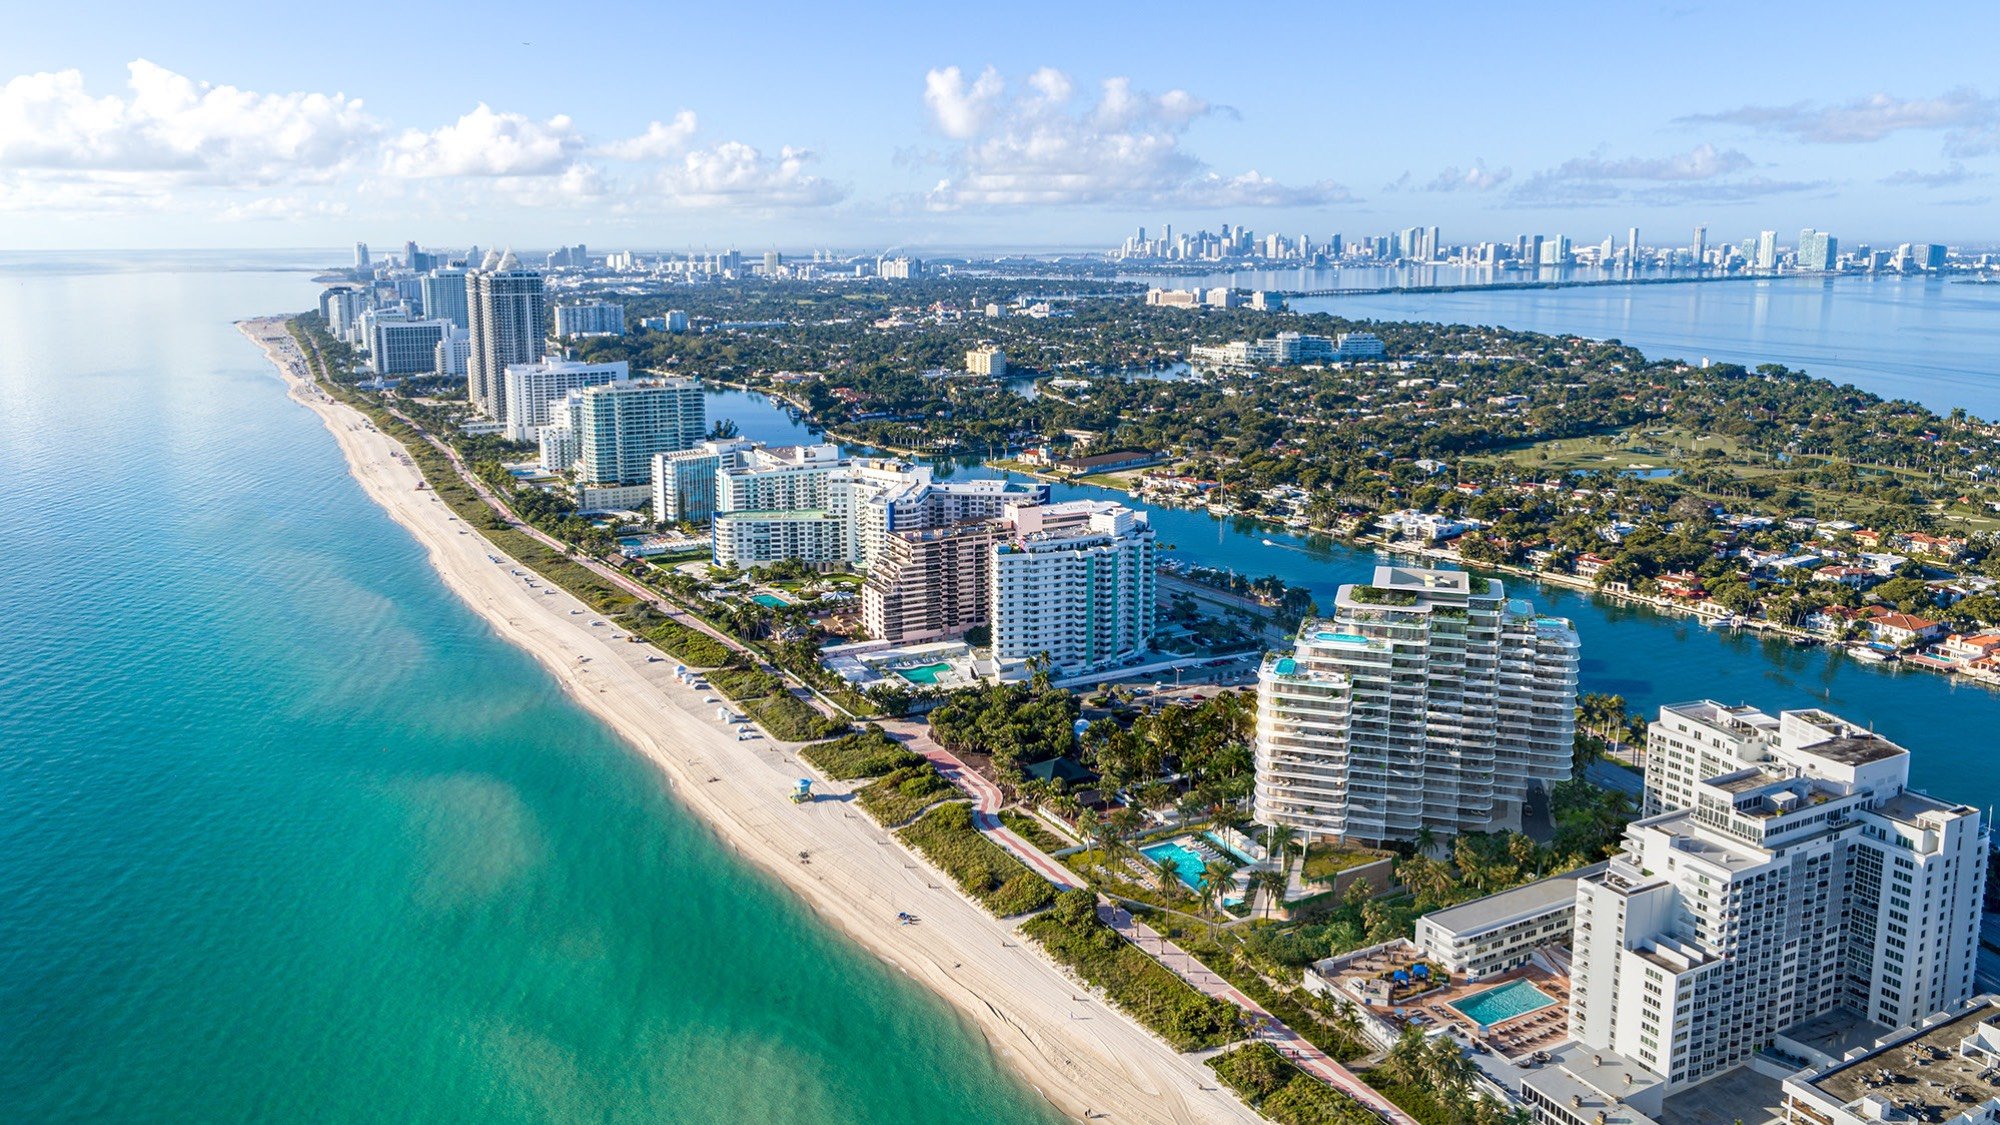
A move to Miami need not mean relinquishing London. For a household considering The Residences at 1428 Brickell, retaining a familiar London base may be part of the appeal: continuity alongside a new daily rhythm. The planning question is not simply whether to keep the property, but what access will remain and how that access fits into two separate residence analyses.
UK accommodation rules examine availability and use. US residence rules examine presence and, where relevant, the conditions for a closer-connection exception. A retained London home can matter to both, but it answers neither question on its own.
Start with a written description of each property's intended role. Is London a personal retreat, a let investment, a vacant residence or accommodation occupied by family? Is Miami an occasional destination or the centre of everyday life? Those distinctions deserve attention before the move, not merely at filing time.
A London property can create a UK accommodation tie when it is available for at least 91 continuous days during the tax year and you spend at least one night there. Special rules apply to accommodation at a close relative's home, so that situation requires separate review rather than automatic application of the one-night threshold.
Ownership is not the deciding factor. The test concerns whether accommodation is available to live in and whether it is used. A holiday home, temporary retreat or other available place to stay can qualify. Nor must a property meet the definition of a home under other UK residence rules to count for this purpose.
Continuity also requires care. Gaps in availability of fewer than 16 days can count toward the continuous 91-day period. Do not assume that a short interruption resets the calculation.
An accommodation tie is one component of the UK Statutory Residence Test-not, on its own, a finding of UK tax residence. The question is how that tie enters the wider analysis, rather than whether one London overnight automatically determines the outcome.
Keeping ownership and keeping personal access are different decisions. If the London property is let, the analysis must establish whether you retain any ability to use it. Ownership alone does not establish continued availability; equally, describing a property as rented does not resolve the question if personal use remains possible.
Review the arrangement as it will operate, not just as it is labelled. Document intended personal stays, tenancy arrangements, family occupation and any periods when access is restricted. Retain evidence of actual access and overnight stays so the record reflects what happened.
For a buyer comparing Miami Beach options such as The Perigon Miami Beach, this decision runs alongside the purchase itself. Selecting the next residence does not settle the status of the previous one. Review the London access plan alongside the Miami occupancy plan, treating neither as an administrative afterthought.
The US substantial presence test generally requires at least 31 days of presence in the current calendar year and 183 weighted days across that year and the two preceding years. It is not simply a count of nights spent in Miami this year.
The calculation includes all current-year days, one-third of the preceding year's days and one-sixth of the second preceding year's days. US presence generally includes any day when you are physically present for any part of the day, although specified exclusions apply.
Consider 130 countable US days in the current year and 120 in each of the preceding two years. The weighted total is 190: 130 plus 40 plus 20. That meets the numerical thresholds even though current-year presence is below 183 days, assuming no applicable exclusions.
Track UK and US presence separately. The UK accommodation analysis and the US weighted calculation ask different questions; one annual travel total cannot reliably answer both. Include previous US visits in the planning exercise before fixing the relocation calendar.
Someone who meets the substantial presence test may qualify for the closer-connection exception only if current-year US presence is fewer than 183 days and the other eligibility conditions are met. Falling below that number is a condition, not a universal safe harbour.
The exception generally requires maintaining a tax home in a foreign country throughout the current year and demonstrating a closer connection to that country than to the United States. Keeping a London home alone does not establish that connection. Relevant factors include permanent homes, family, belongings, business activities and social affiliations.
Here, the substance of a Miami move matters. If work, family and everyday life shift to Coconut Grove, a retained London address may not support the conclusion a household expects. When considering Four Seasons Residences Coconut Grove, distinguish the appeal of the residence from the tax implications of the life you intend to build around it.
A pending application for lawful permanent residence, or specified steps toward that status, can make the exception unavailable. Claiming it generally also requires timely filing of Form 8840. Immigration intentions and filing obligations therefore belong in the same review as travel and property access.
Before relying on a proposed arrangement, assemble three connected records: the intended use of the London property, separate UK and US travel histories, and the planned location of family, work and everyday activity. Ask advisers to examine those facts together while keeping the legal tests distinct.
The financial stakes extend beyond either residence. US resident aliens are generally subject to US income tax on worldwide income, making the residence determination relevant to income and investments outside the United States as well as to the move itself.
The objective is not to make a London home perform a tax function it cannot guarantee. It is to decide deliberately how both homes will be used, preserve evidence of that use and coordinate UK residence, US residence and immigration advice before assuming nonresident treatment. This is a planning framework, not an individual tax determination.
Explore your next South Florida residence with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. The accommodation test concerns availability and use, not ownership alone.
It can create a tie when available for at least 91 continuous days during the tax year and used for at least one night. Special rules apply to a close relative's home.
Not necessarily. Gaps of fewer than 16 days can count toward the continuous availability period.
The arrangement must be examined to establish whether you retain any ability to use the property. Neither ownership nor the rental label alone settles availability.
No. It is one component of the UK Statutory Residence Test, not a standalone residence determination.
The calculation counts all current-year days, one-third of the preceding year's days and one-sixth of the second preceding year's days. The test generally requires at least 31 current-year days and 183 weighted days.
No. Weighted presence from the preceding two years can bring you within the substantial presence test even below 183 current-year days.
No. The exception generally requires a foreign tax home throughout the current year and a closer foreign connection, considering factors such as family, belongings, business and social affiliations.
Yes. A pending application for lawful permanent residence or specified steps toward that status can make the exception unavailable.
Claiming the exception generally requires timely filing of Form 8840. Filing does not replace the need to satisfy the eligibility conditions.