For an art collector purchasing a South Florida residence with portfolio-backed credit, title protection and liquidity management belong in separate files. A disciplined review clarifies whose interest is insured, what endorsements actually change, and how to preserve a potential claim.
For an art collector, a South Florida residence may be both a private retreat and a setting for a carefully assembled collection. Funding the purchase through a securities-backed line of credit, or SBLOC, introduces a separate financial relationship. The property, the pledged portfolio, and the artwork should not be treated as one insured asset.
Real-estate title insurance addresses covered defects in property ownership. It does not protect artwork ownership, authenticity, provenance, or valuation, nor does it absorb the liquidity risks of portfolio-backed borrowing.
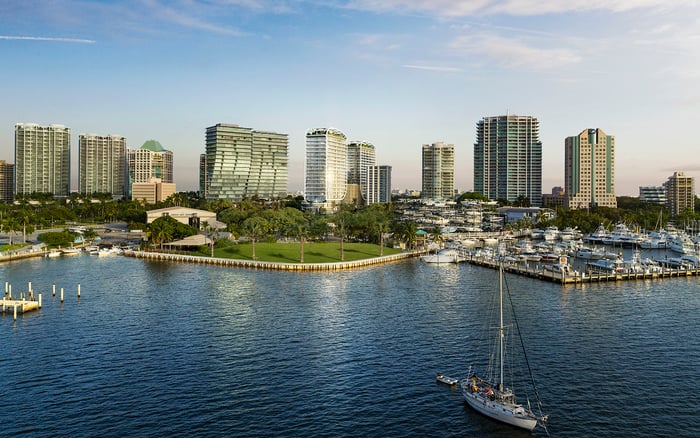
For a buyer considering The Residences at 1428 Brickell in Brickell, the starting point is documentary: identify what secures the borrowing, whose interest each policy insures, and which risks remain outside the title contract. The residence’s appeal and the financing arrangement deserve distinct reviews.
An owner’s title policy protects against covered losses arising from defective or invalid real-estate title, liens, and other legal claims against the property’s title. It is generally issued for the property’s full insurable value, typically its purchase price, and does not expire merely with the passage of time. The policy’s terms still govern coverage.
A lender’s policy serves a different insured: the mortgage lender. It does not replace the buyer’s owner’s policy. Lender coverage generally remains effective until the insured loan is paid in full, with protection governed by the loan amount and policy provisions.
Using an SBLOC does not automatically create a mortgage on the purchased residence or require a real-estate lender’s policy. Have counsel identify the actual collateral arrangement before deciding which policies are relevant.
Review the owner’s stated coverage amount separately from the financing balance. Do not assume title coverage equals the residence’s current market value or automatically rises with appreciation. The stated amount and the policy’s provisions control.
An SBLOC is generally a demand loan, allowing the lender to require repayment at any time under the agreement. A decline in pledged securities can trigger a maintenance call requiring additional collateral or repayment, often within two or three days.
If the borrower cannot satisfy that call, the lender may sell some or all of the pledged securities. Forced sales can produce unintended tax consequences, while market volatility can intensify the risks of borrowing against a portfolio.
For a collector evaluating The Perigon Miami Beach in Miami Beach, the distinction is clear: a sound title file is not a liquidity reserve. Consider having lending and tax advisers review the demand provisions, collateral requirements, and potential consequences of forced sales before funding.
Keep a written contingency plan identifying available repayment resources and the people authorized to act. This is a financial planning recommendation, not a benefit supplied by title insurance.
The policy’s exclusions and its Schedule B exceptions require separate attention. Standard owner’s-policy exclusions include specified defects, liens, or other matters created, suffered, assumed, or agreed to by the insured. Certain matters known to the insured but not disclosed to the insurer in writing may also be excluded, subject to the contract’s precise knowledge and disclosure provisions.
Governmental laws and regulations are generally excluded except where the policy expressly covers specified risks. Title insurance is not a general assurance against every legal, financial, or physical issue affecting the residence.
Schedule B identifies matters excepted from coverage unless the issued policy or an endorsement removes, modifies, or affirmatively covers them. Ask counsel to explain the practical effect of each exception, not merely confirm that the schedule exists.
A useful review sheet records each matter, the requested resolution, and the final policy treatment. Retain written disclosures to the insurer alongside that sheet. Unanswered questions should remain visible in the file, not disappear into closing correspondence.
An endorsement changes standard coverage. Depending on its wording, it may amend an exclusion or condition, or cover a matter otherwise excepted. It is not a general promise that every concern discussed before closing has been insured.
For a purchase at Park Grove Coconut Grove in Coconut Grove, apply the same discipline as for any other residence: record each requested endorsement’s name and form number, then verify issuance, final wording, applicable conditions, and Florida availability. These are transaction-specific checks, not representations about coverage at the project.
Policy amendments and endorsements must be documented in writing and authenticated, or expressly incorporated through Schedule A as the policy permits. Do not treat an informal assurance as the final coverage document.
Availability varies by jurisdiction. If a transaction includes a real-estate-secured loan with future advances, ask counsel about appropriate future-advance-priority coverage. Do not assume that such coverage applies to a securities-only credit line or that every nationally described endorsement is available in Florida.
Organize the archive into three distinct folders. The property folder should retain the title commitment, issued policy, endorsements, recorded instruments, and transaction documents. The credit folder should retain the securities-backed lending agreement and related collateral documents. Keep artwork records separate so they cannot be mistaken for evidence of real-estate coverage.
Preserve funding instructions, wire confirmations, and any entity authorizations, with a clear index linking them to the transaction. Consider designating one person to confirm that the archive contains the final issued documents, not just preliminary versions.
For an owner whose advisers manage different parts of the acquisition, this organization makes the controlling document easier to locate without confusing a funding question with a title question.
If a title problem emerges, consult the issued policy promptly. Follow its written-notice instructions, including delivery to the specified notice address, and preserve evidence of delivery. Do not assume that notifying a closing participant satisfies the insurer’s notice requirements.
Create a chronology of discovery and notice. Preserve the policy and endorsements, commitment, recorded instruments, transaction documents, claim or lawsuit, and evidence of loss. Comply with the policy’s cooperation requirements, which can affect claim handling and coverage.
Before making settlement commitments, check whether insurer consent is required. Settling without required consent can affect recovery. Depending on the policy, the insurer may defend title, cure a covered defect, settle, or pay a covered loss rather than automatically pay the policy limit.
The objective is a coordinated review: title counsel addresses coverage, while lending and tax advisers address portfolio exposure. Actual protection depends on the issued contract, not the prestige of the address.
Explore South Florida residences with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationIt protects against covered losses from defective or invalid real-estate title, liens, and other legal claims against the property’s title. The issued policy and endorsements determine the protection.
No. A lender’s policy protects the mortgage lender and does not replace the buyer’s owner’s policy.
No. Using securities-backed credit does not automatically create a mortgage on the purchased property or require a real-estate lender’s policy.
An owner’s policy does not expire merely with the passage of time. Continued protection remains subject to its terms.
No. The stated coverage amount and policy provisions control, so buyers should not assume coverage automatically tracks appreciation.
A maintenance call may require additional collateral or repayment within two or three days. If it is not satisfied, the lender may sell pledged securities, potentially creating tax consequences.
Schedule B identifies matters excepted from coverage unless the issued policy or an endorsement removes, modifies, or affirmatively covers them.
No. Its effect depends on its final wording and conditions, and availability varies by jurisdiction; verify that the requested endorsement was actually issued or properly incorporated.
Follow the policy’s prompt written-notice instructions, preserve supporting documents, and comply with cooperation requirements. Check consent requirements before making settlement commitments.
The coverage discussed here does not establish protection for artwork ownership, authenticity, provenance, or valuation. Keep artwork records separate from the property’s title file.