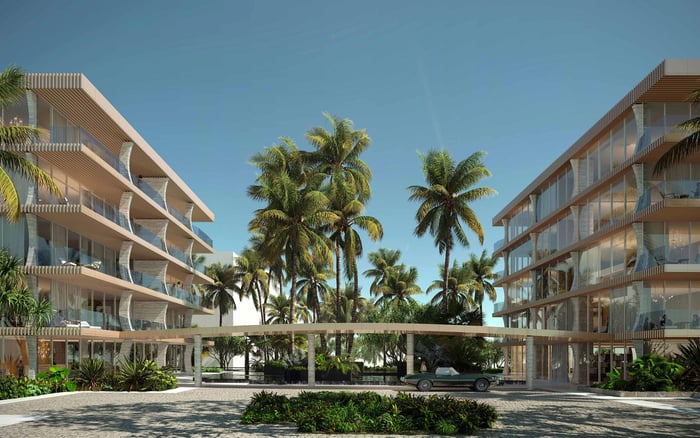
An Austin-to-Palm Beach Gardens move calls for coordinated domicile planning, buyer-specific property-tax estimates and a residence decision grounded in everyday life, not an assumed income-tax advantage.
Leaving Austin for Palm Beach Gardens should begin with a question more personal than financial: where does the household genuinely want to live? Texas and Florida both lack a broad individual income tax. This is not the conventional move from a high-income-tax state to a low-income-tax state. An assumed tax windfall is a poor foundation for choosing a permanent home.
Start with family needs, medical access, travel patterns, community and the practical demands of ownership. A residence should support ordinary weekdays as convincingly as an extended holiday. For a buyer considering The Ritz-Carlton Residences® Palm Beach Gardens, the first task is to assess how the particular home would serve those routines, then test its full carrying costs with advisers.
The wider Palm Beach search deserves the same discipline. If West Palm Beach enters the conversation through Alba West Palm Beach, compare locations against the household's actual calendar rather than treating different residential settings as interchangeable. Tax planning should support a sound residence choice, not manufacture one.
Consider appointing the lead CPA or family office to coordinate the move. The role is not to replace specialist advice, but to keep the Texas, Florida and any other relevant jurisdictional analyses aligned. The purchase closing, physical move and claimed domicile change should not become three conflicting stories.
Maintain one relocation file covering the proposed chronology, use of the Austin property, identification and address changes, travel records, homestead applications and estate-plan revisions. Ask each adviser to identify the obligations within their remit and flag unresolved assumptions. A shared written record separates decisions already made from those still contingent on the property purchase.
Avoid a generic instruction to prepare a “final Texas return.” Neither state has a broad individual income tax. Identify continuing business, property or other filing obligations individually. Florida residence does not eliminate federal taxes or taxes that remain applicable elsewhere.
Domicile concerns the permanent home; residency can carry additional meanings under different jurisdictions' rules. A person can be considered a resident of more than one state while having only one domicile. Florida's residency framework centers on a person's true, fixed and permanent home and principal establishment-not simply a new mailing address.
A declaration of domicile, qualification for homestead exemption and Florida voter registration can provide evidence of residency. None substitutes for consistent conduct. Advisers should reconcile home-use history, identification, addresses and continuing ties to other states so the paperwork reflects the household's actual life.
Spending 183 days in Florida is not a universal domicile solution. Some jurisdictions apply separate statutory-residency tests involving an available abode and a day-count threshold. Ask advisers to analyze each relevant state's rules separately rather than importing one familiar number into every jurisdiction.
Keeping the Austin residence may suit the family, but its future use deserves an explicit decision. Will it remain available for personal stays, be held for another purpose, or be sold? Continued access to a former residence can complicate the evidence supporting a new domicile. It should not disappear from the relocation discussion simply because a Florida purchase has closed.
Document the intended arrangement and revisit it if actual use changes. Maintain travel and day records, particularly when business or family commitments involve other states. This is a coordination practice, not a claim that one tracking method satisfies every jurisdiction.
If evaluating Mr. C Residences West Palm Beach alongside Palm Beach Gardens options, make the permanent-home question explicit. Is the Florida residence intended to be the household's principal home, or another address in a multi-home life? The answer should guide both the purchase brief and the advisers' analysis.
The seller's current property-tax bill is not the buyer's forecast. Florida's Save Our Homes assessment limitation is distinct from the homestead exemption and can create a difference between market value and assessed value. A change of ownership can reset an assessment previously protected by that limitation.
Before committing, request a buyer-specific property-tax estimate and examine insurance, property risk, maintenance and any applicable association costs. These are due-diligence recommendations, not assertions about a particular building's expenses. Base the comparison on the prospective household's ownership circumstances, not the seller's historical position.
Apply the same discipline if the search includes Forté on Flagler West Palm Beach. A compelling residence still requires a clear annual ownership budget. Keep lifestyle preferences and financial assumptions visible side by side so neither obscures the other.
Florida's homestead exemption reduces the taxable value of an eligible permanent residence and is administered through the county property appraiser. The standard application deadline is March 1. Confirm eligibility, required documentation and any late-filing procedures with the county property appraiser rather than assuming the purchase itself establishes entitlement.
Texas homestead benefits do not transfer to Florida. Florida portability concerns the assessment difference from a previous Florida homestead to a new Florida homestead. An Austin property cannot supply that benefit, although a qualifying earlier Florida homestead could create an opportunity.
Eligible portability applicants must establish the new homestead within three years of January 1 of the year they abandoned the previous Florida homestead. A portability claim requires Form DR-501T alongside the new home's homestead application, Form DR-501. Keep these legal requirements separate from the household's preferred moving timetable and the advisers' recommended coordination steps.
Domicile can matter beyond annual income-tax filings. For federal estate- and gift-tax purposes, residency is effectively a domicile concept, making a coordinated review important where those rules apply. Ask estate counsel and the tax team to examine the relevant documents and address records together.
The objective is a coherent transition: a home chosen for living, a carrying-cost budget built for the buyer, and records that accurately reflect the move. A successful purchase should make the relocation easier to sustain, not require the household to reshape its life around a tax assumption.
For a discreet residential search shaped around your priorities, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationTexas and Florida both lack a broad individual income tax, so this is not a conventional state-income-tax arbitrage. Compare actual ownership costs and any continuing tax obligations instead.
A person can be considered a resident of more than one state while having only one domicile. Domicile concerns the permanent home, while residency rules can vary by jurisdiction.
No. Florida's residency framework centers on a true, fixed and permanent home, supported by evidence and consistent conduct.
No, a 183-day count is not a universal domicile rule. Advisers should analyze each relevant state's domicile standards and any separate statutory-residency test.
Retaining it warrants an explicit decision about its use. Continued access to a former residence can complicate the evidence supporting a new domicile.
A practical recommendation is to have the lead CPA or family office maintain one shared relocation file. It should align the move chronology, property use, travel records, filings and estate-plan review.
The standard deadline is March 1. Confirm eligibility, documentation and any late-filing procedures with the Palm Beach County Property Appraiser.
No. Florida portability concerns the assessment difference from a previous Florida homestead, not a Texas residence.
Eligible applicants must establish the new homestead within three years of January 1 of the year they abandoned the previous Florida homestead. The claim requires Form DR-501T alongside Form DR-501.
A change of ownership can reset an assessment previously protected by Save Our Homes. Obtain a buyer-specific estimate rather than relying on the seller's existing tax position.