A buyer-side framework for evaluating Mandarin Oriental Residences, West Palm Beach, separating project contingencies from family-office authorization, funding documentation, and secure payment procedures.
An exceptional waterfront address deserves an equally disciplined acquisition process. For a family office considering Mandarin Oriental Residences, West Palm Beach, the decision turns on three distinct questions: what is being purchased, who has authority to commit capital, and how that capital will reach the intended recipient.
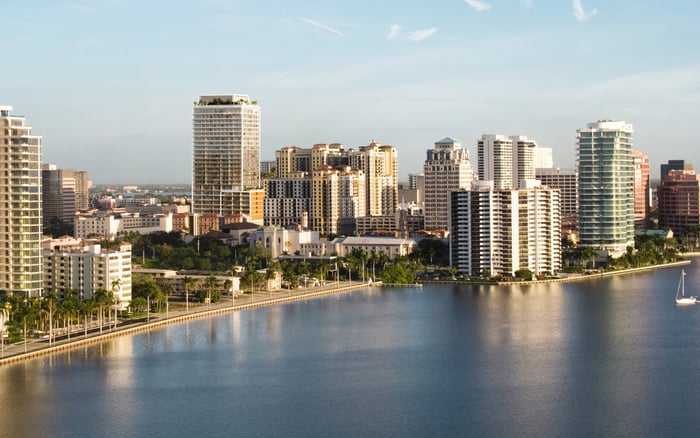
The announced development is planned for 5400 North Flagler Drive in West Palm Beach, on the Intracoastal Waterway. Great Gulf is the announced developer, with plans for 87 private residences. Those details establish the proposition; they do not replace a review of the purchase agreement, condominium documents, approval status, or payment instructions.
The controls below are buyer-side recommendations, not representations of this project's purchase requirements or payment policies. Their purpose is to preserve discretion and decision quality, without allowing a compelling lifestyle narrative to substitute for documented authority.
The first review should separate announced plans from contractual commitments. Improvements, designs, and construction remain subject to appropriate federal, state, and local permits and approvals. Those contingencies do not establish which approvals have already been obtained.
Ask counsel to identify the documents establishing current approval status, the seller's obligations, and the consequences of material changes. Assess delivery expectations through the agreement rather than treating a marketing timetable as a guarantee. A family office should model the implications of a longer holding period for liquidity and personal use, without assigning an unsupported completion date.
A buyer also considering Alba West Palm Beach can use the same comparison framework: documented obligations, unresolved contingencies, and capital committed at each stage. This is a framework for evaluating contracts, not a claim that the projects share terms, approvals, or delivery schedules.
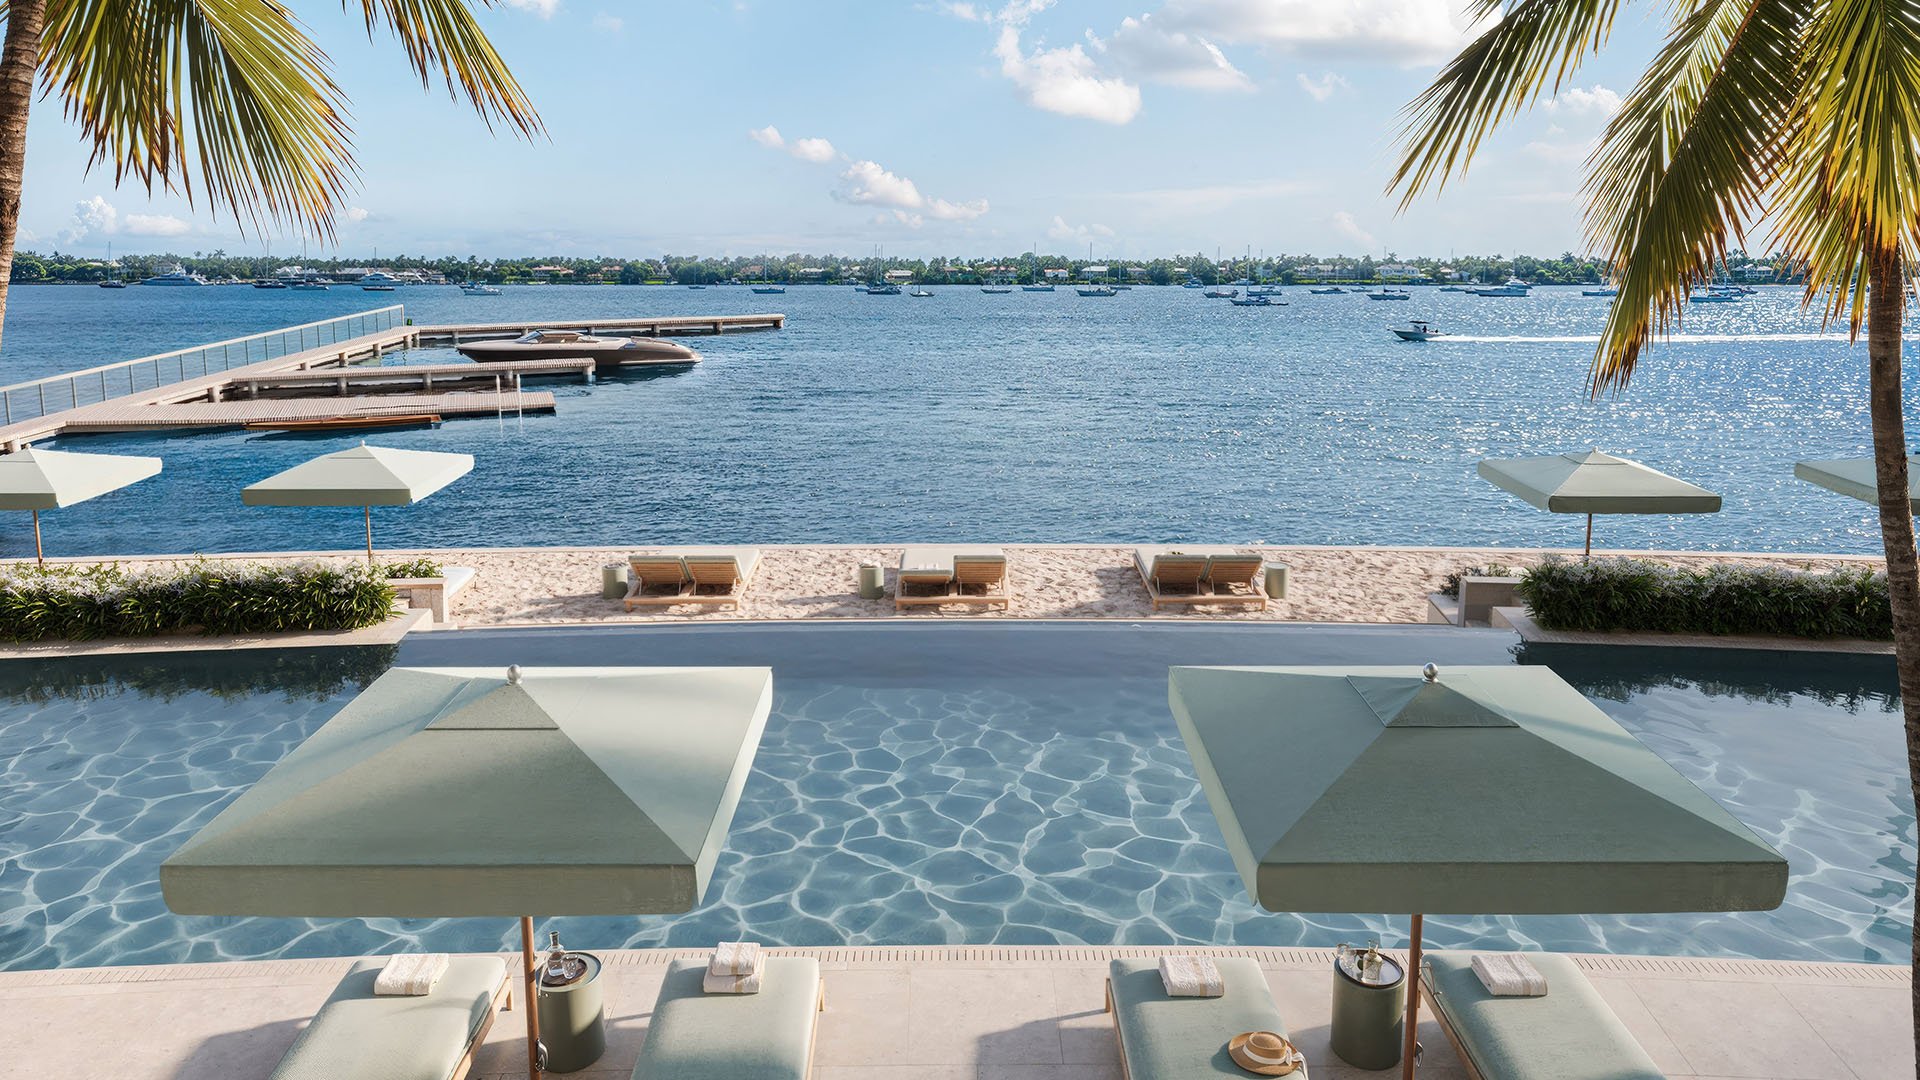
The Intracoastal setting and proposed boating component should not be treated as a single promise. Dock and boat-slip construction is separately contingent on applicable federal, state, and local permits and approvals. Dock and boat-slip plans also remain subject to change in the developer's sole and absolute discretion.
If boating access materially influences the purchase, counsel should examine whether the buyer receives an enforceable right, how that right would be allocated, and what happens if the contemplated facilities change. Availability, use restrictions, costs, and remedies belong in the document review-not in assumptions about waterfront ownership.
The same discipline can guide a comparison with Forté on Flagler West Palm Beach. Compare each property's documented relationship between the residence and the buyer's intended lifestyle, without inferring equivalent boating access or legal rights from an address or presentation.
A practical approval memorandum should identify the proposed purchaser, intended ownership structure, authorized signatories, capital allocation, and unresolved conditions. Counsel and tax advisers should evaluate the ownership choice before execution, rather than assume a later substitution will be permissible.
Separate investment approval from payment authorization. A principal may approve the acquisition while another designated person confirms that a particular deposit is due, correctly calculated, and payable to the contractually identified recipient. A second reviewer can reconcile the instruction with the agreement before the bank releases funds.
Recommended approval gates include contract execution, each scheduled deposit, material amendments, and closing. At each gate, retain the approved document version and record who authorized the action. Set an internal escalation rule for changed recipients, revised account details, unexpected urgency, or requests that depart from the agreement.
These are proposed governance measures, not identified developer procedures. Their value lies in clarity: sales, legal, and treasury decisions should remain distinct, even when the same principal ultimately controls all three.
A useful funding file should explain both the origin of the purchase money and its route into the paying account. These questions are related but distinct. A description of longstanding family wealth does not, by itself, reconcile a particular transfer from an entity or trust.
As a buyer-side preparation exercise, consider organizing purchaser identification, relevant entity or trust authority, account ownership evidence, and records supporting the transaction that generated the funds. Depending on the circumstances, these might relate to a business sale, investment redemption, distribution, or other documented liquidity event. Confirm actual requirements with the relevant transaction parties before transmitting sensitive material.
Use a concise index to connect the proposed purchaser, funding entity, paying account, and authorized signatories. Where these differ, ask counsel to resolve the explanation and any contractual implications before payment.
Discretion also requires restraint. Share only what is appropriately requested, independently confirm the recipient and transmission channel, and establish access and retention expectations. A well-organized file should clarify the transaction without creating an unnecessary archive of private family information.
Treat payment verification as a task separate from receiving payment instructions. As a recommended control, independently confirm the recipient's identity and account details through a previously established, trusted contact channel. Do not rely solely on a telephone number supplied in the same message as the wire instructions.
Before release, reconcile the beneficiary name, account details, amount, and payment purpose with the approved transaction documents. Have a second authorized reviewer check the instruction and verification record. Any change to the destination account should trigger a fresh review, not merely an acknowledgment of the new email.
Timing pressure should not override that gate. A request to bypass verification warrants escalation even when the underlying purchase is approved. If a transfer appears misdirected, promptly contact the sending bank to request intervention and notify counsel through trusted channels. Do not assume recovery is assured.
This is a suggested treasury protocol, not a description of the project's escrow arrangements or security procedures. The actual recipient and treatment of deposits require transaction-specific confirmation.
Brand appeal does not remove the need to examine condominium economics. Florida's milestone-inspection framework generally covers residential condominium and cooperative buildings with three habitable stories or more. An initial inspection is generally required in the year a covered building reaches 30 years, followed by recurring inspections. This should not be treated as an immediate inspection requirement for every proposed building.
Structural integrity reserve-study provisions address inspected items, remaining useful life, replacement costs or deferred-maintenance expenses, and reserve-funding schedules. Ask counsel and financial advisers how the applicable framework informs future association obligations.
Ask counsel to confirm which condominium disclosures apply to the transaction, including any concerning incomplete required milestone inspections, turnover inspection reports, or structural integrity reserve studies. Confirm the operative requirements and transaction category at signing.
When comparing Mr. C Residences West Palm Beach, apply the same cost-review discipline without assuming identical budgets, reserves, or obligations.
Before signing or funding, bring the legal review, capital authorization, funding explanation, and payment verification into one decision record. Identify unresolved conditions and who may accept them. The goal is not friction for its own sake, but a purchase whose operational discipline matches its residential ambition.
Explore South Florida residences with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe development is planned for 5400 North Flagler Drive in West Palm Beach, on the Intracoastal Waterway.
Great Gulf is the announced developer. The announced plans comprise 87 private residences.
No. They establish that improvements, designs, and construction are contingent on appropriate approvals, not which approvals have already been obtained.
No. Dock and boat-slip construction is contingent on applicable approvals, and the plans are subject to change in the developer's sole and absolute discretion.
No. They are buyer-side recommendations for separating acquisition approval, legal review, and payment authorization.
As a preparation exercise, it should connect the origin of the purchase money with the purchaser, funding entity, and paying account. Actual documentation requirements should be confirmed with the relevant transaction parties.
A recommended control is to pause release and independently reverify the recipient and account details through a trusted contact channel. A second authorized reviewer should check the revised instruction before payment.
Promptly contact the sending bank to request intervention and notify counsel through trusted channels. Recovery should not be assumed.
They address useful-life estimates, replacement costs or deferred-maintenance expenses, and reserve-funding schedules. Those considerations can inform an assessment of future association obligations.
Ask counsel which disclosures apply concerning incomplete required milestone inspections, turnover inspection reports, or structural integrity reserve studies. Counsel should confirm the operative requirements and transaction category at signing.