A move to Palm Beach Gardens requires more than a new address. For family-office principals, New York day counts, the retained Manhattan residence, and a consistent Florida domicile record deserve coordinated attention.
For a family-office principal moving from Manhattan to Palm Beach Gardens, selecting a residence is only part of the transition. The more consequential task is ensuring that daily life, travel patterns, and personal records reflect the same move. A Florida address should represent an actual principal home, not merely a winter destination with redirected correspondence.
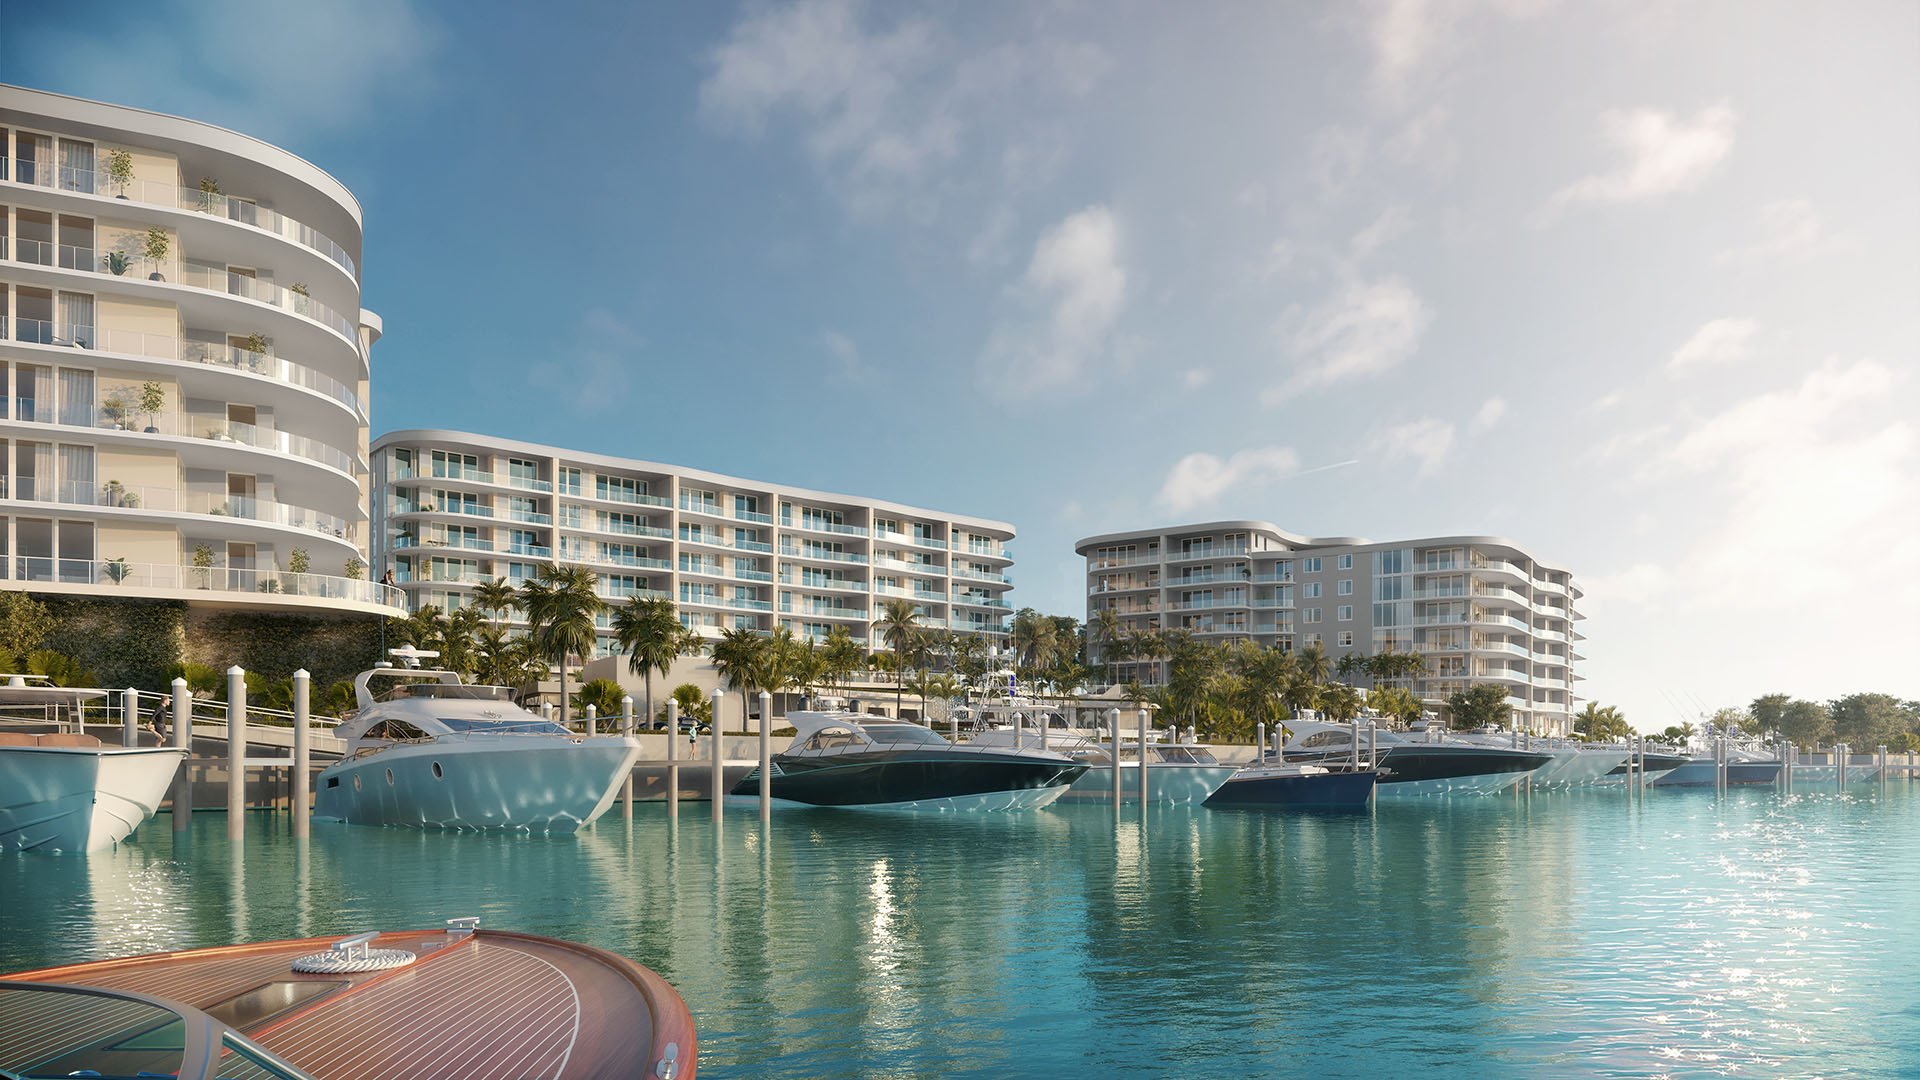
A buyer considering The Ritz-Carlton Residences® Palm Beach Gardens should therefore evaluate more than the property itself. The practical question is whether the home will become the household’s genuine center of return. Purchasing a residence does not, by itself, settle domicile or eliminate New York residency exposure.
The planning framework has three parts: understand the two New York residency routes, count travel correctly, and maintain a documentary record consistent with the relocation. Each deserves attention before the family settles into its new routine.
New York has two distinct routes to individual residency: domicile and statutory residency. Treating them as interchangeable creates a significant planning blind spot.
The statutory-residency test generally requires both a permanent place of abode in New York for substantially all of the taxable year and at least 184 New York days. Remaining at 183 days or fewer avoids the day-count component of that test. It does not, by itself, establish that New York domicile has ended.
Conversely, establishing Florida domicile does not necessarily remove statutory-residency exposure. A person who retains a qualifying Manhattan apartment and meets the New York day threshold can still face that separate test.
For the family office, the implication is straightforward: maintain two parallel reviews. One addresses where the principal’s permanent home actually is. The other addresses the New York residence and the individual’s physical presence in the state. A favorable answer to one does not replace a review of the other.
An overnight calendar is not a sufficient New York day-count system. Any part of a day generally counts as a New York day, so a meeting followed by a same-day return to Florida can matter even when no Manhattan bedroom is used.
Consider a hypothetical trip: arrival in New York on Monday evening and departure on Wednesday morning. Under the general partial-day rule, all three dates count, despite only two overnight stays. Counsel should review applicable exceptions, particularly for transit or unusual travel, before the office determines the final treatment.
Maintain a separate calendar for each taxpayer rather than treating the household itinerary as a single record. Capture arrivals, departures, partial-day visits, overnight locations, and supporting travel documents. Shared trips do not mean every family member has an identical annual count.
Reconcile the calendar regularly against itineraries, invoices, card activity, and meeting records. Preserve the underlying documents as well as the spreadsheet. An internal travel buffer may be useful, but it is a planning choice-not a different statutory threshold.
The Manhattan apartment deserves its own review. A permanent place of abode is generally a residence maintained by the taxpayer that is suitable for year-round use. Ownership is not essential; a maintained rental can also qualify.
That distinction matters for families who sell one apartment but retain another arrangement, or assume that leasing rather than owning resolves the issue. The analysis extends beyond the name on a deed.
Document whether the residence remains available for personal use, and have counsel assess the actual arrangement. Do not assume that ownership, a sale, or a subletting decision alone answers every residency question. Review the apartment’s treatment alongside the travel calendar rather than leaving it as a separate real-estate administrative matter.
Florida residency centers on a true, fixed, permanent home and principal establishment, rather than a simple minimum number of Florida days. The central question is where the person intends to return whenever absent.
For buyers comparing Palm Beach Gardens with West Palm Beach, including Alba West Palm Beach, the useful distinction is between a property that accommodates visits and a home that supports ordinary life. Neither a prestigious address nor an acquisition price answers that question.
The same discipline applies when considering Mr. C Residences West Palm Beach as part of a broader Palm Beach area search. Identify which residence will actually serve as the permanent home, and organize the relocation around that decision. Paperwork should not be asked to establish an intention that daily life does not support.
Travel need not disappear. The objective is a coherent account of where home is when the family returns, supported by conduct and records rather than an address alone.
A declaration of domicile, voter registration, and qualification for homestead exemption can help establish Florida residency. A Florida driver’s license and vehicle registration can indicate intent, but are not necessarily conclusive on their own.
The family office should coordinate household, banking, insurance, tax, estate-planning, and administrative records with the actual relocation chronology. This is an exercise in consistency, not an invitation to manufacture uniformity. Document legitimate exceptions, and ensure dates reflect what happened.
Homestead planning adds a specific timing consideration: permanent Florida residency is required as of January 1 for the applicable tax year. The application requests the declaration-of-domicile date and collects evidence including driver’s-license, vehicle-registration, voter-registration, and federal-tax-return address information.
Those fields make sequencing important. Before applying, review whether the claimed residency date and supporting documents tell a consistent story. A later administrative update should not be presented as though it occurred earlier.
Assign responsibility for calendar maintenance, document retention, and periodic reconciliation. Have personal tax and legal advisers review unresolved travel days, the retained Manhattan residence, and the claimed domicile transition before assumptions become embedded in filings.
Keep the scope clear: individual residency and homestead planning do not establish the separate tax treatment of family-office entities, trusts, partnerships, or employees. Those questions require their own analysis.
The best-organized move is not the one with the most paperwork. It is the one in which the home, the calendar, and the records consistently describe the same life. This framework is general information, not individualized tax or legal advice.
Explore a South Florida residence that fits your family’s next chapter with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. It avoids the day-count component of New York’s statutory-residency test, but does not by itself establish that New York domicile has ended.
The test generally requires both a permanent place of abode in New York for substantially all of the taxable year and at least 184 New York days.
Any part of a day generally counts, even without an overnight stay. Counsel should review applicable exceptions for transit and unusual travel.
Yes. Ownership is not essential; a maintained rental suitable for year-round use can qualify.
Yes. Retaining a qualifying New York residence and meeting the day-count requirement can create statutory residency despite Florida domicile.
As an operational practice, maintain a separate calendar for each taxpayer. Record arrivals, departures, partial-day visits, overnight locations, and supporting documents.
It should function as the true, fixed, permanent home and principal establishment, including the place the person intends to return whenever absent.
No. A Florida driver’s license and vehicle registration can indicate intent, but are not necessarily conclusive by themselves.
Permanent Florida residency is required as of January 1 for the applicable tax year. The application also requests residency evidence and the declaration-of-domicile date.
No. Individual residency and homestead planning do not determine the separate tax treatment of entities, trusts, partnerships, or employees.